Julia Chirkova
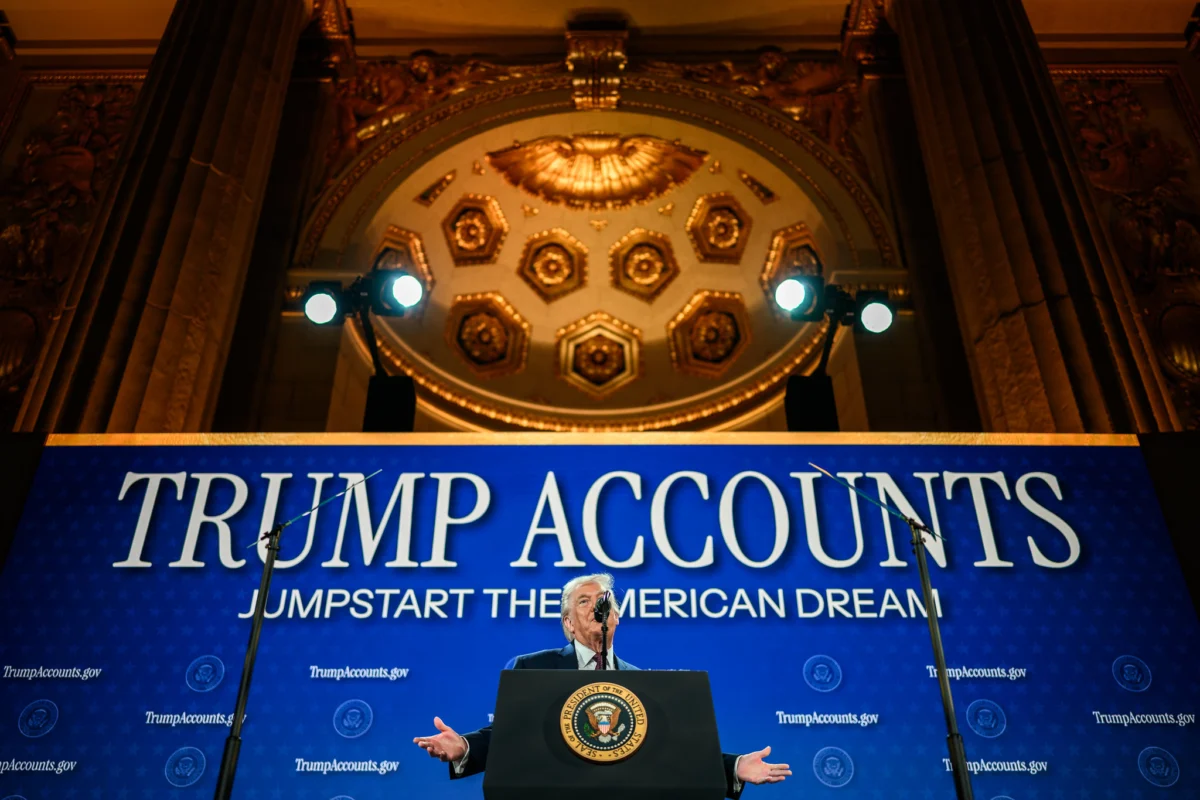
WASHINGTON D.C. – The U.S. Treasury Department has issued new guidance that will implement an automatic enrollment process for "Trump Accounts," a significant shift from the current opt-in system. This change, slated to take effect on October 1, 2026, is projected to create accounts for an additional 60 million American children under the age of 18, dramatically expanding the program’s reach. Currently, approximately 73 million children are eligible for these tax-advantaged savings accounts, with roughly 7 million having enrolled since their launch on July 4, 2026.
The transition to auto-enrollment is a strategic move aimed at broadening access, particularly among low- and moderate-income families. Previously, parents or guardians were required to actively sign up their children for the program. This manual process has resulted in a relatively low participation rate among families earning up to $80,000 annually, with only about 5% having opened a Trump Account. Proponents of the auto-enrollment policy argue that it will streamline the process, remove barriers to entry, and potentially unlock greater private sector contributions to these child savings accounts.
Understanding "Trump Accounts" and Their Objectives
"Trump Accounts" are designed as tax-advantaged savings vehicles available to any child in the United States under the age of 18 who possesses a Social Security number. A key feature of the program, introduced at its inception, provides a federal seed investment of $1,000 to children born between January 1, 2025, and December 31, 2028. This initial funding is provided irrespective of family income, aiming to offer a foundational financial boost to a broad segment of the youngest generation.
Beyond the initial federal contribution, the accounts allow for annual contributions of up to $5,000 from parents, guardians, and other individuals. These funds are typically invested in a diversified portfolio of low-cost index funds. Projections from the White House suggest that if fully funded and left untouched until the beneficiary reaches adulthood, an account could potentially grow to as much as $1.9 million by the age of 28. This ambitious growth projection underscores the program’s intent to foster long-term financial security and provide significant capital for future endeavors.
The Mechanics of Auto-Enrollment and Parent Responsibilities
While the auto-enrollment process will automatically establish an account for eligible children, a crucial step remains for parents or guardians to access the federal seed money and actively manage the account. The initial $1,000 federal contribution will not be automatically deposited. Instead, parents or legal guardians will still need to formally request this funding and officially claim their child’s account before any deposits can be made. This ensures a level of parental oversight and involvement in the financial planning for their children.
The process of establishing an account, even under the new auto-enrollment framework, is designed to be relatively straightforward. It involves filing IRS Form 4547, which can be completed concurrently with tax filings or at any other point during the year. The Internal Revenue Service (IRS) estimates that the time required to set up an account is between five and ten minutes, minimizing the administrative burden on families.
Funds withdrawn from Trump Accounts for qualified expenses are accessible without penalty at age 18. These qualified expenses are broadly defined to include significant life events and investments, such as educational pursuits, the purchase of a home, or the establishment of a business. However, it is important to note that while withdrawals for these purposes are not penalized, they are subject to taxation at ordinary income rates and may be subject to additional regulatory restrictions.
Background and Policy Context
The introduction of "Trump Accounts" and the subsequent shift to automatic enrollment represent a significant policy initiative focused on youth financial literacy and long-term wealth building. Launched on July 4, 2026, the program emerged during a period of increased focus on economic security for future generations and addressing wealth inequality. The naming of the accounts after former President Donald Trump suggests a connection to his economic policies or a desire to associate the initiative with his political brand.
The initial opt-in system was likely implemented to gauge public interest and manage the rollout of a new federal program. However, the low uptake among lower-income families highlighted a critical need for a more inclusive approach. The Treasury Department’s decision to move to auto-enrollment directly addresses this disparity, aiming to ensure that the benefits of the program are accessible to all eligible children, regardless of their parents’ proactive engagement or financial literacy.
Supporting Data and Projected Impact
The statistics surrounding the current enrollment figures paint a clear picture of the potential impact of auto-enrollment. With approximately 73 million children eligible and only 7 million having opted in, the current participation rate stands at just under 10%. The projected addition of over 60 million children through automatic enrollment could more than double the program’s reach, bringing the total number of enrolled children to over 70 million, representing nearly 96% of all eligible children.
The emphasis on low- and moderate-income families is particularly noteworthy. These demographic groups often face greater financial challenges and may have less access to traditional savings and investment vehicles. By automatically enrolling these children, the program aims to provide a critical starting point for wealth accumulation that might otherwise be unattainable. The current statistic of only 5% of families earning up to $80,000 annually having opened accounts underscores the effectiveness gap of the opt-in model. Auto-enrollment is expected to significantly close this gap.
The potential for account growth to $1.9 million by age 28, while dependent on consistent contributions and investment performance, offers a compelling vision of long-term financial empowerment. This projection could significantly alter the economic trajectory for millions of young Americans, providing them with substantial capital for higher education, entrepreneurial ventures, or homeownership.
Potential Reactions and Broader Implications
The shift to auto-enrollment is likely to elicit varied reactions from policymakers, financial institutions, and the public.
Government and Policy Analysts: Proponents will hail the move as a progressive step towards greater financial inclusion and a proactive measure to address future economic disparities. Critics, however, may raise concerns about parental rights, the potential for government overreach, and the administrative complexities of managing such a large-scale automatic enrollment system. Discussions are also likely to emerge regarding the long-term sustainability of the federal seed funding and the program’s overall fiscal impact.
Financial Institutions: The surge in new accounts could present significant opportunities for investment firms and financial service providers. The management of these passively invested accounts, along with the potential for increased parental contributions and subsequent financial planning needs, could create a substantial new market. Conversely, institutions that primarily rely on actively managed funds or higher-fee products may face increased competition from the low-cost index fund model inherent in Trump Accounts.
Parents and Families: For parents who were hesitant or unable to navigate the opt-in process, auto-enrollment will be a welcome development, offering a straightforward path to securing a financial head start for their children. However, those who prefer complete control over their financial decisions may feel apprehensive about accounts being established without their explicit initial consent. Educational outreach will be crucial to ensure parents understand their rights and responsibilities within the new system.
The broader implications of this policy extend to the national savings rate and future economic productivity. By encouraging early savings and investment, the program has the potential to boost the overall capital available for investment in the economy. Furthermore, equipping young adults with significant financial resources could foster greater entrepreneurship and economic mobility.
The success of the auto-enrollment strategy will hinge on effective communication, streamlined administrative processes, and continued public engagement. The Treasury Department’s forthcoming guidance will be critical in detailing the precise implementation steps and addressing any potential challenges that may arise as this significant expansion of the "Trump Accounts" program unfolds. The coming months will be pivotal in shaping the future financial landscape for millions of American children.