

 Lina Irawan
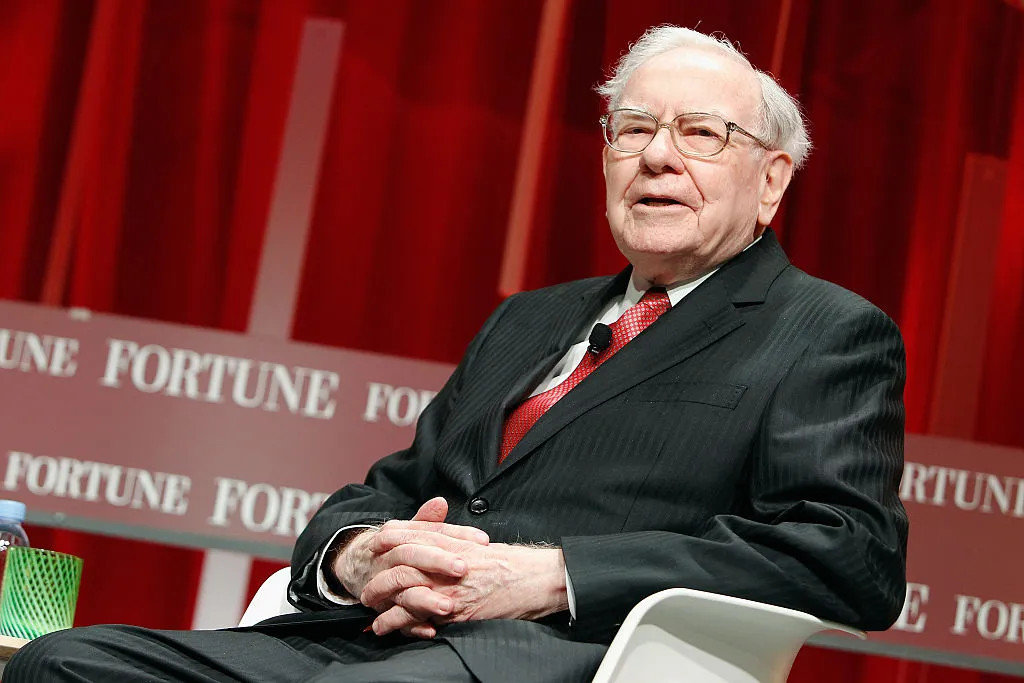
The investment philosophy championed by legendary investor Warren Buffett, encapsulated in his iconic advice to "be greedy when others are fearful, and fearful when others are greedy," has served as a beacon for investors seeking to navigate the tumultuous waters of market cycles. While deceptively simple, this contrarian approach demands extraordinary discipline and conviction, particularly when the broader market sentiment is gripped by panic. Its efficacy was starkly illustrated during the depths of the 2008 financial crisis, when Buffett publicly reiterated this counsel, urging investors to "Buy American." Despite facing several more months of declining stock prices after his pronouncement, those who heeded his long-term vision ultimately reaped substantial rewards, underscoring the profound utility of this timeless strategy for both novice and seasoned investors alike.
The Genesis of a Maxim: Buffett’s Contrarian Philosophy
The roots of Buffett’s famous dictum can be traced back to his 1986 letter to Berkshire Hathaway shareholders, where he articulated his firm’s investment approach: "We simply attempt to be fearful when others are greedy and to be greedy only when others are fearful." This statement is not merely a catchy phrase but the cornerstone of value investing, a methodology that seeks to purchase assets for less than their intrinsic worth. In essence, it advocates for rational decision-making divorced from the prevailing emotional tides of the market. When others are euphoric, often driving asset prices to unsustainable highs (greed), Buffett advises caution and even divestment (fear). Conversely, when widespread panic or pessimism drives fundamentally sound assets to undervaluation (fear), he sees an opportune moment to acquire (greed). This contrarian stance stands in direct opposition to the herd mentality that often characterizes speculative market bubbles and subsequent crashes.
The enduring popularity of this saying surged following its reiteration in Buffett’s October 2008 op-ed for The New York Times, titled "Buy American. I Am." Published at a moment of profound economic uncertainty and investor capitulation during the Great Recession, the article served as a powerful reminder for investors to maintain conviction even when stock prices appeared to be in freefall. Market corrections and crashes, while unsettling, are inherent features of long-term asset accumulation, and history repeatedly demonstrates that their eventual recoveries generously reward patient, disciplined investors.
The Crucible of 2008: A Test of Conviction
To fully appreciate the weight of Buffett’s 2008 advice, it is crucial to revisit the economic landscape of that era. The global financial crisis, ignited by the collapse of the U.S. subprime mortgage market and the subsequent unraveling of complex financial instruments like collateralized debt obligations (CDOs), plunged the world into its deepest recession since the Great Depression. The crisis officially began in December 2007, but its most severe impacts materialized in late 2008.
A Chronology of Collapse and Intervention:
- October 2007: The S&P 500 index reached its pre-crisis peak of 1,565.15, marking a period of relative market optimism.
- September 2008: The bankruptcy of Lehman Brothers, a major investment bank, sent shockwaves through the global financial system, triggering a full-blown panic. Credit markets froze, and major financial institutions faced imminent collapse.
- October 2008: Amid unprecedented market volatility and plummeting asset values, Warren Buffett published his "Buy American. I Am." op-ed. At this juncture, the S&P 500 had already fallen significantly from its peak, but the worst was yet to come. His message was a call for calm and confidence in the long-term prospects of American enterprise, despite the immediate gloom.
- March 2009: The S&P 500 finally bottomed out at 676.53 on March 9, 2009, representing a staggering decline of nearly 57% from its October 2007 peak. This trough occurred several months after Buffett’s op-ed, meaning investors who took his advice immediately still had to endure further portfolio depreciation, a true test of their psychological fortitude.
The sentiment during this period was overwhelmingly negative. News headlines screamed about economic catastrophe, unemployment surged, and many financial analysts predicted a prolonged downturn, some even fearing a systemic collapse of capitalism. In this environment of widespread fear and uncertainty, Buffett’s contrarian stance was not merely advice; it was a profound act of faith in the underlying resilience and innovative capacity of the U.S. economy.
Deconstructing Market Fear: Psychology and Opportunity
Market downturns are not solely economic events; they are deeply psychological. Human beings are hardwired with cognitive biases that often lead to irrational financial decisions, especially during periods of stress.
- Herd Mentality: The tendency to follow the actions of a larger group, often overriding individual rational analysis. During a crash, this manifests as panic selling, as investors observe others liquidating assets and fear being left behind.
- Loss Aversion: The psychological phenomenon where the pain of losing is felt more intensely than the pleasure of gaining an equivalent amount. This drives investors to sell positions to "stop the bleeding," even if it means crystallizing losses at the worst possible time.
- Recency Bias: The inclination to believe that recent events will continue indefinitely into the future. A prolonged market decline can lead investors to believe that markets will never recover, discouraging them from buying.
Buffett’s advice directly counters these inherent psychological pitfalls. By being "greedy when others are fearful," an investor deliberately chooses to act against the prevailing emotional current. This is not a call for blind speculation but an invitation to rationally assess asset values when they are depressed due to collective panic, rather than fundamental deterioration. The fear-driven selling creates opportunities for those with a long-term perspective to acquire quality assets at discounted prices, establishing a greater "margin of safety"—another core Buffett principle.
What Buffett’s Counsel Is Not: Avoiding Reckless Speculation
It is crucial to clarify what Buffett’s iconic saying doesn’t imply. While it champions a contrarian mindset, it is not an endorsement of reckless speculation, such as going "all-in" on a single highly volatile stock or engaging in complex, risky derivatives like speculative options trading without deep understanding. This insight is not an invitation to gamble but a directive to avoid panicking and succumbing to emotional investing when observing others do so.
Buffett’s own investing career is marked by meticulous research, a deep understanding of business fundamentals, and a commitment to acquiring companies with enduring competitive advantages ("moats"). He has never advocated for buying distressed assets simply because they are cheap; rather, he seeks fundamentally sound businesses whose stock prices have been temporarily depressed by market pessimism. He famously advises investors to operate within their "circle of competence," investing only in businesses they thoroughly understand.
Indeed, Buffett has sold shares of various companies throughout his career, but these decisions were typically driven by a change in the company’s underlying fundamentals, its competitive landscape, or its management quality, not merely because its stock value was temporarily under pressure. Selling based on panic locks in losses and, crucially, prevents participation in the inevitable market recovery.
The Empirical Reward of Patience: Data from the Great Recession
The recovery following the 2008-2009 crash provides compelling empirical evidence for Buffett’s wisdom. As noted, the S&P 500 bottomed in March 2009. From that point, the market began a sustained recovery:
- Recovery to Previous Highs: It took approximately four years for the S&P 500 to regain its October 2007 peak. By March 2013, the index had not only recovered all its losses but surpassed its pre-crisis high.
- Long-Term Gains: Investors who maintained their positions or, even better, continued to invest during the downturn (a strategy known as dollar-cost averaging), witnessed significant appreciation. For instance, an investment in the S&P 500 made at the March 2009 low would have more than tripled by 2015 and seen exponential growth in the decade that followed.
- Cost of Missing the Recovery: Data consistently shows that missing even a few of the market’s best-performing days, which often occur during the early stages of a recovery from a downturn, can severely impact long-term returns. Investors who sold out of fear in late 2008 or early 2009 not only locked in their losses but also forfeited the opportunity to participate in one of the most significant bull markets in history.
This historical trajectory underscores that market downturns, while painful, are typically temporary phases within a longer-term upward trend. The U.S. stock market, represented by the S&P 500, has historically generated an average annual return of around 10-12% over the long run, despite numerous corrections, bear markets, and economic crises.
Practical Strategies for Navigating Market Drops
Adhering to Buffett’s advice requires a strategic framework that transcends emotional reactions. When markets are falling, certain practical steps can help investors remain disciplined and capitalize on opportunities:
- Cultivate a Long-Term Mindset: Understand that stock market volatility is normal. Any money invested in stocks that you anticipate needing within the next five to seven years should ideally be in less volatile assets. For long-term goals (retirement, future education), stocks remain a powerful wealth-building tool.
- Avoid Constant Portfolio Monitoring: Excessive checking of portfolio values during a downturn can amplify anxiety and lead to impulsive decisions. Focus on the underlying businesses, not the daily fluctuations of their stock prices.
- Stick to Your Investment Plan: Develop a well-defined investment strategy based on your financial goals, risk tolerance, and time horizon. This plan should include your asset allocation (e.g., percentage in stocks, bonds, cash) and rebalancing rules.
- Embrace Dollar-Cost Averaging: Continue making regular contributions to your investment accounts (e.g., 401(k), IRA). When prices are low, your fixed contribution buys more shares, effectively lowering your average cost per share over time. This automatically implements the "greedy when others are fearful" principle without requiring market timing.
- Rebalance Prudently: Rebalancing involves adjusting your portfolio back to its target asset allocation. During a downturn, this might mean selling some assets that have performed well (e.g., bonds) to buy more of those that have fallen (e.g., stocks). This is a disciplined way to buy low and sell high without emotional input.
- Build a Robust Emergency Fund: A sufficient cash buffer (typically 3-6 months of living expenses) is paramount. This ensures you won’t be forced to sell investments at a loss to cover unexpected expenses during a market downturn, alleviating a major source of financial anxiety. If your market-related anxiety stems from a small cash position, prioritizing building this emergency savings account without selling assets is often the best course of action.
- Focus on Fundamentals: During market drops, revisit the companies you own or are considering buying. Are their business models still sound? Do they have strong balance sheets, competent management, and competitive advantages? A market crash often reveals the true quality of businesses; focus on those that can weather economic storms.
Broader Implications: Financial Literacy and Resilience
The lessons from Buffett’s advice and the 2008 crisis extend beyond mere investment tactics; they underscore the critical importance of financial literacy and personal financial resilience. Understanding market dynamics, the power of compounding, and the psychological traps of investing empowers individuals to make more informed decisions. It highlights that true wealth building is a marathon, not a sprint, demanding patience, discipline, and an unwavering focus on long-term objectives.
Moreover, the emphasis on building cash buffers and understanding one’s own risk tolerance speaks to a broader principle of financial preparedness. A well-constructed personal financial plan, encompassing savings, debt management, and appropriate insurance, acts as a crucial defense against unexpected economic shocks, allowing investors to truly embody Buffett’s advice rather than merely intellectually acknowledge it.
In conclusion, Warren Buffett’s counsel to "be greedy when others are fearful" is far more than a simple investment tip; it is a profound philosophy that challenges human nature and demands rational thought in the face of widespread panic. The 2008 financial crisis provided a vivid, albeit painful, demonstration of its power. For those who possessed the foresight and discipline to embrace this contrarian wisdom, the subsequent market recovery delivered substantial rewards, solidifying its place as one of the most enduring and effective tenets of successful long-term investing. The path to investment success often lies not in predicting the future, but in adhering to sound principles, maintaining conviction, and acting with patience and discipline when others are losing their nerve.








