

 Lina Irawan
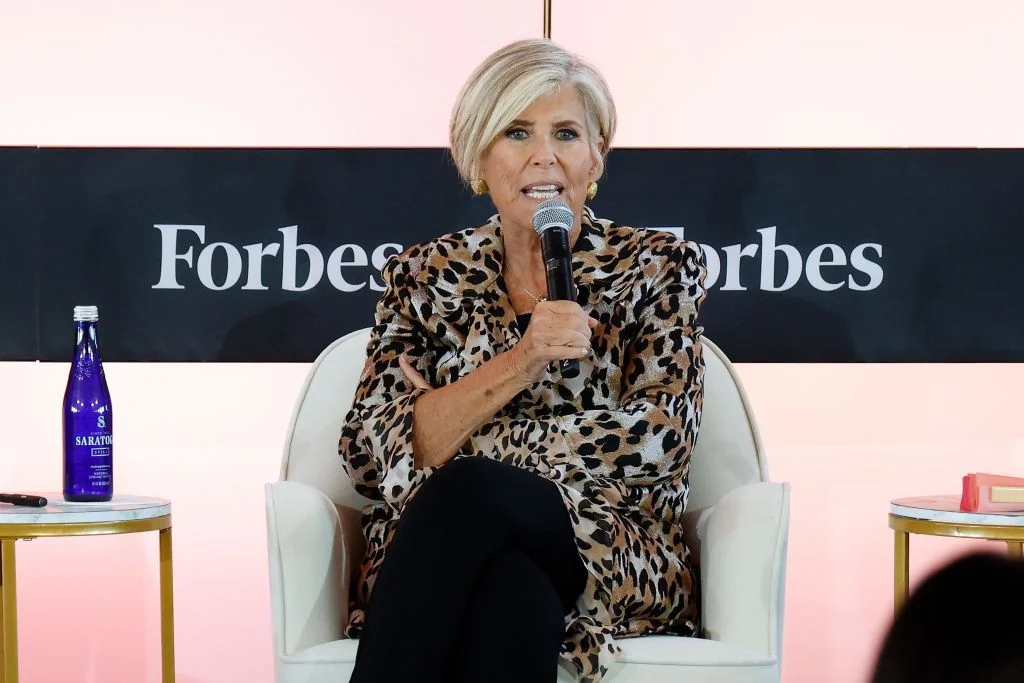
For decades, personal finance titan Suze Orman has delivered her signature brand of "tough love" financial guidance, advocating for stringent debt avoidance, prudent spending, and strategic saving. While these foundational principles remain cornerstones of her philosophy, Orman has increasingly emphasized a critical, yet often overlooked, aspect of financial well-being: peace of mind. This shift reflects a broader understanding that true financial freedom extends beyond mere net worth, encompassing a profound sense of security and mental tranquility. Her recent pronouncements underscore a holistic approach to personal finance, urging individuals to cultivate resilience and emotional stability alongside their investment portfolios.
The Evolution of a Financial Guru’s Philosophy
Suze Orman’s journey to becoming one of America’s most recognizable financial advisors began not in academia, but in a diverse set of professional experiences, including a stint as a waitress before founding her own financial planning firm in 1987. Her career trajectory accelerated with the publication of best-selling books like "The 9 Steps to Financial Freedom" (1997) and her highly popular show, "The Suze Orman Show," which aired on CNBC from 2002 to 2015. Throughout these years, her advice was often direct, unflinching, and intensely practical. She famously championed living below one’s means, avoiding credit card debt at all costs, and diligently building savings. Phrases like "You are your own best investment" and warnings against "fools’ gold" resonated with millions seeking clarity in a complex financial landscape.
However, the global financial crises and periods of heightened economic uncertainty, particularly the 2008 recession and the more recent volatility spurred by the COVID-19 pandemic and inflationary pressures, appear to have deepened Orman’s focus on the psychological dimensions of wealth. While the objective metrics of money — balances, returns, debts — are crucial, Orman now frequently articulates that the subjective experience of financial security is equally vital. Her evolving message acknowledges that external market forces and unforeseen life events can wreak havoc not just on bank accounts, but on mental and emotional well-being. This shift isn’t a departure from her core tenets, but rather an enrichment, integrating psychological resilience into the framework of sound financial planning.
The Indispensable Role of a Cash Buffer
Central to Orman’s current emphasis on peace of mind is the maintenance of a robust cash buffer, commonly known as an emergency fund. She views these accessible reserves not merely as a safety net, but as a critical psychological shield against the unpredictable nature of life and markets. The concept is straightforward: having readily available cash to cover unexpected expenses prevents individuals from resorting to high-interest debt, liquidating long-term investments at inopportune moments, or experiencing debilitating financial stress during crises.
Financial advisors typically recommend holding enough cash to cover at least three to six months of essential living expenses. For individuals with less stable income, significant health concerns, or dependents, this recommendation often extends to nine or even twelve months. Data consistently highlights the precarious position many Americans face without such a buffer. A Federal Reserve report on the economic well-being of U.S. households frequently reveals that a significant percentage of adults would struggle to cover an unexpected $400 expense using cash or an equivalent. For example, the 2022 report indicated that 37% of adults would not be able to cover such an expense or would have to sell something or borrow money. This statistic underscores the pervasive vulnerability that Orman aims to address.
The psychological benefit of an adequate emergency fund cannot be overstated. Knowing that a job loss, a sudden home repair, or an unforeseen medical bill can be managed without derailing one’s entire financial plan provides immense relief. This stability allows individuals to navigate market headlines and economic downturns with greater equanimity, rather than succumbing to panic. During periods of market volatility, an emergency fund ensures that investors are not forced to sell their holdings at a loss, thus preserving their long-term growth potential.
For retirees, the importance of an accessible cash fund is amplified, particularly concerning healthcare costs. Orman frequently highlights that medical expenses can become a significant and often underestimated burden in retirement. While Medicare covers a portion of costs, it has substantial gaps, including deductibles, co-insurance, and prescription drug costs, not to mention long-term care, which Medicare generally does not cover. According to Fidelity Investments’ 2023 estimates, an average retired couple aged 65 could need approximately $315,000 saved (after tax) to cover healthcare expenses throughout retirement. This figure does not include potential long-term care costs, which can range from tens of thousands to well over $100,000 per year for assisted living or nursing home care. Having a dedicated cash reserve or an easily accessible portion of one’s portfolio specifically for these potential healthcare "surprises" is, in Orman’s view, paramount to maintaining peace of mind in one’s later years. It allows retirees to focus on enjoying their retirement rather than constantly worrying about the next medical bill.
The Imperative of Emotional Discipline in Investing
Beyond the practicalities of cash reserves, Orman dedicates considerable attention to the psychological pitfalls that can derail even the most meticulously planned investment strategies. She steadfastly advises against letting emotions cloud investment decisions, identifying the "Fear of Missing Out" (FOMO) as a particularly insidious trap. In an age of instant information and social media-driven trends, the temptation to chase speculative assets or jump into rapidly appreciating markets is ever-present. Investors, observing others seemingly striking it rich, can develop a sense of being "behind" or missing out on easy gains.
This FOMO often leads to imprudent decisions: investing in highly volatile assets without understanding the underlying risks, abandoning a well-diversified portfolio for a single "hot" stock, or allocating an outsized portion of one’s capital to unproven ventures. History is replete with examples of such speculative bubbles, from the Dutch Tulip Mania in the 17th century to the Dot-com bubble of the late 1990s and, more recently, surges in certain cryptocurrencies and "meme stocks." Invariably, these episodes conclude with significant losses for those who entered at the peak, driven by emotion rather than fundamental analysis. Behavioral economics research consistently demonstrates how cognitive biases like herd mentality, recency bias, and overconfidence can lead investors astray. Orman’s counsel serves as a crucial antidote to these tendencies, urging a disciplined, long-term perspective.
A core tenet of this emotional discipline is diversification. Orman emphasizes the importance of spreading investments across various asset classes, industries, and geographies. This strategy, rooted in Modern Portfolio Theory, aims to reduce overall portfolio risk without necessarily sacrificing returns. By not putting "all your eggs in one basket," investors can mitigate the impact of any single asset or sector underperforming. While diversification doesn’t guarantee profits or protect against all losses, it significantly smooths out the investment journey, making it easier for investors to remain calm during market downturns and adhere to their long-term plans.
The need for emotional control and diversification becomes even more pronounced as investors approach and enter retirement. Orman highlights the critical concept of "sequence of returns risk." This refers to the danger that poor investment returns early in retirement can have a disproportionately negative impact on a portfolio’s longevity, even if later returns are strong. A substantial market downturn early in retirement, when withdrawals are being made, can significantly deplete a portfolio, leaving less capital to recover when the market eventually rebounds. Given that retirees have a shorter time horizon to recover from significant losses compared to younger investors, Orman advocates for gradually reducing exposure to higher-risk assets like stocks and increasing allocation to lower-risk assets like bonds as retirement nears. This balanced approach, while potentially reducing peak returns during bull markets, offers greater stability and, crucially, makes it "easier to sleep at night." If one’s entire net worth is subject to dramatic swings based on a week of negative headlines, the psychological toll can be immense. Diversification, coupled with a conservative allocation strategy for those in or near retirement, minimizes the risk of having to drastically cut back on essential living expenses during a stock market correction, thereby safeguarding financial peace of mind.
Cultivating Holistic Financial Peace of Mind
Ultimately, Suze Orman’s recent emphasis culminates in the broader concept of cultivating holistic financial peace of mind, defining financial freedom not merely by the amount of money accumulated, but by the absence of worry about "what-ifs." This goes beyond just savings and investments to encompass a comprehensive review of one’s entire financial architecture.
A critical component of this holistic approach is ensuring adequate insurance coverage. Orman strongly recommends regularly reviewing all insurance policies — life, health, disability, long-term care, home, and auto. These policies are not investments designed to grow wealth; rather, they are protective mechanisms designed to mitigate catastrophic financial losses from unforeseen events. For instance, life insurance provides financial security for dependents in the event of an untimely death, while disability insurance protects income should one become unable to work. Long-term care insurance, though often expensive, can be a vital safeguard against the exorbitant costs of extended care in later life. According to the American Council of Life Insurers (ACLI), a significant portion of the U.S. population remains underinsured, leaving their families vulnerable to severe financial hardship. A thorough review ensures that coverage amounts are appropriate, policies are up-to-date, and premiums are manageable, thereby eliminating a major source of potential "what-if" anxiety.
Equally important, and often overlooked, is the meticulous updating of beneficiary designations on all financial accounts, including retirement plans (401(k)s, IRAs), life insurance policies, and investment accounts. Orman stresses that these designations dictate who receives your assets upon your passing, overriding instructions in a will. Outdated beneficiaries (e.g., an ex-spouse, a deceased relative) can lead to protracted legal battles, unintended heirs, and significant delays in asset distribution, creating immense stress and financial burden for surviving family members. A simple annual check of these designations can prevent a future nightmare, offering peace of mind that one’s wishes will be honored without complication.
While not explicitly detailed in the original article, the concept of "what-ifs" inherently extends to broader estate planning. Orman’s philosophy would logically encompass the creation of essential documents like a will, living trust (if appropriate), and powers of attorney for finances and healthcare. These documents ensure that an individual’s assets are distributed according to their wishes, and that financial and medical decisions can be made by trusted individuals if they become incapacitated. The absence of such planning is a profound source of "what-if" anxiety, potentially leaving loved ones in legal and financial limbo.
Finally, Orman challenges individuals to integrate this peace-of-mind metric into their daily financial decisions, particularly when considering significant purchases. Before making a large expenditure — whether for a new car, a home renovation, or a luxury vacation — she advises asking a fundamental question: "Will this purchase increase or decrease my peace of mind?" This introspective query forces a re-evaluation of priorities, moving beyond immediate gratification to consider the long-term impact on financial stability and mental tranquility. A lavish purchase that necessitates drawing down emergency savings, incurring significant debt, or delaying essential financial goals might provide temporary joy but ultimately erode peace of mind. Conversely, foregoing an impulse buy to bolster savings or pay down debt can create a deeper, more enduring sense of security.
Broader Impact and Implications
Suze Orman’s continued evolution in financial advice reflects a significant trend within the broader financial planning industry. There is a growing recognition that effective financial guidance must extend beyond purely quantitative metrics to embrace the psychological and behavioral aspects of money management. This holistic approach acknowledges that financial well-being is deeply intertwined with mental health and overall life satisfaction. Financial advisors are increasingly incorporating elements of behavioral finance, psychological coaching, and values-based planning into their practices, moving towards a more client-centric model that addresses not just wealth accumulation, but also stress reduction and life fulfillment.
Orman’s enduring popularity, particularly her ability to simplify complex financial concepts and connect them to real-life emotions, indicates that her message resonates deeply with a public grappling with economic uncertainty and information overload. Her consistent emphasis on personal responsibility, coupled with this refined focus on peace of mind, offers practical, actionable strategies that empower individuals to take control of their financial destinies.
It is crucial, as Orman herself would likely reiterate, that the information provided serves as educational guidance and not as personalized investment advice. The complexities of individual financial situations necessitate seeking counsel from qualified financial professionals who can offer tailored recommendations based on specific goals, risk tolerance, and circumstances. However, the overarching message from Suze Orman remains clear and universally applicable: true financial freedom is not merely about accumulating wealth, but about cultivating a profound and unshakable sense of security that allows one to live life with purpose and without constant financial apprehension. Her insights continue to offer timely and relevant wisdom for navigating the ever-changing landscape of personal finance, emphasizing that the greatest return on investment may very well be a tranquil mind.








