Candice Horbacz
The seemingly straightforward question of "how many gallons are in a barrel?" unravels into a complex and costly puzzle for businesses operating across the United States. While federal regulations provide clear definitions for standard units, a surprising number of states have adopted divergent measurements for barrels, particularly concerning taxation on commodities like oil and beer. This unharmonious landscape of units introduces significant complexity, elevates compliance costs for interstate businesses, and raises fundamental questions about state authority versus federal constitutional mandates. The result is an administrative labyrinth that burdens businesses, complicates data collection for federal agencies, and ultimately impedes the smooth flow of commerce.
The Genesis of Standardized Barrels: A Historical Imperative for Commerce
The concept of a standardized barrel is rooted in centuries of commercial necessity. In the early days of trade, inconsistent container sizes created chaos, making fair pricing, accurate accounting, and efficient transport nearly impossible. The drive for standardization emerged from practical demands, ensuring that when one bought or sold a "barrel" of a commodity, everyone understood precisely how much was being exchanged. This historical context underscores the fundamental importance of uniform weights and measures in facilitating a robust and equitable marketplace.
For the nascent American oil industry in the mid-19th century, the problem of inconsistent container sizes was particularly acute. Oil, a volatile and valuable commodity, was being extracted in burgeoning quantities, especially in Pennsylvania. Producers and refiners struggled with varying barrel sizes, which complicated transactions, led to disputes, and hindered the growth of a national market. Recognizing this critical impediment, petroleum producers in Pennsylvania convened in 1866 and reached a landmark agreement: a standard oil barrel would contain 42 U.S. gallons. This specific volume was chosen for its practicality, being large enough for efficient transport yet manageable enough for a single person to handle. The Petroleum Producers’ Association officially adopted this standard in 1872, solidifying its place in industry practice. Today, the 42-gallon oil barrel remains the globally recognized standard, codified in the Code of Federal Regulations, which explicitly defines a barrel of oil as 42 gallons.
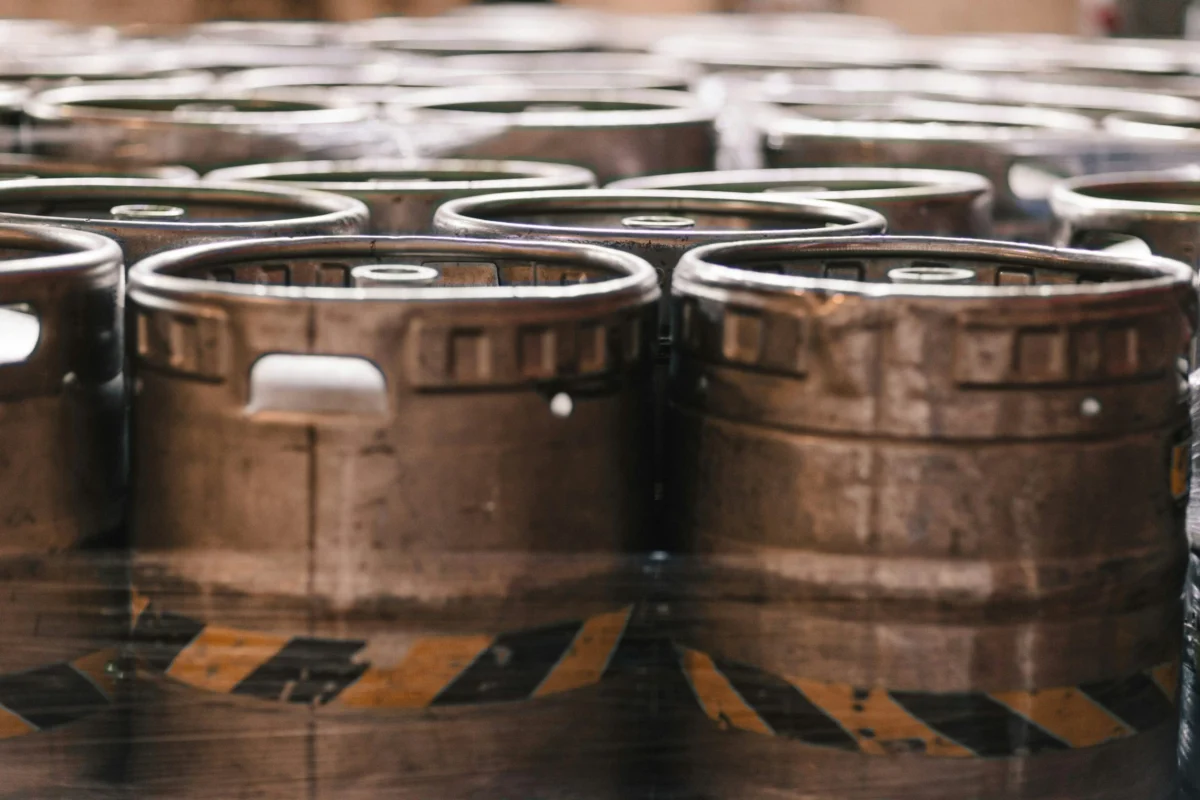
Similarly, the alcohol industry faced its own challenges regarding measurement standardization, particularly concerning taxation. While duties on alcohol in the U.S. predate the Civil War, the first federal tax stamps for beer were issued in 1866. These early stamps were initially designed for various barrel sizes, reflecting the lack of a uniform standard. However, as the industry matured and federal taxation became more sophisticated, the need for a consistent unit of measure became paramount. Standardization efforts eventually led to the adoption of the 31-gallon beer barrel as the national standard. This volume, also defined in the Code of Federal Regulations, ensures consistency in both trade and the collection of excise taxes, simplifying operations for brewers, distributors, and government agencies alike. These federal standards for both oil and beer barrels were established with the clear intent of fostering efficient commerce and equitable taxation across state lines.
A Patchwork of Nonconformity: State-Level Deviations from Federal Standards
Despite the clear federal mandates and the historical rationale for standardization, a significant challenge persists: several states have chosen to define "barrels" differently within their own statutes, primarily for the purpose of levying taxes or inspection fees. This creates a fragmented regulatory environment that directly contradicts the spirit and letter of national standards, impacting businesses engaged in interstate commerce.
Three states, Indiana, Kansas, and Missouri, diverge from the federal 42-gallon standard for oil barrels in specific contexts. While Indiana, for instance, adheres to the 42-gallon definition for its petroleum severance tax, it inexplicably defines a barrel as 50 gallons for the state’s petroleum products inspection fee. This means that a company transporting oil through Indiana must account for two different barrel definitions depending on the specific tax or fee being assessed. Similarly, Kansas and Missouri also levy their gasoline inspection fees on a per-barrel basis, defining their "Kansas barrel" or "Missouri barrel" as 50 gallons, rather than the standard 42 gallons. This 20% difference in volume directly impacts the calculation of inspection fees, making cross-state comparisons and compliance significantly more intricate.
The situation is equally complex, if not more so, for beer barrels, with Arkansas, Connecticut, and Virginia exhibiting their own unique interpretations. Arkansas, for example, levies taxes per barrel of 32 gallons of beer, a slight but critical deviation from the federal 31-gallon standard. To further complicate matters, other sections of Arkansas state statutes correctly define a barrel of beer as 31 gallons, creating internal inconsistencies that can lead to confusion and potential compliance errors. The state’s precise tax rates, such as the $7.507808 per barrel tax for non-licensed products at beer festivals, highlight the granular, yet problematic, nature of these discrepancies.
Connecticut’s approach defines a beer barrel as having "at least 28 but not more than 31 gallons." While this range might seem accommodating, it implies that manufacturers using smaller-than-standard containers (e.g., 28 or 29 gallons) would effectively bear a higher tax burden per gallon compared to those using the full 31-gallon standard. While businesses using the standard 31-gallon barrels might not need to make physical accommodations, the lack of a single, precise definition still introduces ambiguity and potential for varying effective tax rates.
Virginia presents perhaps the most convoluted scenario. Its code broadly defines any container with a volume greater than 43 ounces (approximately 0.336 gallons) as a "barrel," while smaller containers are deemed "bottles." Given this extremely broad definition, the state’s taxes are not strictly levied "per barrel" in the conventional sense but rather "per gallon per barrel," or "per ounce per bottle" depending on the container size. While this effectively translates to a per-gallon tax levy for many products, rendering the "barrel" definition less relevant for direct taxation, it becomes critically important for other regulatory aspects, such as brewery license fees, which are often determined by the number of barrels a brewery produces annually. This distinction forces businesses to navigate a dual system where the definition of "barrel" shifts its relevance based on the specific regulatory context.
Economic Fallout and Administrative Burden: Navigating the Labyrinth
The implications of these non-standard barrel definitions extend far beyond mere mathematical inconvenience. They impose substantial economic and administrative burdens on businesses, particularly those operating across state lines, and even on government entities tasked with data collection and analysis.
For interstate businesses, the varying definitions translate directly into increased compliance costs. Companies must invest in specialized accounting software, legal counsel, and administrative personnel to meticulously track and differentiate between "standard" barrels and "state-specific" barrels. This often means running parallel accounting systems, adjusting inventory management practices, and training staff to understand and apply the correct definitions for each jurisdiction. The cumulative cost of this administrative overhead can be significant, diverting resources that could otherwise be invested in growth, innovation, or job creation. Industry observers contend that these hidden costs disproportionately affect smaller businesses with fewer resources to dedicate to complex compliance regimes.
Moreover, these discrepancies introduce unnecessary friction into interstate commerce. A national distributor of gasoline, for example, must account for 42-gallon barrels in most states, but suddenly switch to 50-gallon barrels for inspection fees in Kansas or Missouri. This logistical and accounting complexity slows down operations, increases the risk of errors, and can even deter businesses from expanding into states with non-standard measurements, thereby stifling economic activity and market efficiency.
The administrative burden is not confined to the private sector. Federal agencies, whose mandate includes collecting and analyzing national economic data, also struggle with these state-level inconsistencies. The Energy Information Administration (EIA), a critical source of energy-related information for policymakers and the public, has publicly acknowledged the challenges posed by non-standard barrel definitions. Last year, the EIA was compelled to revise previously published fuel tax figures due to Kansas’s petroleum inspection fee being levied per a 50-gallon "Kansas barrel" instead of the standard 42-gallon unit. This incident highlights how state nonconformity can distort national data, making it harder to track and compare tax burdens accurately, assess energy policy impacts, and provide reliable information for economic forecasting. If a federal agency with dedicated resources struggles to reconcile these differences, the predicament of a private business with limited compliance staff is exponentially greater.
Legal Scrutiny: The Constitutional Question of Weights and Measures
Beyond the economic and administrative inefficiencies, the practice of states defining their own barrel measurements raises a significant constitutional question regarding the division of powers between state and federal governments. The United States Constitution explicitly grants Congress the power "To coin Money, regulate the Value thereof, and of foreign Coin, and fix the Standard of Weights and Measures" (Article I, Section 8, Clause 5). This clause clearly delegates the authority to establish uniform standards of measurement to the federal government, precisely to avoid the kind of chaotic, fragmented system that existed under the Articles of Confederation and that now reappears in the context of barrel definitions.
The federal government has exercised this power by codifying the 42-gallon oil barrel and the 31-gallon beer barrel in the Code of Federal Regulations. By legislating different volumes for these units, states appear to be encroaching upon an area of authority explicitly reserved for the federal government. Legal scholars and constitutional experts argue that there is no constitutional basis for states to unilaterally redefine standard units of measure once Congress has acted. The intent of the framers was to ensure national uniformity in commerce, preventing individual states from creating barriers to trade through idiosyncratic standards.
This situation bears a striking, albeit less dramatic, resemblance to Indiana’s infamous legislative attempt in 1897 to statutorily define the mathematical constant pi as 3.2. While that particular bill ultimately failed to pass into law, it serves as a historical precedent for legislative overreach into areas of established, universal standards. Just as states lack the authority to redefine fundamental mathematical constants, they arguably lack the authority to redefine universally accepted units of physical measurement that directly impact interstate commerce.
Call for Harmonization: Towards a Unified Standard
The solution to this needless complexity is straightforward: states should conform to the federally established standards for barrels of oil and beer. Harmonizing these definitions would yield substantial benefits across the board. Businesses would experience a significant reduction in compliance costs, allowing them to allocate resources more efficiently and foster smoother, more predictable interstate trade. Data collection for federal agencies like the EIA would become more accurate and less burdensome, leading to better-informed policy decisions.
Furthermore, aligning state statutes with federal standards would uphold the constitutional principle of a unified system of weights and measures, reinforcing the federal government’s delegated authority and promoting national economic coherence. There is no compelling reason for the answer to "how many gallons are in a barrel?" to depend on which side of a state line one stands. Embracing uniformity would eliminate an unnecessary source of friction, making the American marketplace more efficient, transparent, and equitable for all participants. The time is opportune for states to shed these anachronistic deviations and embrace a truly national standard.