Candice Horbacz
A forthcoming Tax Law Review article, "Taxation and Deglobalization," by prominent legal scholar Reuven Avi-Yonah, has ignited a fervent debate within economic and legal circles by proposing a radical shift in corporate tax policy. Avi-Yonah posits that with strategic fixes to the tax base, including the implementation of full expensing for investments, traditional concerns regarding the economic repercussions of a high corporate income tax rate would largely dissipate. This, he argues, could pave the way for a staggering 80 percent top corporate tax rate, particularly for companies reporting profits exceeding $10 billion. While other influential analysts and scholars, such as Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby, have previously advocated for a "fix the base, raise the rate" approach, their discussions have generally contemplated top rates significantly below Avi-Yonah’s audacious 80 percent figure. This bold proposal challenges long-held assumptions about corporate taxation in a globalized, or increasingly deglobalized, economy.
The "Fix the Base, Raise the Rate" Doctrine: A Brief History
The concept of reforming the corporate tax base to allow for higher rates is not new. For decades, policymakers and economists have grappled with the complexities of taxing multinational corporations, particularly in an era of heightened global economic integration. The fundamental challenge lies in balancing the need for government revenue with the desire to foster economic growth and competitiveness. Corporate income taxes, while a significant source of funding for public services, have often been criticized for their potential to distort investment decisions, discourage innovation, and incentivize profit shifting.
The "fix the base, raise the rate" school of thought gained significant traction as concerns about tax avoidance and the erosion of national tax bases intensified. Economists observed that many multinational corporations were adept at exploiting loopholes and inconsistencies in international tax laws, moving profits from high-tax jurisdictions to low-tax havens. This profit shifting meant that even modest corporate tax rates required higher statutory rates to collect the same amount of revenue, creating a vicious cycle where higher rates amplified the incentives for avoidance, leading to further distortions.
Key reforms proposed under this doctrine include broadening the tax base by eliminating various deductions and credits, and crucially, introducing mechanisms like full expensing of investment. Full expensing allows businesses to immediately deduct the full cost of certain investments in new technology, equipment, or buildings. This reform is championed for alleviating a bias in the tax code that otherwise discourages investment, thereby incentivizing companies to expand, which in turn can boost worker productivity, wages, and job creation in the long run. By ensuring that the cost of capital is not taxed, full expensing theoretically neutralizes the corporate tax’s distortive effect on marginal investments.
Another critical area of reform targets profit shifting directly. Multinational companies often engage in intricate accounting practices, such as manipulating transfer prices for intra-company transactions or strategically locating intellectual property in low-tax jurisdictions, to reduce their overall tax burden. This non-neutrality distorts investment decisions, favoring businesses more capable of engaging in such practices. Furthermore, the resources firms expend on administration and compliance for profit shifting are economically unproductive, representing a deadweight loss to the economy. Therefore, moving the tax base toward something less susceptible to profit shifting is considered a sound policy goal.
Destination-Based Cash Flow Taxation (DBCFT) and Avi-Yonah’s Proposals
One of the most comprehensive proposals to limit profit shifting and reform the corporate tax base is the destination-based cash flow tax (DBCFT). A DBCFT typically entails several key components: denying tax deductions for imports (including service imports), imposing a zero tax rate on export income (together known as "border adjustment"), full expensing of investment, and denying interest expense deductions.
The advantages of a DBCFT are significant. Border adjustment mechanisms effectively close off major profit-shifting avenues by taxing consumption where it occurs, rather than income where it is theoretically generated. This system aims to prevent companies from exploiting differences in national tax rates by shifting paper profits across borders. Concurrently, full expensing paired with no interest deduction, often referred to as "cash flow taxation," broadly reduces the distortive effects of taxation on investment decisions, making the tax code more neutral with respect to capital allocation.
Avi-Yonah’s specific proposals, while broadly aligning with the spirit of moving towards a less profit-shifting-prone tax base, differ in certain respects from a pure DBCFT. He suggests a 10 percent tariff instead of denying the deductibility of imports and includes a digital services tax. These can be interpreted as alternative mechanisms designed to achieve similar goals of broadening the tax base and preventing erosion, particularly in a world increasingly dominated by digital economies.
The Rationale for an 80 Percent Rate: Taxing "Excessive Rents"
Avi-Yonah’s provocative leap to an 80 percent top corporate tax rate stems from a particular interpretation of economic rents and the evolving global economic landscape. He argues that the corporate tax, after base reforms ensure that normal corporate projects are effectively untaxed, should be adjusted to collect some of the "excessive rents"—or supernormal returns—of firms, particularly those with significant monopoly or pricing power.
In his view, companies with profits higher than $10 billion are highly likely to exhibit monopolistic or cartel-like behavior, generating returns far exceeding the cost of capital. A progressive rate structure, with an 80 percent top marginal rate for these large entities, would target these rents without impacting the incentives for normal, productive investments that generate average returns. Smaller companies, with lower profit levels, would be subject to gradually decreasing marginal rates.
Crucially, Avi-Yonah links the feasibility of such a high rate to the concept of a "deglobalizing economy." In a fully globalized world, where capital and profits can move relatively freely, an 80 percent corporate tax rate would be almost unthinkable, likely triggering massive capital flight and corporate headquarters relocation. However, in a deglobalizing economy—characterized by increased protectionism, reshoring of supply chains, and potentially reduced cross-border financial flows—Avi-Yonah argues that applying such a tax on a worldwide basis becomes more feasible. The implicit assumption is that the costs of moving operations or profits would outweigh the benefits of avoiding the high U.S. tax rate, especially if access to the lucrative U.S. market were contingent on compliance.
This perspective aligns with a broader sentiment in some policy circles that large corporations, particularly in the tech and pharmaceutical sectors, have accumulated vast profits and market power, leading to concerns about wealth inequality and insufficient public revenue. Taxing "excessive rents" is seen by some as a way to reclaim a share of these profits for public good without unduly penalizing productive investment.
The Critical Counter-Argument: Why Rates Still Matter
While the admiration for full expensing as a pro-growth reform is well-founded, and its ability to reduce the sensitivity of investment decisions to the tax rate is undeniable, critics argue that believing rates would not matter if the business tax base is perfectly designed is a dangerous oversimplification. The core of the critique against Avi-Yonah’s 80 percent proposal lies in the inherent limitations of any real-world tax system and the nuances of investment behavior that the standard economic models often fail to capture fully.
The standard economic (Hall-Jorgenson) framework for the user cost of capital, often cited to explain the neutrality of full expensing, suggests that under expensing, the tax rate theoretically cancels out of the investment decision formula. The formula c = (r + δ) / (1 – τz), where ‘c’ is the required pre-tax return, ‘r’ is the required after-tax return, ‘δ’ is economic depreciation, ‘τ’ is the tax rate, and ‘z’ is the present value of cost-recovery deductions per dollar invested, simplifies to c = r + δ when full expensing (z=1) is in place. This simplification implies that the tax rate (τ) no longer influences the investment hurdle rate, making investment decisions tax-neutral.
However, critics, including those analyzing the implications of Avi-Yonah’s proposal, contend that this framework does not encompass the full complexity of real-world investment choices, especially when considering extremely high tax rates. While a good approximation for low or moderate rate changes, the departures from this idealized model become too significant to ignore when contemplating an 80 percent corporate tax.
Limitations of the Standard Framework: Innovation and Asymmetries
One crucial example of these limitations lies in innovation driven by new firm entry, often funded by founders who work for less than their market wage—their "implicit wages"—while building the business. The inability of entrepreneurs to deduct these unpaid efforts for business tax purposes represents a significant departure from the standard user cost model. No tax system can fully allow and accurately price a business deduction for this opportunity cost. Consequently, the tax rate will not fully cancel out, even under full expensing.
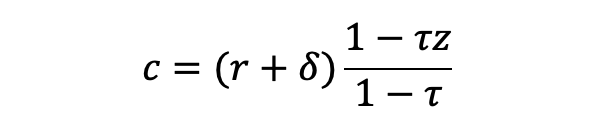
Consider an investment requiring explicit capital spending (fully expensed) plus a complementary input of the founder’s effort, with an opportunity cost (ψ) per dollar of capital that receives no business cost recovery. This opportunity cost could be the market income an entrepreneur would forgo by working at an established firm, net of labor taxes. An extended user cost formula demonstrates that a higher business tax rate significantly increases the required pre-tax return on such projects. For instance, if the founder’s unexpensed effort equals half of the capital investment, raising the business rate from 21 percent to 80 percent could increase the required pre-tax return by approximately 114 percent. This effect is not linear; raising the rate from 70 percent to 80 percent would increase the required return by about 31 percent, a much larger impact than a 10-percentage-point increase at lower rates (e.g., from 21 percent to 31 percent, which might yield only a 6 percent increase). This illustrates that the cost of raising the rate becomes exponentially larger as the rate itself climbs higher.
More broadly, whenever investment cost offsets are not symmetric with the taxation of gains, full expensing is insufficient to ensure the tax rate cancels in the user cost calculation. This asymmetry can manifest in several ways beyond implicit wages. Businesses in a loss position, for example, may have their deductions delayed, or if they never turn a profit, the deduction may never be realized. Data from venture-backed startups indicates that a significant percentage (e.g., 55 percent of those funded between 1985 and 2009) are terminated at a loss, highlighting the real-world impact of unrealized deductions.
Furthermore, Avi-Yonah’s proposal for a progressive corporate tax rate, rather than a flat one, introduces additional asymmetries. A progressive structure can create intertemporal asymmetry over a firm’s life cycle. Relieving early-stage costs at a lower 21 percent rate while taxing later, successful profits at 80 percent would inevitably raise the user cost of capital. The precise magnitude would depend on factors like timing, discounting, and the firm’s ability to defer tax deductions through various elections, which themselves reintroduce the tax rate into the user cost calculation.
Broader Economic Implications of an 80 Percent Corporate Tax Rate
Beyond the technicalities of the user cost of capital, an 80 percent corporate tax rate, even with base reforms, would have profound and potentially detrimental implications for the broader economy.
- Innovation and Entrepreneurship: Startups and innovative firms, often operating at a loss in their early stages, rely heavily on future profitability to attract capital and talent. An 80 percent tax on high profits could severely dampen the incentive for entrepreneurs to take risks, knowing that a vast majority of their eventual success would be appropriated by the government. This could stifle the very engine of economic dynamism and technological advancement.
- Capital Flight and Competitiveness: While Avi-Yonah argues that a deglobalizing economy makes capital flight harder, an 80 percent rate would still make the U.S. an extreme outlier globally. Most developed nations have corporate tax rates ranging from 15 percent to 30 percent. Even if physical assets are harder to move, financial capital remains highly mobile. Foreign direct investment into the U.S. could plummet, and U.S. companies might still find ways to structure their operations to minimize exposure to such a high domestic rate, even if it means sacrificing some access to the U.S. market or incurring higher operational costs elsewhere. The global average corporate tax rate has been steadily declining for decades, from over 40% in the 1980s to around 23% today, reflecting intense international tax competition. An 80% rate would fly in the face of this trend.
- Market Concentration and Monopoly Power: While Avi-Yonah’s proposal aims to target "excessive rents" from monopolistic firms, such a high rate could paradoxically entrench existing monopolies. New entrants, often starting small and growing, would face an extremely steep tax wall once they achieved significant profitability. This could make it harder for innovative challengers to scale and compete with established giants, potentially reducing market contestability rather than enhancing it.
- Revenue Volatility: An 80 percent rate applied to a narrow base of highly profitable companies could lead to significant revenue volatility. The profits of large corporations can fluctuate dramatically with economic cycles. Relying heavily on such a concentrated source of revenue could make government budgeting unpredictable and unstable.
- Tax Incidence: The question of who ultimately bears the burden of the corporate tax (tax incidence) is complex. While nominally paid by corporations, the economic burden can be shifted to consumers (through higher prices), workers (through lower wages), or shareholders (through lower returns). An 80 percent rate could impose a substantial burden on these groups, potentially leading to reduced consumption, slower wage growth, and lower savings.
Conclusion: A Complex Balancing Act
Reuven Avi-Yonah’s article on "Taxation and Deglobalization" represents a bold intellectual contribution to the ongoing debate about corporate tax reform. His emphasis on fixing the tax base, particularly through full expensing and measures to curb profit shifting, aligns with many pro-growth tax reform recommendations. Such reforms are indeed crucial for creating a more neutral, efficient, and equitable tax system.
However, the leap to an 80 percent top corporate tax rate, even with these base improvements, appears to stretch the theoretical and practical limits of taxation. While the idealized models suggest that a perfectly designed cash flow tax with full expensing could render the tax rate irrelevant for marginal investments, real-world complexities—such as the non-deductibility of entrepreneurial effort, the challenges faced by loss-making startups, and the intertemporal effects of progressive rate structures—demonstrate that the tax rate continues to exert a significant influence on investment decisions and overall economic activity.
The debate sparked by Avi-Yonah’s proposal underscores the delicate balancing act inherent in tax policy: the need to raise sufficient revenue, to promote economic growth, to ensure fairness, and to maintain international competitiveness. While base reforms can undoubtedly lower the economic cost of existing tax rates and even modest rate increases, the evidence suggests that an 80 percent corporate income tax rate, even in a deglobalizing world, would likely impose substantial economic consequences, potentially stifling innovation and deterring investment rather than merely collecting "excessive rents." The intellectual undercurrent that believes a perfectly designed business tax base can render rates irrelevant carries a real danger of overlooking these critical trade-offs.