Julia Chirkova
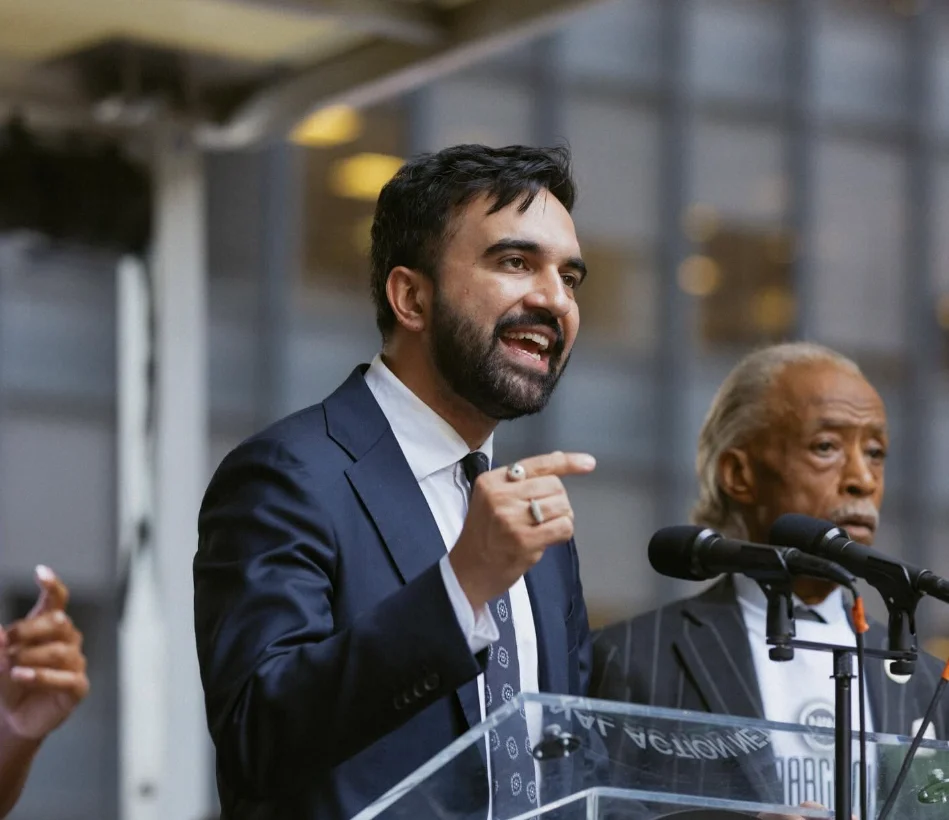
A significant setback has befallen New York City Mayor Zohran Mamdani’s ambitious "pied-à-terre" tax initiative, as a Staten Island judge has ruled against the city’s rollout of the controversial surcharge on high-value second homes. Justice Wayne Ozzi, in a 22-page decision issued Tuesday, found the city’s initial notification process unlawful, ordering the cancellation and re-issuance of tax notices and mandating the removal of the supplemental property tax roll from public view. This ruling strikes a blow to a key revenue-generating program designed to address a substantial budget gap.
Legal Challenge and Judicial Scrutiny
The legal challenge, brought forth by owners of high-value second homes, centered not on the legality of the tax itself, but on the methodology employed by the city in its implementation. Plaintiffs argued that the city failed to adhere to state law by placing the burden of proof on homeowners to demonstrate they reside in their own properties before potentially being subjected to the tax.
Justice Ozzi echoed these concerns, stating in his decision, "No crime is involved here, but homeowners are being substantially harmed and penalized needlessly." The judge’s ruling directly addresses the notices mailed by the city, deeming them unlawful. Furthermore, he ordered the immediate removal of the supplemental property tax roll, which had been posted online and identified approximately 900,000 properties as potentially subject to the surcharge.
Randy Mastro, representing the homeowners in the lawsuit, characterized the city’s approach as a "botched rollout" that wasted taxpayer time and resources. "The fact is that this administration failed to follow state law when it burdened New York City homeowners with proving they live in their own homes or be on the hook for paying a new surcharge," Mastro stated. He emphasized that the administration must now "go back and do what it should have done from the start: use all the information at its disposal to make an individualized ‘initial determination’ about who truly owes this surcharge before demanding that they pay it."
Background of the Pied-à-Terre Tax
The pied-à-terre tax, signed into law by Governor Kathy Hochul in May, is a cornerstone of Mayor Mamdani’s fiscal strategy. It targets wealthy individuals who own luxury second homes in New York City but maintain their primary residences elsewhere. The revenue generated, estimated to be $500 million annually, is earmarked to help close a significant budget deficit and fund the administration’s affordability agenda.
The tax applies to residential properties valued over $5 million if owned by non-New York City residents. For co-ops and condos, the threshold is a market value exceeding $1 million. Exemptions are available for properties where the owner permanently resides in the city or has an immediate family member living there.
A Flawed Implementation Process
The city’s implementation of the tax has been marked by a series of missteps, as detailed in court filings and the judge’s decision. Initially, in July, the city dispatched letters to approximately 17,000 luxury property owners, informing them they might be subject to the surcharge and providing information on how to file for an exemption. These initial notices were reportedly based, in part, on information gleaned from homeowners’ 2024 personal tax returns.
However, the process soon encountered complications. The city subsequently obtained more recent tax forms from the state, six months ahead of schedule. This led to a situation where hundreds of individuals who had initially received notices were later contacted by the city and informed that they were, in fact, not subject to the pied-à-terre tax. This iterative and seemingly disorganized approach fueled homeowner frustration and contributed to the legal challenge.
Among the plaintiffs in the lawsuit were Rachel O’Brien and Carmine Morano, the wife and father of Republican Staten Island Councilmember Frank Morano. While the Moranos and their co-plaintiff, Simon Hedley, ultimately learned they were not subject to the tax, their experience, as described by Mastro, involved significant distress. Mastro, a prominent legal figure known for representing affluent New Yorkers and a vocal critic of Mayor Mamdani’s policies, claimed that the notification process caused "hell" for these homeowners, forcing them to engage lawyers and accountants and leading to the sharing of their sensitive tax data with the city.
Judicial Analysis of Harm and Due Process
Justice Ozzi’s decision specifically highlighted the "substantial harm" and "needless penalty" inflicted upon homeowners. The judge’s emphasis on the need for an "individualized ‘initial determination’" before imposing such a tax underscores a fundamental principle of due process: that individuals should not be compelled to prove their innocence or eligibility for exemption before being subjected to financial penalties.
The homeowners’ legal team argued that the mere act of being notified of potential liability, requiring consultation with legal and financial professionals, and having personal tax information disclosed constituted significant harm, even if they were ultimately deemed not liable. This argument resonated with Justice Ozzi, who found that the city’s procedural missteps had indeed caused undue hardship.
City’s Defense and Counterarguments
During oral arguments before Justice Ozzi last month, the city’s Law Department, represented by Chief Steve Banks, contended that the lawsuit should be dismissed. Banks argued that the plaintiffs had not suffered actual harm and therefore had no "live claim" for relief. He characterized the case as a "policy dispute dressed up as a case in controversy," suggesting that the homeowners were attempting to litigate a policy they disliked rather than addressing a concrete legal injury.
Banks further argued that the city’s implementation process was "iterative" and that no laws had been violated. He asserted that the homeowners had manufactured claims after receiving a "non-final agency determination" that ultimately did not impact them. The city’s defense hinged on the notion that the notification process was a preliminary step and that the ultimate liability had not yet been definitively established for any of the plaintiffs.
Implications and Future Outlook
The judge’s ruling presents a significant hurdle for Mayor Mamdani’s administration, forcing a pause and a complete recalibration of the pied-à-terre tax rollout. The city must now re-evaluate its notification strategy and ensure strict adherence to state laws governing tax assessments and homeowner rights. This could involve developing a more robust system for initial determinations, leveraging existing data more effectively, and providing clearer, more accurate information to property owners.
The delay in implementation will likely impact the projected revenue stream of $500 million, potentially exacerbating the city’s budget challenges. The administration faces the dual task of complying with the court’s order while simultaneously seeking to advance its fiscal and affordability goals.
The pied-à-terre tax, as articulated by Mayor Mamdani, is intended to address what he described as a "fundamentally unfair system that hurts working New Yorkers." He has pointed to examples such as the $238 million penthouse on Billionaires’ Row owned by Chicago-based hedge funder Ken Griffin, which he characterized as a unit designed for "those who store their wealth in New York City real estate, but who don’t actually live here." Mamdani’s vision is that "everyone has a role to play in contributing to our city. And some, a little bit more than others."
The judicial rebuke, however, underscores the critical importance of procedural correctness in tax policy implementation, especially when it involves substantial financial implications for property owners. The city’s next steps will be closely watched, as they will determine the future of this key revenue source and its intended impact on the city’s fiscal health and housing affordability initiatives.
More than 2,000 individuals have reportedly challenged their status under the tax, and the city had recently extended the deadline for submitting proof of residency to October 6th. This ruling now necessitates a complete restart of the notification process for these individuals and for any others who may be identified as potentially subject to the tax. The protracted nature of this legal battle and the administrative complexities involved suggest that the full implementation of the pied-à-terre tax may be significantly delayed.