Nila Kartika Wati
The United States Treasury Department and the Internal Revenue Service (IRS) have formally introduced a proposed regulation that would fundamentally alter the landscape of American education by stripping nonprofit colleges, universities, and private K-12 schools of their tax-exempt status if they maintain programs using race as a criterion for eligibility. Announced on September 3, 2026, the rule represents the most aggressive move to date by the Trump administration to dismantle diversity, equity, and inclusion (DEI) frameworks within the private sector. Under the proposal, any institution of learning that administers or supports programs—ranging from scholarships and admissions to specialized academic support—that "discriminates on the basis of race, color, or national or ethnic origin" would forfeit its 501(c)(3) status. While the administration frames the move as a necessary step to ensure "colorblind" meritocracy, legal experts and educational leaders warn of a protracted judicial battle that could destabilize the financial foundations of thousands of institutions.
The Scope of the Proposed Regulation
The proposed rule is expansive, covering approximately 18,000 private schools that serve an estimated 750,000 students across the United States. This includes not only elite Ivy League universities and small liberal arts colleges but also private elementary and secondary schools, trade schools, and professional graduate programs. According to the Treasury Department’s initial impact statement, the regulation would apply to any school-administered initiative, including athletic recruitment, specialized fellowships, and even foundations that provide targeted scholarships to students at public universities.
Treasury Secretary Scott Bessent has articulated the administration’s stance, suggesting that any program designed with specific diversity goals constitutes a form of prohibited discrimination. By targeting the tax-exempt status of these institutions, the federal government is leveraging its most powerful financial tool. For a nonprofit school, the 501(c)(3) designation is a lifeline; it exempts the institution from federal income tax and, crucially, allows donors to deduct their contributions from their own taxes. The loss of this status would likely trigger a domino effect, leading to the loss of state and local property tax exemptions, which are often contingent upon federal standing.
Financial Stakes and Economic Impact
The economic ramifications of the proposed rule are significant. In 2025, Americans contributed approximately $92 billion in charitable donations to private educational institutions. These donations are not merely "extra" funds; they are integral to the operational viability of higher education. On average, philanthropic giving covers roughly 10% of the annual operating budgets for private colleges and universities. For many smaller, tuition-dependent colleges already reeling from demographic shifts and rising costs, the loss of tax-deductible donations could lead to immediate insolvency.
Furthermore, the IRS estimates that the loss of tax exemption would necessitate a radical restructuring of school finances. Without the ability to attract high-net-worth donors through tax incentives, schools would be forced to find alternative revenue streams, most likely through steep increases in tuition. This, in turn, would affect student accessibility, potentially pricing out the very middle-class families the administration claims to support. The government itself has acknowledged in the Federal Register that the rule could lead to significant legal costs for schools and complicated renegotiations with existing donors whose endowment gifts were predicated on the school’s nonprofit status.
A Chronology of the Anti-DEI Push
The September 2026 proposal is the culmination of a multi-year effort to redefine civil rights law through executive and judicial action. The timeline below highlights the key events leading to this policy shift:
- June 2023: The U.S. Supreme Court rules in Students for Fair Admissions v. Harvard, declaring that race-conscious admissions policies in higher education violate the Equal Protection Clause of the 14th Amendment.
- January 2025: Following his inauguration, President Trump issues an executive order titled "Ending Illegal Discrimination and Restoring Merit-Based Opportunity," directing federal agencies to review all programs that utilize racial preferences.
- January 2026: The Department of Labor begins auditing federal contractors, including many universities, for DEI policies that the administration deems discriminatory against non-minority groups.
- June 30, 2026: Two federal courts block the Department of Education’s attempts to modify student loan forgiveness rules for nonprofit employees, signaling a judicial appetite for checking executive overreach in the educational sector.
- September 3, 2026: The Treasury and IRS officially propose the rule to revoke tax-exempt status for schools with race-based programs.
- November 3, 2026: The mandatory public comment period is set to conclude, after which the IRS must review and respond to feedback.
- May 31, 2027: The earliest possible date for the rule to take effect, pending legal injunctions.
Legal Precedents and the "Public Policy" Doctrine
The administration bases its legal authority on a specific interpretation of the 1983 Supreme Court case Bob Jones University v. United States. In that landmark decision, the Court ruled that the IRS had the power to revoke the tax-exempt status of a university that prohibited interracial dating, citing that the school’s policies violated a "fundamental public policy" against racial discrimination.
However, legal scholars point out a critical distinction. In Bob Jones, the government was acting against an institution that was practicing exclusion and segregation. The current administration is attempting to use the same logic against institutions practicing inclusion and remediation. Critics argue that the administration is stretching the "public policy" doctrine beyond its intended scope. While the Harvard decision of 2023 limited race-conscious admissions, it did not explicitly state that all race-based efforts (such as targeted recruitment or support services) were illegal, nor did it suggest that tax status should be used as a punitive measure.
Furthermore, legal experts like Philip Hackney and Brian Galle have argued that the proposed rule may violate the "Major Questions Doctrine," a judicial principle that suggests agencies cannot make decisions of vast economic and political significance without clear authorization from Congress. Since the tax code (Section 501(c)(3)) does not explicitly define "discrimination" in a way that includes diversity initiatives, the administration may be overstepping its regulatory bounds.
Responses from Educational and Advocacy Groups
The reaction from the educational sector has been swift and overwhelmingly critical. Organizations such as EdTrust and the American Association of University Professors (AAUP) have issued statements condemning the rule as an assault on institutional autonomy. The AAUP argued that the proposal creates a "chilling effect" on academic freedom, as schools may preemptively shutter programs that are essential to their mission out of fear of financial ruin.
"This is not about ending discrimination; it is about using the tax code as a weapon to enforce a specific ideological agenda," said a spokesperson for a coalition of private liberal arts colleges. "By threatening the very existence of these institutions, the government is undermining the diversity of thought and background that makes American higher education a global leader."
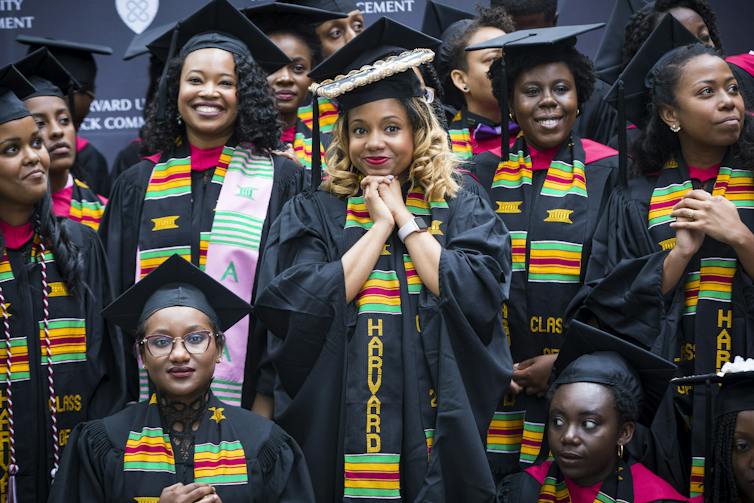
Conversely, supporters of the rule argue that it is a long-overdue correction. They contend that any use of race in decision-making is inherently discriminatory and that the federal government should not subsidize institutions that categorize students by skin color. Secretary Bessent has maintained that the rule simply aligns the tax code with the constitutional principles articulated in the Harvard decision.
Broader Implications and Potential Chilling Effects
Beyond the immediate financial and legal concerns, the proposed rule carries broader implications for the nonprofit sector at large. If the IRS is permitted to revoke tax-exempt status based on an administration’s shifting definition of "public policy," other nonprofits could be at risk. Civil rights groups worry that this logic could eventually be applied to healthcare organizations, housing nonprofits, or foundations that focus on specific marginalized communities.
There is also the concern of "institutional autonomy." The First Amendment protects the rights of private organizations to associate and express their values. By conditioning a tax benefit on the abandonment of specific educational philosophies—such as the belief that a diverse student body is essential to learning—the government may be infringing upon the speech and associational rights of these schools.
As the November 3 deadline for public comments approaches, the IRS is expected to receive a record-breaking number of submissions. These comments will form the basis for the inevitable lawsuits that will follow the rule’s finalization. Given the complexity of the issues and the high stakes involved, legal analysts predict that the rule will be tied up in the court system for years, likely reaching the Supreme Court. In the interim, private schools face an agonizing choice: maintain their commitment to diversity programs and risk their financial future, or dismantle those programs to ensure their survival, potentially altering their institutional identity forever.
Conclusion and Future Outlook
The Trump administration’s proposal represents a watershed moment in the relationship between the federal government and private education. By targeting the 501(c)(3) status, the administration has moved the "culture war" into the realm of high-stakes fiscal policy. While the final version of the rule may undergo changes based on public feedback, the underlying intent remains clear: to force a "colorblind" standard on private institutions through economic pressure. Whether the judiciary will allow such an expansive use of executive power remains the central question that will define the next chapter of American educational law. For now, the 18,000 schools in the crosshairs must prepare for a period of profound uncertainty and intense legal scrutiny.