Candice Horbacz
Washington State’s recently enacted income tax on high earners, slated to take effect in 2028, is already a focal point of intense legal and political activity, signaling a contentious future for the state’s evolving fiscal landscape. Despite its delayed implementation, the measure faces a multi-pronged assault, including a pending constitutional challenge, legislative efforts to broaden its scope, and a citizen-led initiative on the November ballot aimed at its outright repeal. This flurry of action underscores the deep divisions and complex procedural maneuvers that have characterized the tax’s journey to date.
The tax, which imposes a 9.9 percent levy on individual or couple incomes exceeding $1 million, represents a significant departure for a state historically known for its lack of a broad-based individual income tax. Its passage has ignited a fierce debate about fairness, economic impact, and the very interpretation of Washington’s state constitution.
A Complex Legislative Genesis and Procedural Gambit
The path to the high-earner income tax has been anything but straightforward, marked by strategic legislative maneuvers designed to circumvent traditional voter review processes and accelerate its consideration. The current tax was adopted following a series of events that began in 2024.
In a move that surprised many observers, the Washington State Legislature overwhelmingly approved a filed ballot measure, Initiative 2111, in early 2024. This initiative, if it had gone to voters and passed, would have explicitly stipulated that "Neither the state nor any county, city, or other local jurisdiction in the state of Washington may tax any individual person on any form of personal income." Typically, such ballot measures are put before the electorate. However, by adopting it themselves, lawmakers initiated a critical legislative clock. Amending language adopted by a ballot measure requires a two-thirds legislative supermajority for the first two years after its approval. Had voters approved Initiative 2111 in November 2024, lawmakers would have been barred from considering an income tax until the 2027 legislative session. By adopting it themselves in early 2024, they effectively started this two-year clock sooner, allowing them to revisit the income tax issue during the 2026 session, rather than waiting until 2027. This procedural agility enabled the legislature to adopt the very type of tax that Initiative 2111 ostensibly prohibited, albeit with a delayed implementation.
Further illustrating the legislature’s intent to control the tax’s trajectory, an emergency clause was appended to the high-earner income tax bill. This clause, asserting that the new tax was "necessary for the support of the state government and its existing public institutions," served a crucial purpose: it shielded the measure from a provision in Washington law that ordinarily allows voters to review tax changes through a referendum. Referendums, which allow citizens to approve or reject laws passed by the legislature, are a common mechanism for public oversight of new legislation. By declaring an "emergency," lawmakers effectively blocked this avenue, forcing opponents to seek alternative means to challenge the tax. This controversial use of the emergency clause for a tax not taking effect until 2028, with a filing date in 2029, drew sharp criticism from watchdog groups and tax opponents who argued it undermined democratic processes.
Design of the Tax: Targeting Specific Income Streams and Small Businesses
The new income tax, structured to apply to individuals or couples earning over $1 million annually, is designed to capture income from specific, often high-value, financial activities. While the term "high earner" might conjure images of individuals with exceptionally large salaries, the reality of the tax’s application is more nuanced. Very few people earn salaries exceeding $1 million solely from traditional wages. Instead, incomes at this level typically flow through several key channels:
- Capital Gains and Dividend Income: Profits from the sale of investments or distributions from company earnings can push individuals over the threshold.
- Pass-Through Business Income: A significant portion of the tax burden is expected to fall on small business owners. Pass-through entities, such as sole proprietorships, partnerships, and S corporations, report their income on the individual income tax returns of their owners. This means that business profits, rather than being subject to corporate tax, are taxed at individual rates. For many successful small business owners, their share of the business’s profits can easily exceed the $1 million threshold in a given year.
- Restricted Stock Unit (RSU) Vesting: A common form of compensation in the tech sector, RSUs grant employees company shares that vest (become fully owned) after a certain period or upon specific events, such as an initial public offering (IPO). It is not uncommon for an employee who has worked at a startup for several years to have multiple years’ worth of accumulated stock vest all at once when the company goes public. This single event can generate an income figure well over $1 million for that year, even if their average annual income over the vesting period was significantly lower.
- Sale of Businesses or Major Assets: Individuals selling a long-established business they built over decades, or generating substantial capital gains from the sale of a home or other significant asset, could also find their income for that specific year exceeding the $1 million threshold, thus subjecting them to the tax.
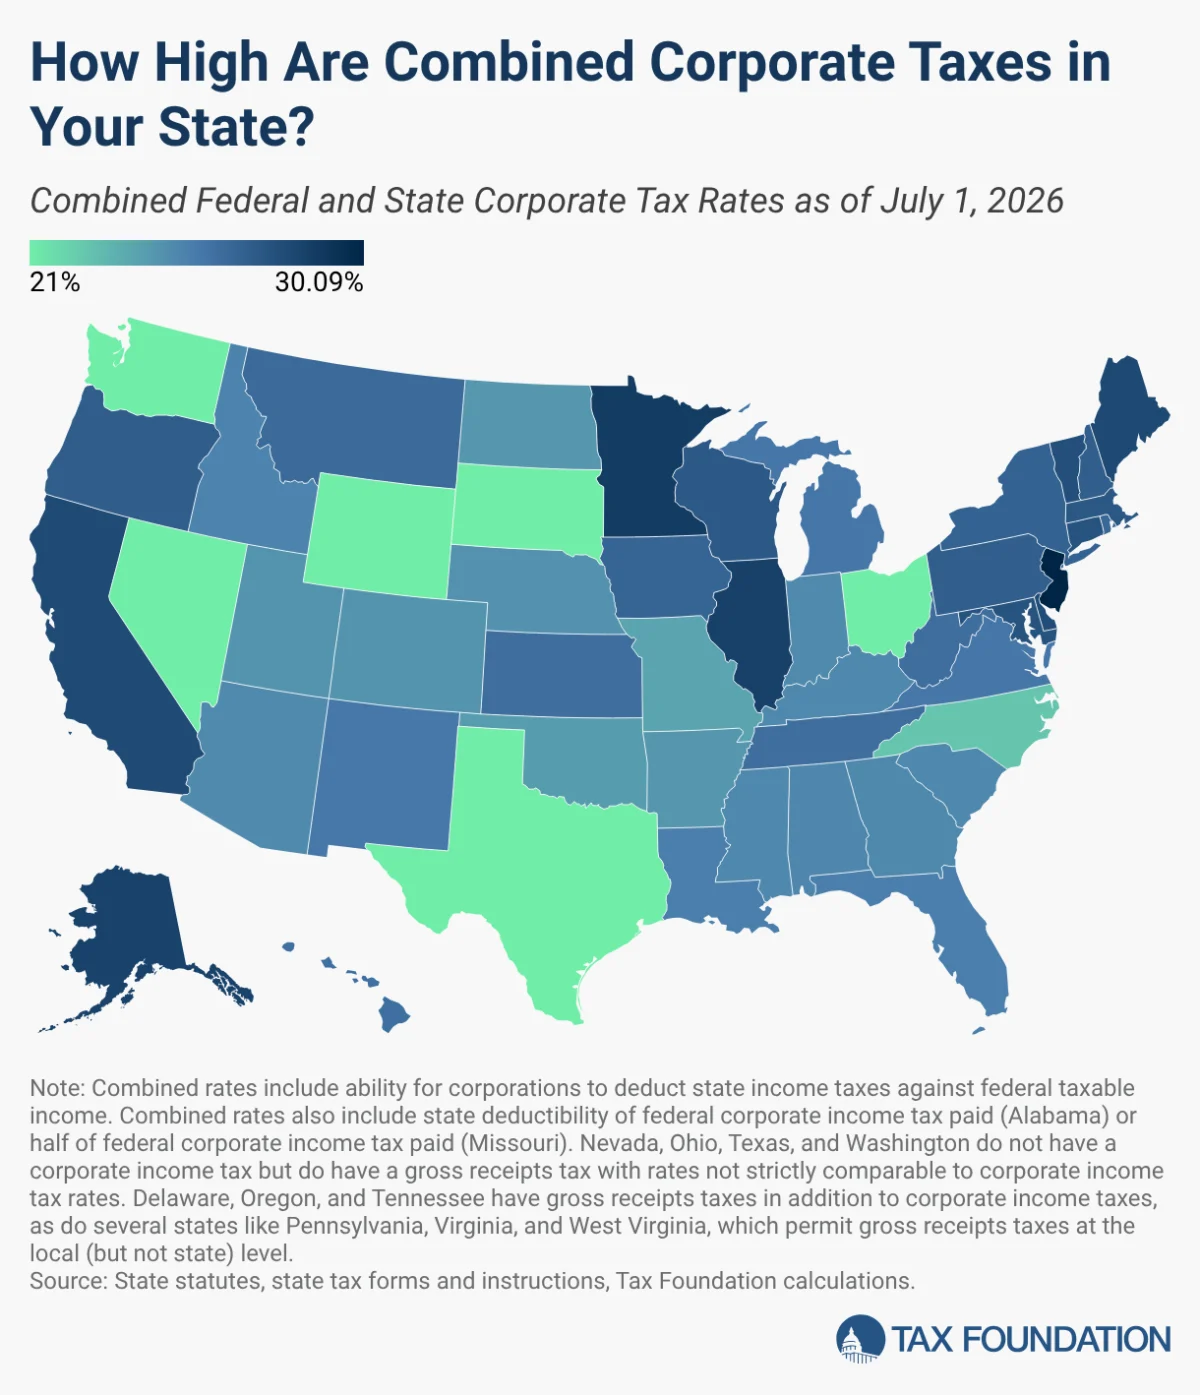
The impact on pass-through businesses is a particular concern for critics. According to the U.S. Small Business Administration, Washington is home to 672,472 small businesses, most of which are pass-through entities. These businesses collectively employ 1.4 million people, representing 48.4 percent of all employees in the state. A 9.9 percent income tax on these owners is seen by many as imposing one of the nation’s highest tax burdens on their income, especially when layered on top of Washington’s existing, high-rate gross receipts tax (the Business & Occupation Tax) and its broad sales tax base, which already subjects an unusually high share of business inputs to taxation.
Economic and Fiscal Implications: A "Worst of Both Worlds" Scenario?
Washington’s tax code has long been characterized by its reliance on business taxes and sales taxes, largely due to the absence of a broad-based individual income tax. Unlike other states without an income tax that often embrace a low-tax, limited-government ethos, Washington’s spending priorities necessitate a substantial tax base, forcing businesses to shoulder a disproportionate share of the overall tax burden.
Opponents argue that by layering a high-rate income tax specifically on high earners, many of whom are small business owners, the state is creating a "worst of both worlds" scenario. They contend that this approach limits the ability of these businesses to reinvest, expand, and create jobs, potentially undermining economic vitality. The combined top state and local tax rate for some high earners in Seattle could reach an astonishing 18.037 percent. This figure amalgamates the new 9.9 percent state income tax with existing local levies such as the 5 percent Seattle Social Housing Tax, the 2.557 percent Seattle JumpStart Tax, and the 0.58 percent WA Cares tax. This combined rate would position Seattle among the highest-taxed jurisdictions for top earners in the entire country, a significant shift for a state previously known for its lack of income taxation.
Beyond the rate itself, the tax features an unusual design that has raised concerns. Its charitable deduction is capped at $50,000, which critics argue disproportionately impacts higher-income individuals who often make larger philanthropic contributions. Furthermore, the $1 million threshold applies identically to single and joint filers. This means two single earners, each making $600,000 (totaling $1.2 million), would not face any tax liability, while a married couple filing jointly with the same combined income would be taxed on the amount exceeding $1 million. This lack of adjustment for filing status is seen as creating a "marriage penalty."
Another critical design flaw, according to tax experts, is the absence of a safe harbor provision for those who unexpectedly become subject to the tax or misjudge their liability. Under federal law and in most other states, underpayment penalties are typically waived if a taxpayer pays at least 90 percent of their current year’s tax liability or 100 (or 110) percent of their prior year’s tax liability through withholding or quarterly estimated payments. Washington’s new tax lacks such a provision, meaning an individual whose income suddenly spikes above the threshold due to an RSU vesting event or a business sale could face unexpected penalties, even if they had no prior history of being a high-income earner for tax purposes.
Legal Battle and Constitutional Questions
The legal foundation of Washington’s high-earner income tax remains highly contested. A date has been set for oral arguments in a constitutional challenge to the new law, a challenge rooted in the state’s long-standing legal history regarding income taxation. Washington’s constitution has historically been interpreted by its Supreme Court as largely prohibiting income taxation, particularly if it is not uniformly applied. Previous attempts to implement income taxes in Washington have been struck down on these grounds, with courts often classifying income as "property" and thus subject to the state’s uniformity clause, which mandates that all property be taxed at the same rate. Proponents of the new tax argue that it is structured differently, perhaps as an excise tax on the "privilege" of earning high income, rather than a direct property tax, to navigate these constitutional hurdles. However, opponents maintain that it is, in essence, an income tax and therefore unconstitutional under existing precedent. The outcome of this pending litigation will be a pivotal moment for the future of the tax and potentially for Washington’s broader fiscal policy.
The Ballot Box: Initiative 645 and Voter Sentiment
With the legislative and legal avenues for review restricted, opponents of the income tax have taken their fight directly to the voters. Initiative 645, successfully placed on the November ballot, seeks to reverse the legislature’s decision and prevent the new tax from taking effect.
The campaign surrounding Initiative 645 is expected to be fiercely contested. Proponents of the repeal effort will likely emphasize the constitutional concerns, the burden on small businesses, and the perceived overreach of government. They will also highlight the historical context of Washington voters consistently rejecting income tax measures. Over the decades, Washingtonians have repeatedly voted down various forms of income tax proposals, underscoring a deep-seated skepticism toward such levies. Research from the Washington Secretary of State’s office shows a clear pattern of voters rejecting income tax ballot measures throughout the state’s history.
However, the path to repeal through the ballot measure is an uphill battle, made more challenging by the official ballot language. Critics have pointed out that the ballot wording for Initiative 645 includes a warning that repeal would necessitate cuts to education funding. This statement has generated considerable controversy, as the tax is not yet in place, and no state budget has been adopted that incorporates these future revenues. A 2022 law allows the attorney general to supply a fiscal impact statement to ballot measures, but opponents argue that in this instance, the statement speaks of decreasing funding even though the tax in question does not yet exist and its revenues are purely prospective. This framing, they contend, is designed to sway voters by implying immediate and tangible negative consequences for essential services if the tax is repealed.
Broader Implications and Future Outlook
The ongoing saga of Washington’s high-earner income tax represents a critical juncture for the state’s fiscal policy. The debate is not merely about a specific tax rate or threshold but about the fundamental structure of taxation in a rapidly growing and diversifying economy.
One state lawmaker has already proposed reducing the tax threshold to as low as $250,000, significantly expanding the pool of taxpayers who would be subject to the levy. This early discussion of expansion, even before the initial tax takes effect, fuels concerns among critics that the current $1 million threshold is merely a starting point for a broader income tax.
Advocates for the tax argue that it is a necessary step toward creating a more equitable tax system, where wealthier individuals contribute a larger share to state services, and to diversify Washington’s revenue streams, which are heavily reliant on sales and property taxes and can be volatile. They contend that the revenues are vital for supporting education, infrastructure, and other public institutions.
Conversely, opponents fear that the tax will deter high-income earners and businesses from relocating to or expanding within Washington, potentially harming the state’s economic competitiveness, particularly its thriving technology sector. The dual pressures of a constitutional challenge and a public vote highlight the profound uncertainty surrounding this landmark tax.
As the legal arguments unfold and the November election approaches, all eyes will be on Washington State. The outcome will not only determine the fate of this specific tax but could also set a precedent for future tax policy, potentially reshaping the economic landscape and the social contract between citizens and government in the Pacific Northwest for decades to come. The resolution of this multifaceted challenge will be a defining moment in Washington’s fiscal history, reflecting the ongoing tension between revenue needs, economic competitiveness, and deeply ingrained public sentiment regarding taxation.