Lana Rhoades
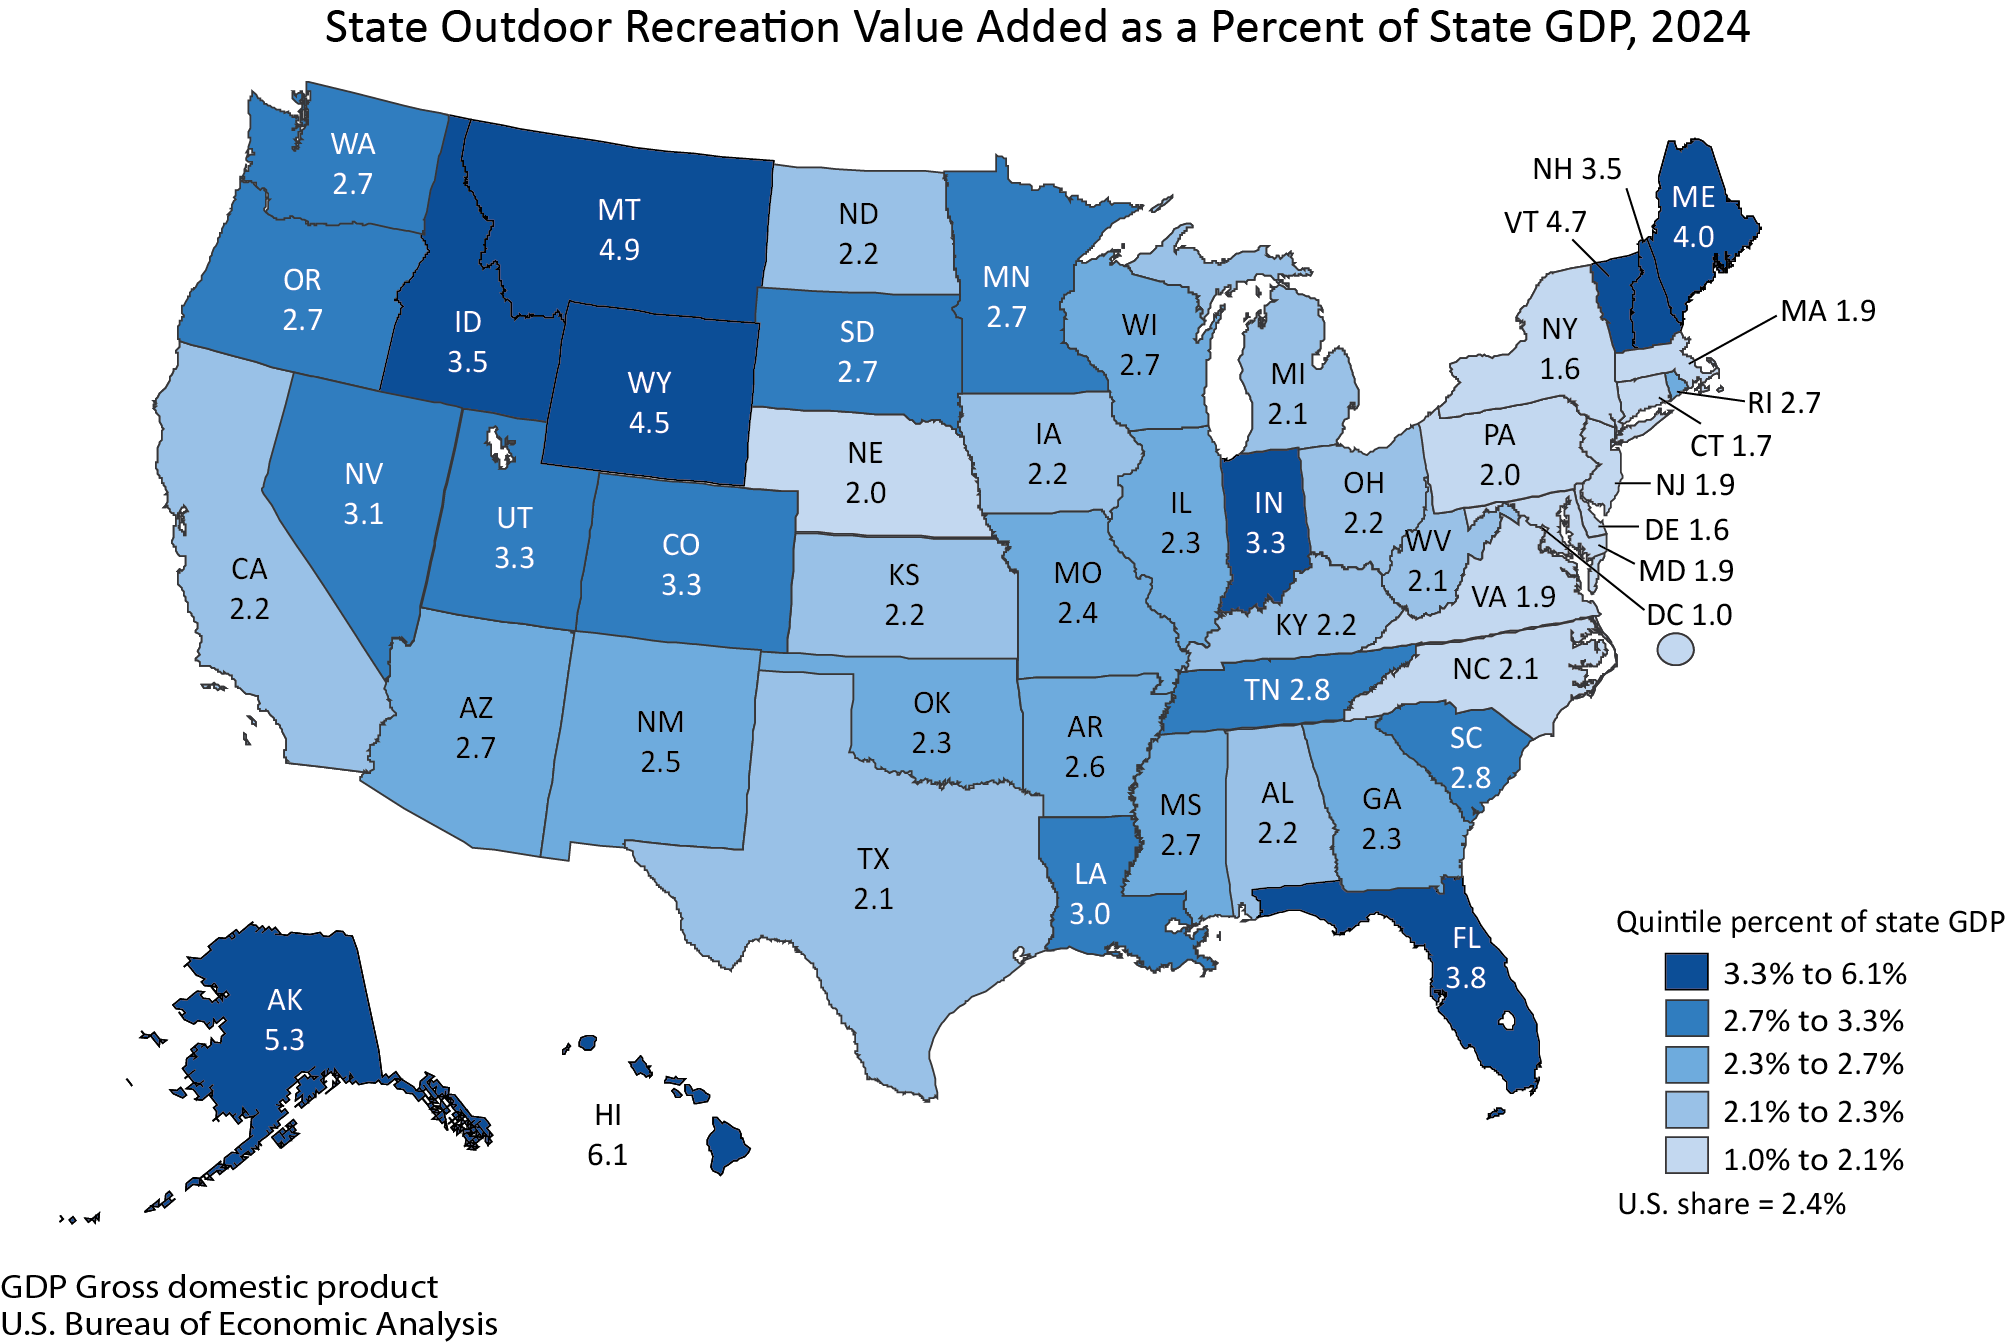
The United States Bureau of Economic Analysis (BEA) has unveiled its latest comprehensive report detailing the economic impact of the nation’s outdoor recreation sector. For the year 2024, the outdoor recreation economy demonstrably solidified its significant role in the U.S. economic landscape, accounting for a substantial 2.4 percent of the nation’s current-dollar Gross Domestic Product (GDP). This translates to an impressive value added of $696.7 billion, underscoring the sector’s robust contribution to national economic output. The report, which provides granular data for all 50 states and the District of Columbia, also highlights considerable variation in the sector’s economic significance across different regions, with Hawaii leading the nation at 6.1 percent of its state GDP, while the District of Columbia registered 1.0 percent.
This annual update from the BEA is a critical indicator for policymakers, industry leaders, and researchers, offering a detailed snapshot of a dynamic and increasingly vital economic engine. The BEA’s methodology, which incorporates updated national and regional economic accounts along with newly available source data, ensures the statistics are as accurate and timely as possible, reflecting the evolving nature of consumer engagement with outdoor activities.
National Economic Performance and Trends
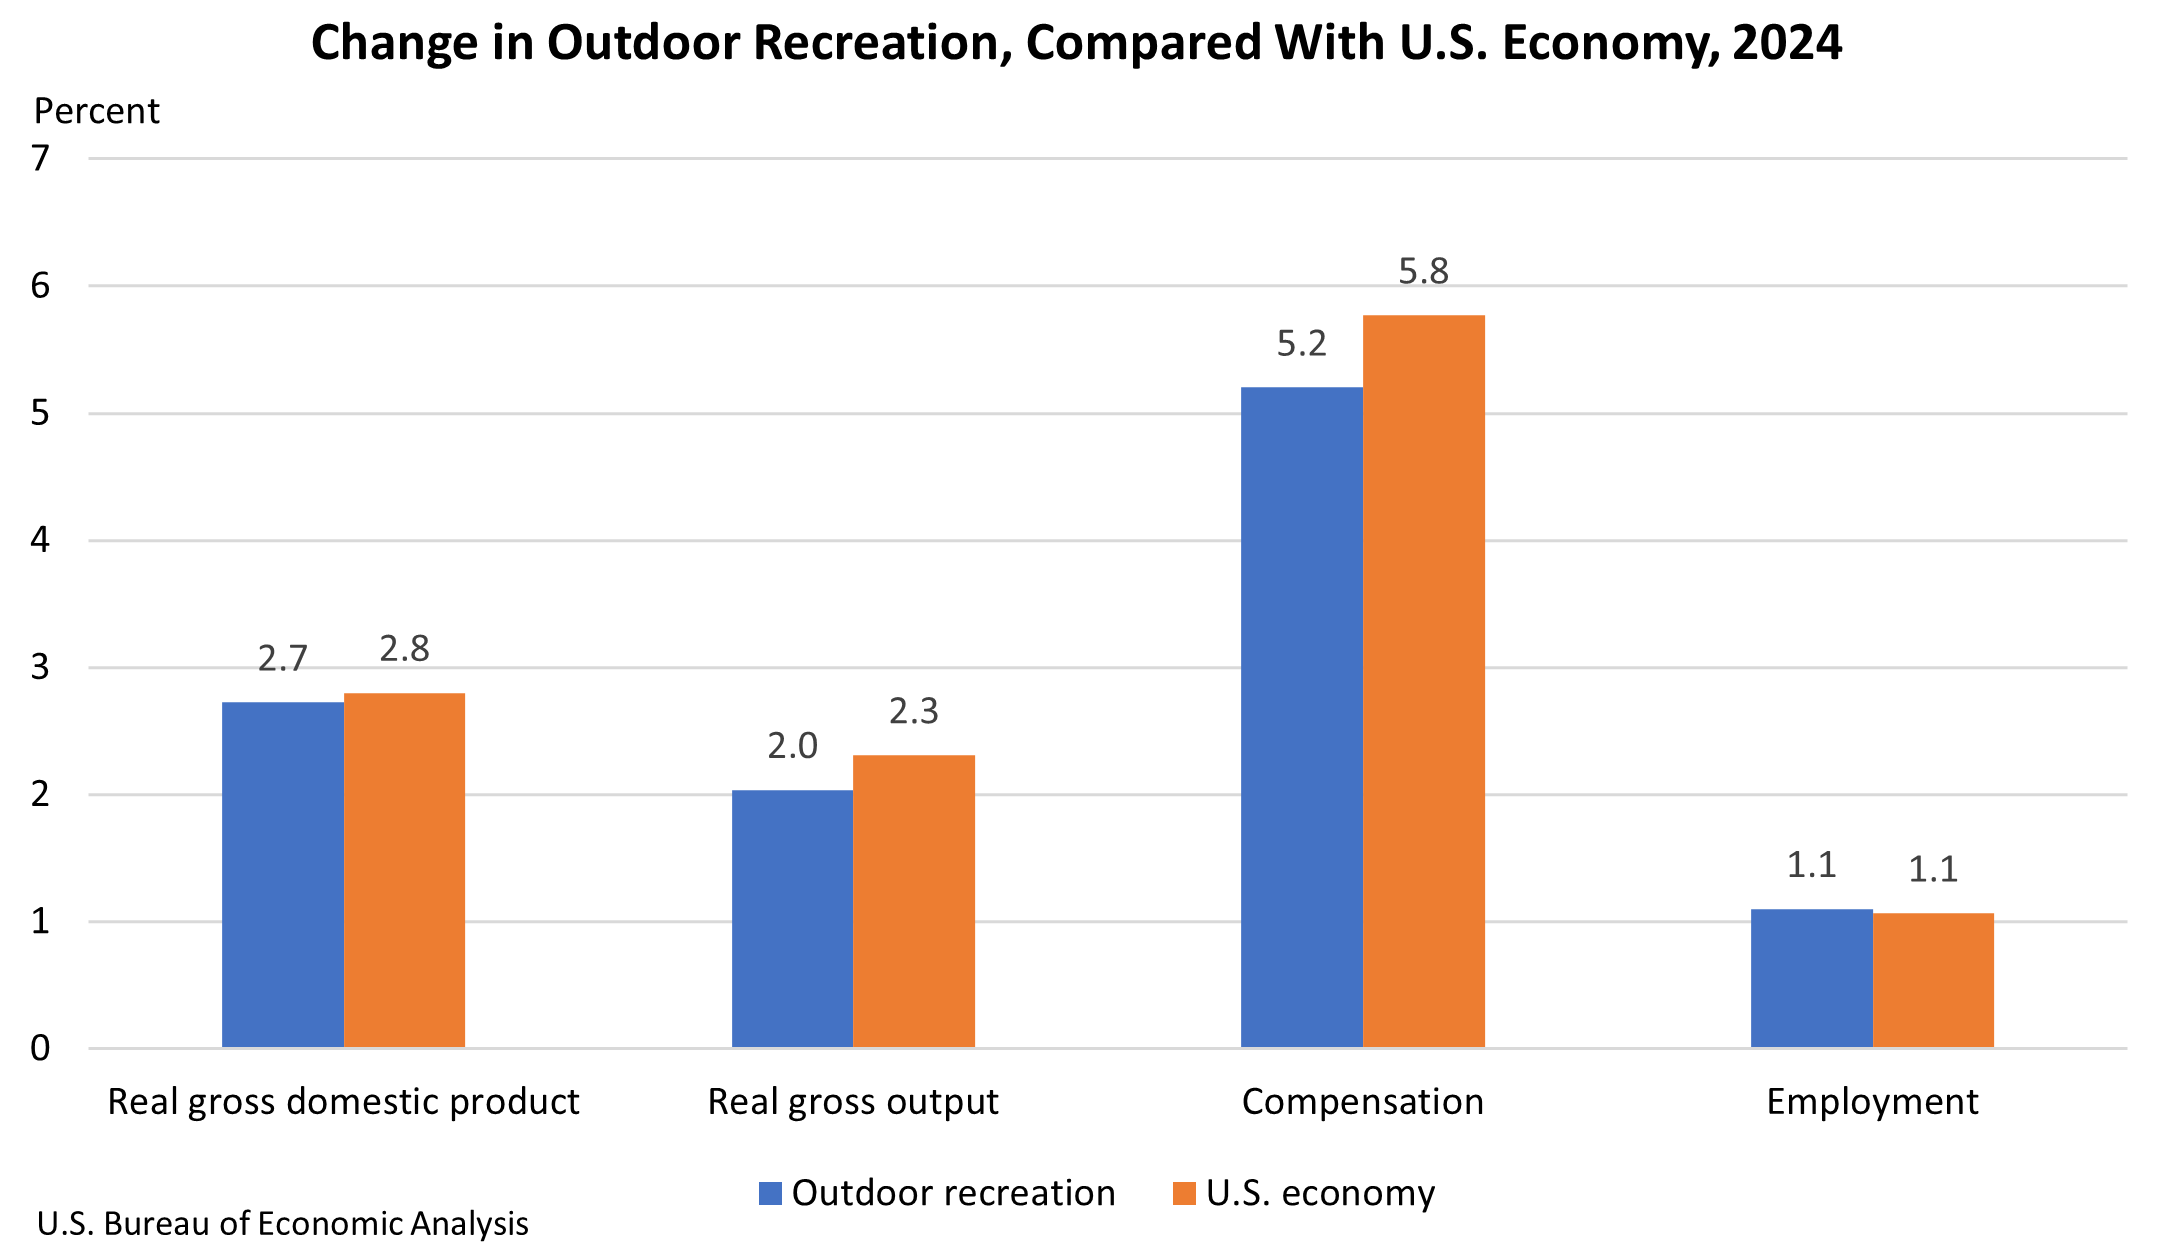
In terms of inflation-adjusted ("real") GDP, the outdoor recreation economy experienced a growth of 2.7 percent in 2024. While this figure represents a slight deceleration from the robust 5.3 percent growth observed in 2023, it still outpaced the overall U.S. economy’s growth rate of 2.8 percent for the same period. This sustained, albeit moderated, expansion suggests a resilient demand for outdoor experiences, even as the broader economic environment adjusts. The BEA’s data further reveal that real gross output for the outdoor recreation economy rose by 2.0 percent.
Crucially, the sector also demonstrated positive momentum in employment and compensation. Outdoor recreation compensation saw a significant increase of 5.2 percent, indicating that workers in this sector are benefiting from the industry’s expansion. Employment within the sector also grew by 1.1 percent, a testament to the ongoing creation of jobs directly and indirectly related to outdoor pursuits.
State-Level Variations and Employment Dynamics
The impact of the outdoor recreation economy is not uniform across the nation, with significant regional disparities evident in its contribution to state GDP. Hawaii’s leading position, with 6.1 percent of its state GDP derived from outdoor recreation, highlights the economic importance of its natural beauty and associated tourism and leisure activities. Conversely, the District of Columbia’s lower percentage of 1.0 percent reflects its unique economic structure, which is less reliant on traditional outdoor recreation activities compared to states with extensive natural resources.
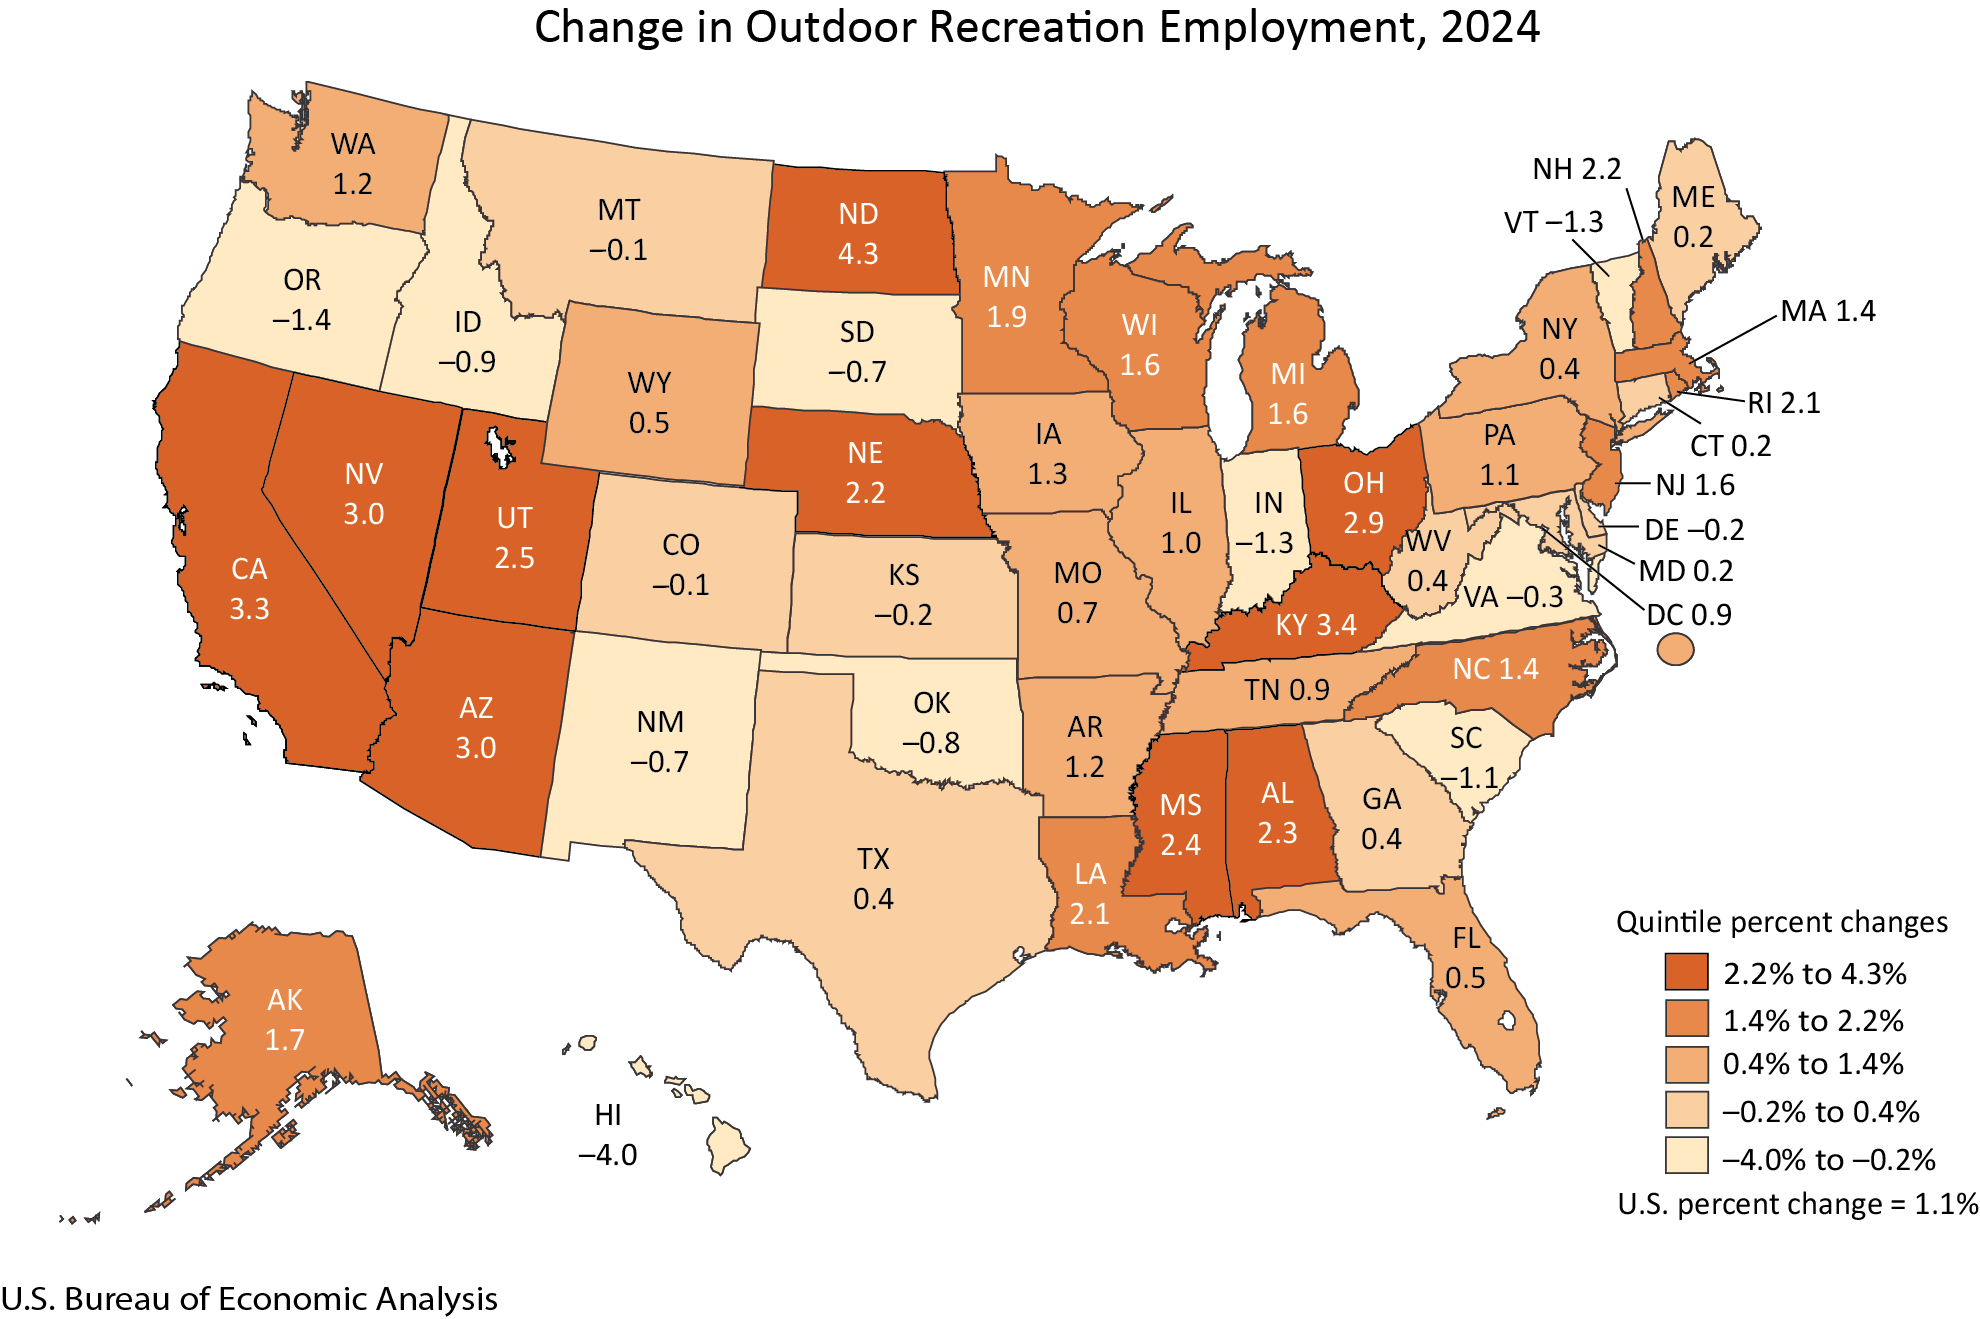
Employment trends within the sector also show considerable variation. In 2024, outdoor recreation employment expanded in 36 states and the District of Columbia. North Dakota recorded the highest percentage increase in outdoor recreation employment at 4.3 percent, suggesting a growing sector in that region. In contrast, Hawaii experienced a decline of 4.0 percent in outdoor recreation employment, a notable shift from its overall economic dominance in the sector. These divergent employment trends underscore the localized nature of the outdoor recreation economy and the diverse factors influencing its growth or contraction in different states, including tourism patterns, climate, and local investment.
Breakdown by Activity: Shifting Consumer Engagement
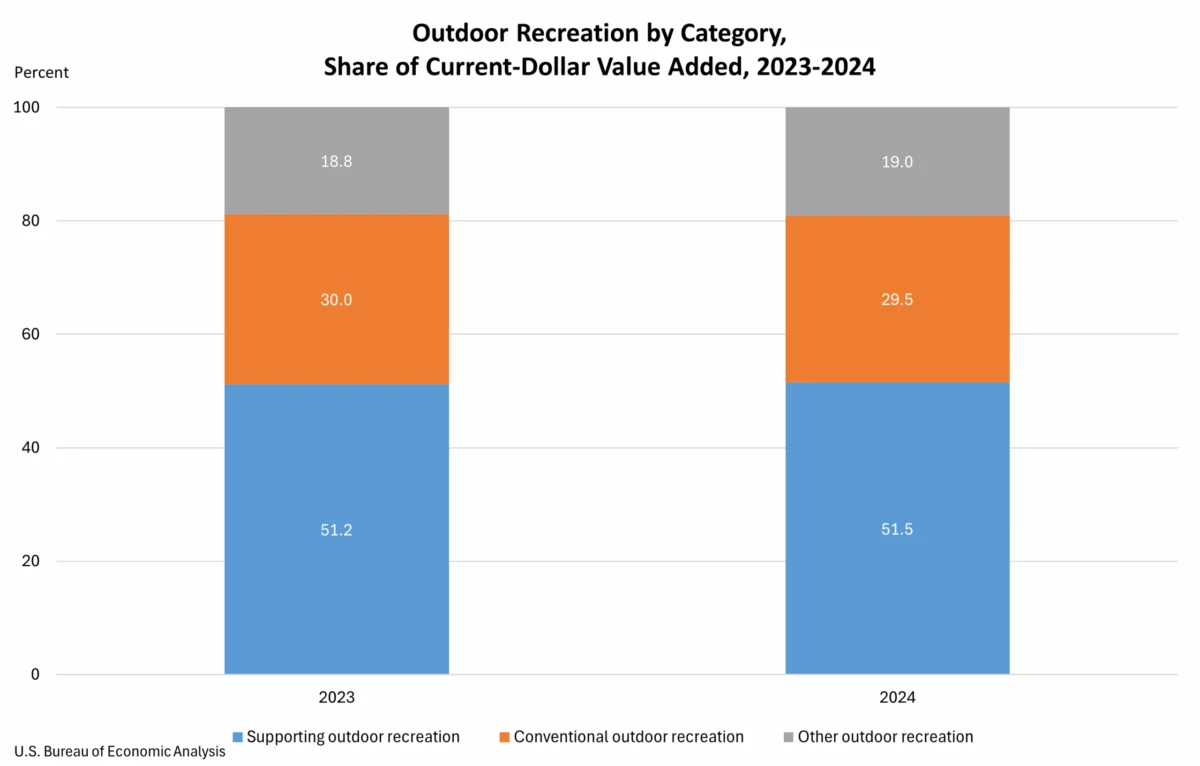
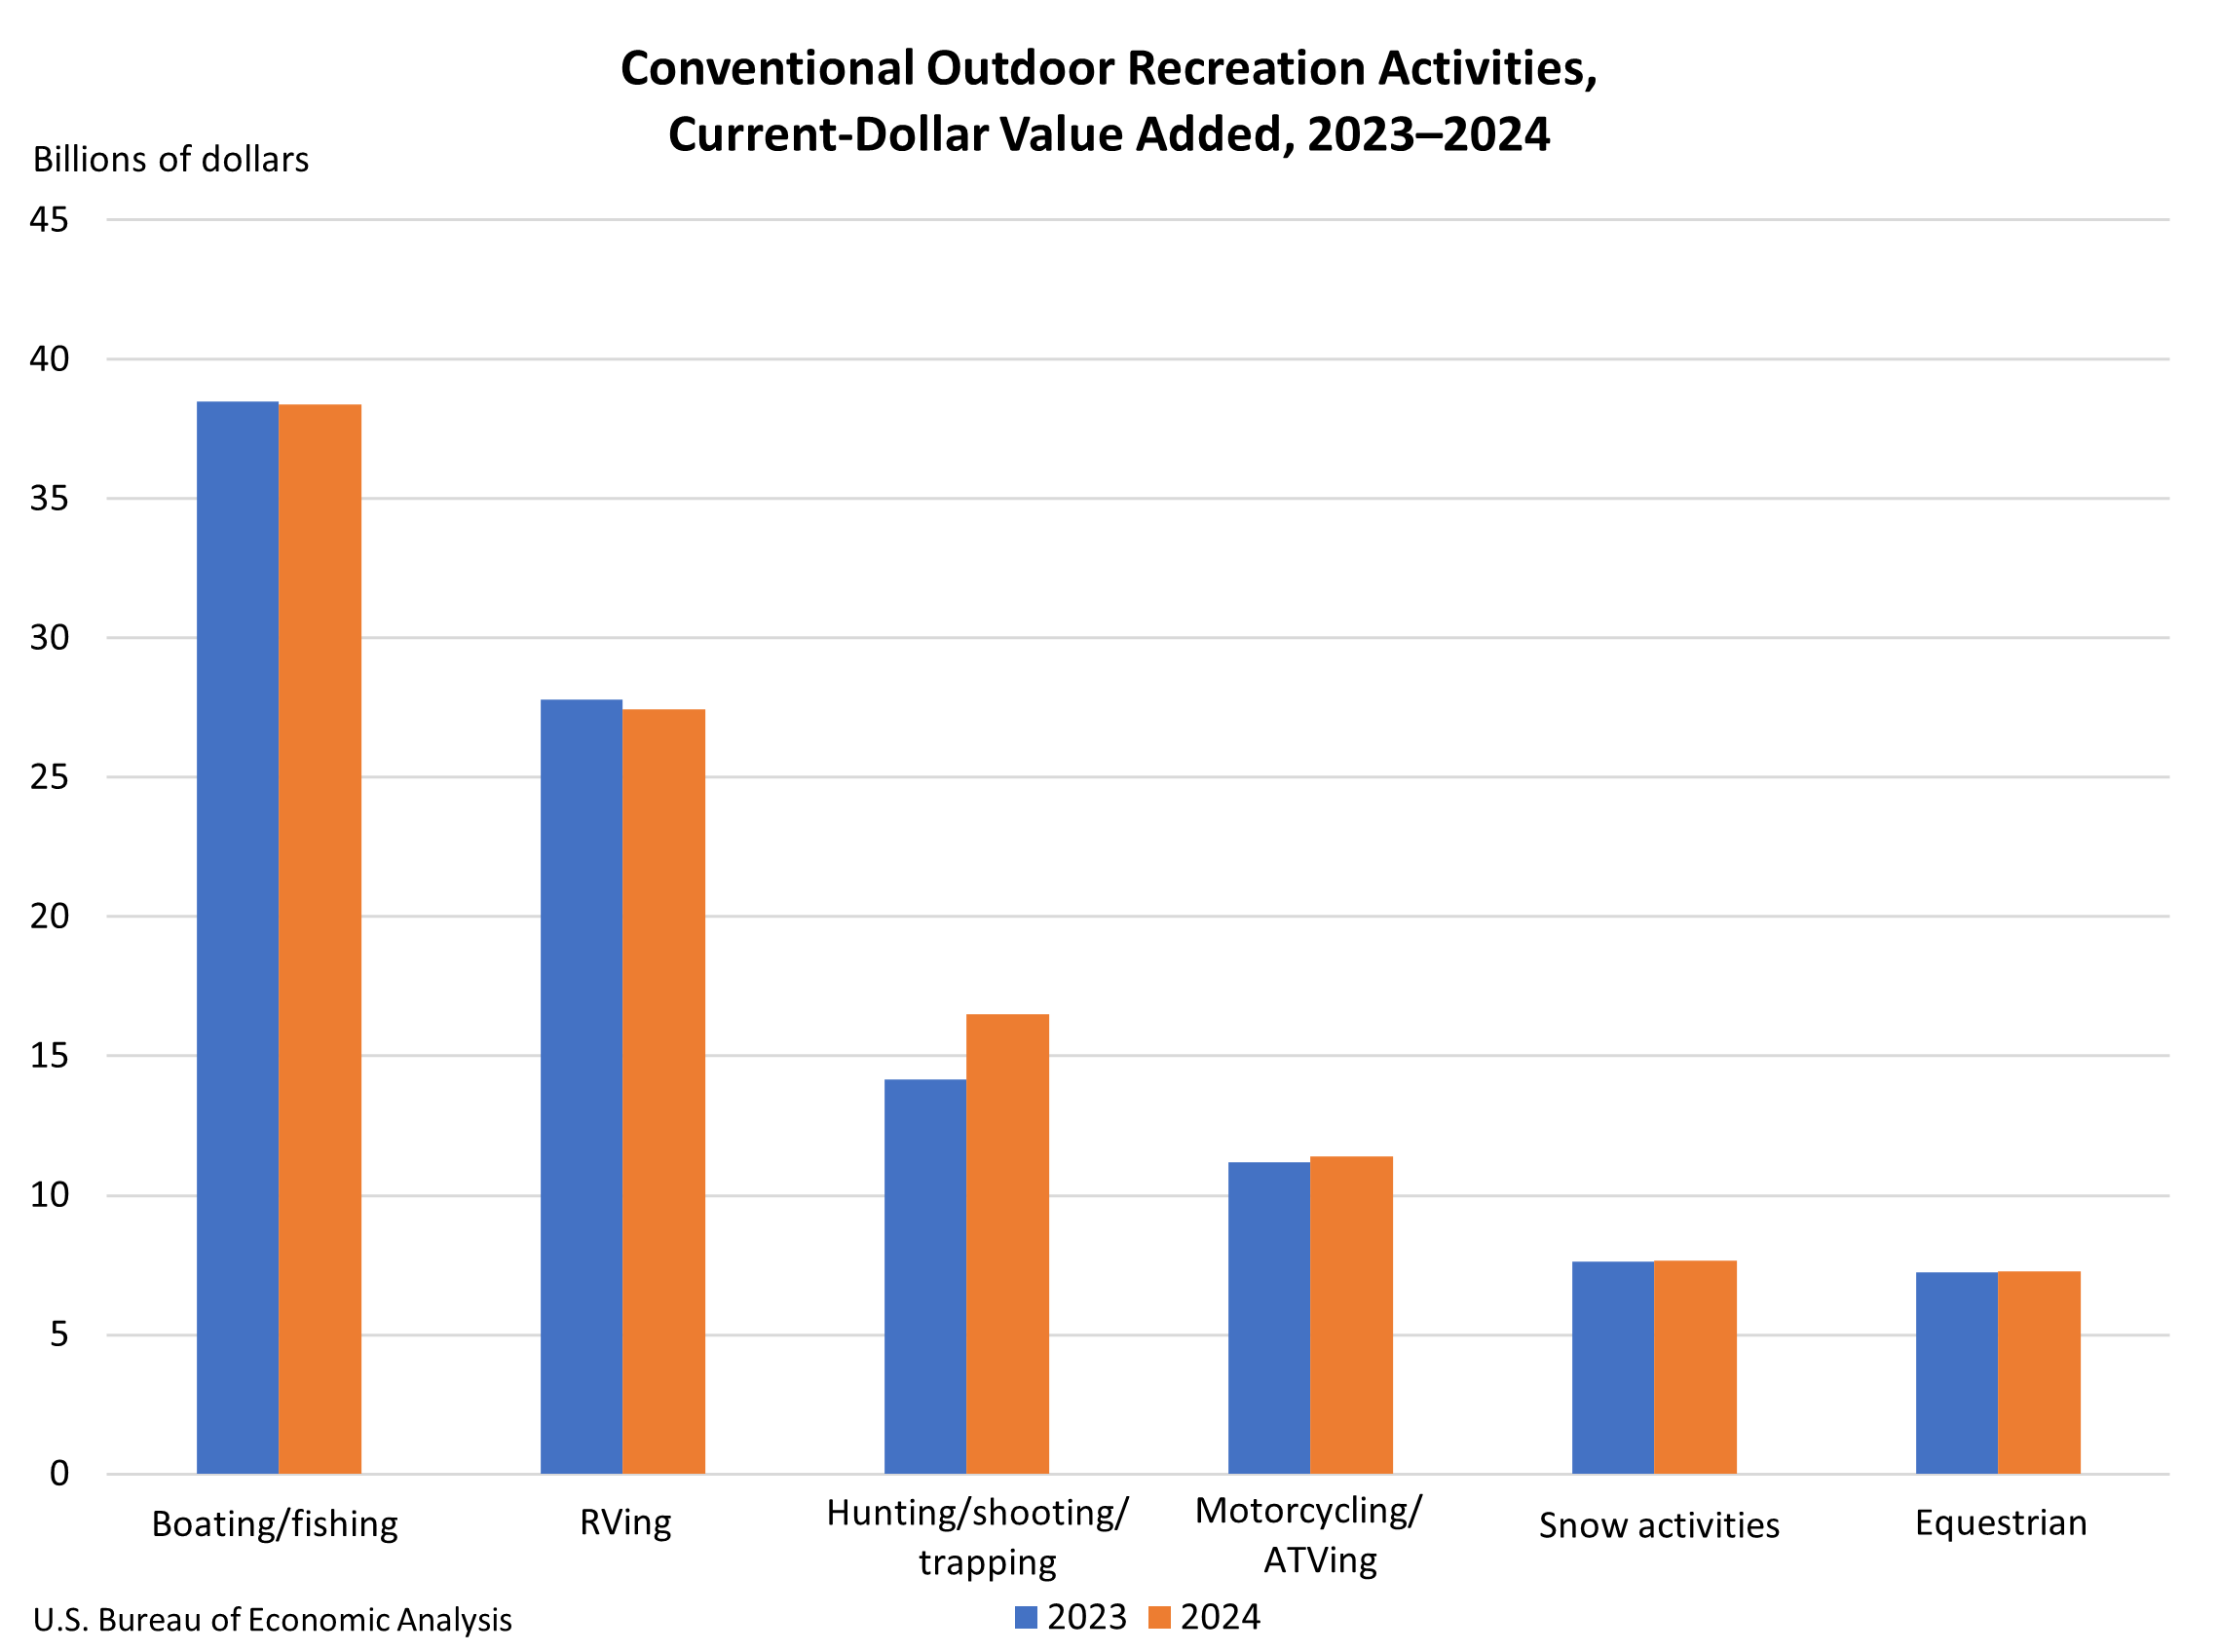
The BEA categorizes outdoor recreation activities into three primary groups: conventional activities (e.g., bicycling, boating, hiking, hunting), other activities (e.g., gardening, outdoor concerts), and supporting activities (e.g., construction, travel and tourism, local trips, government expenditures).
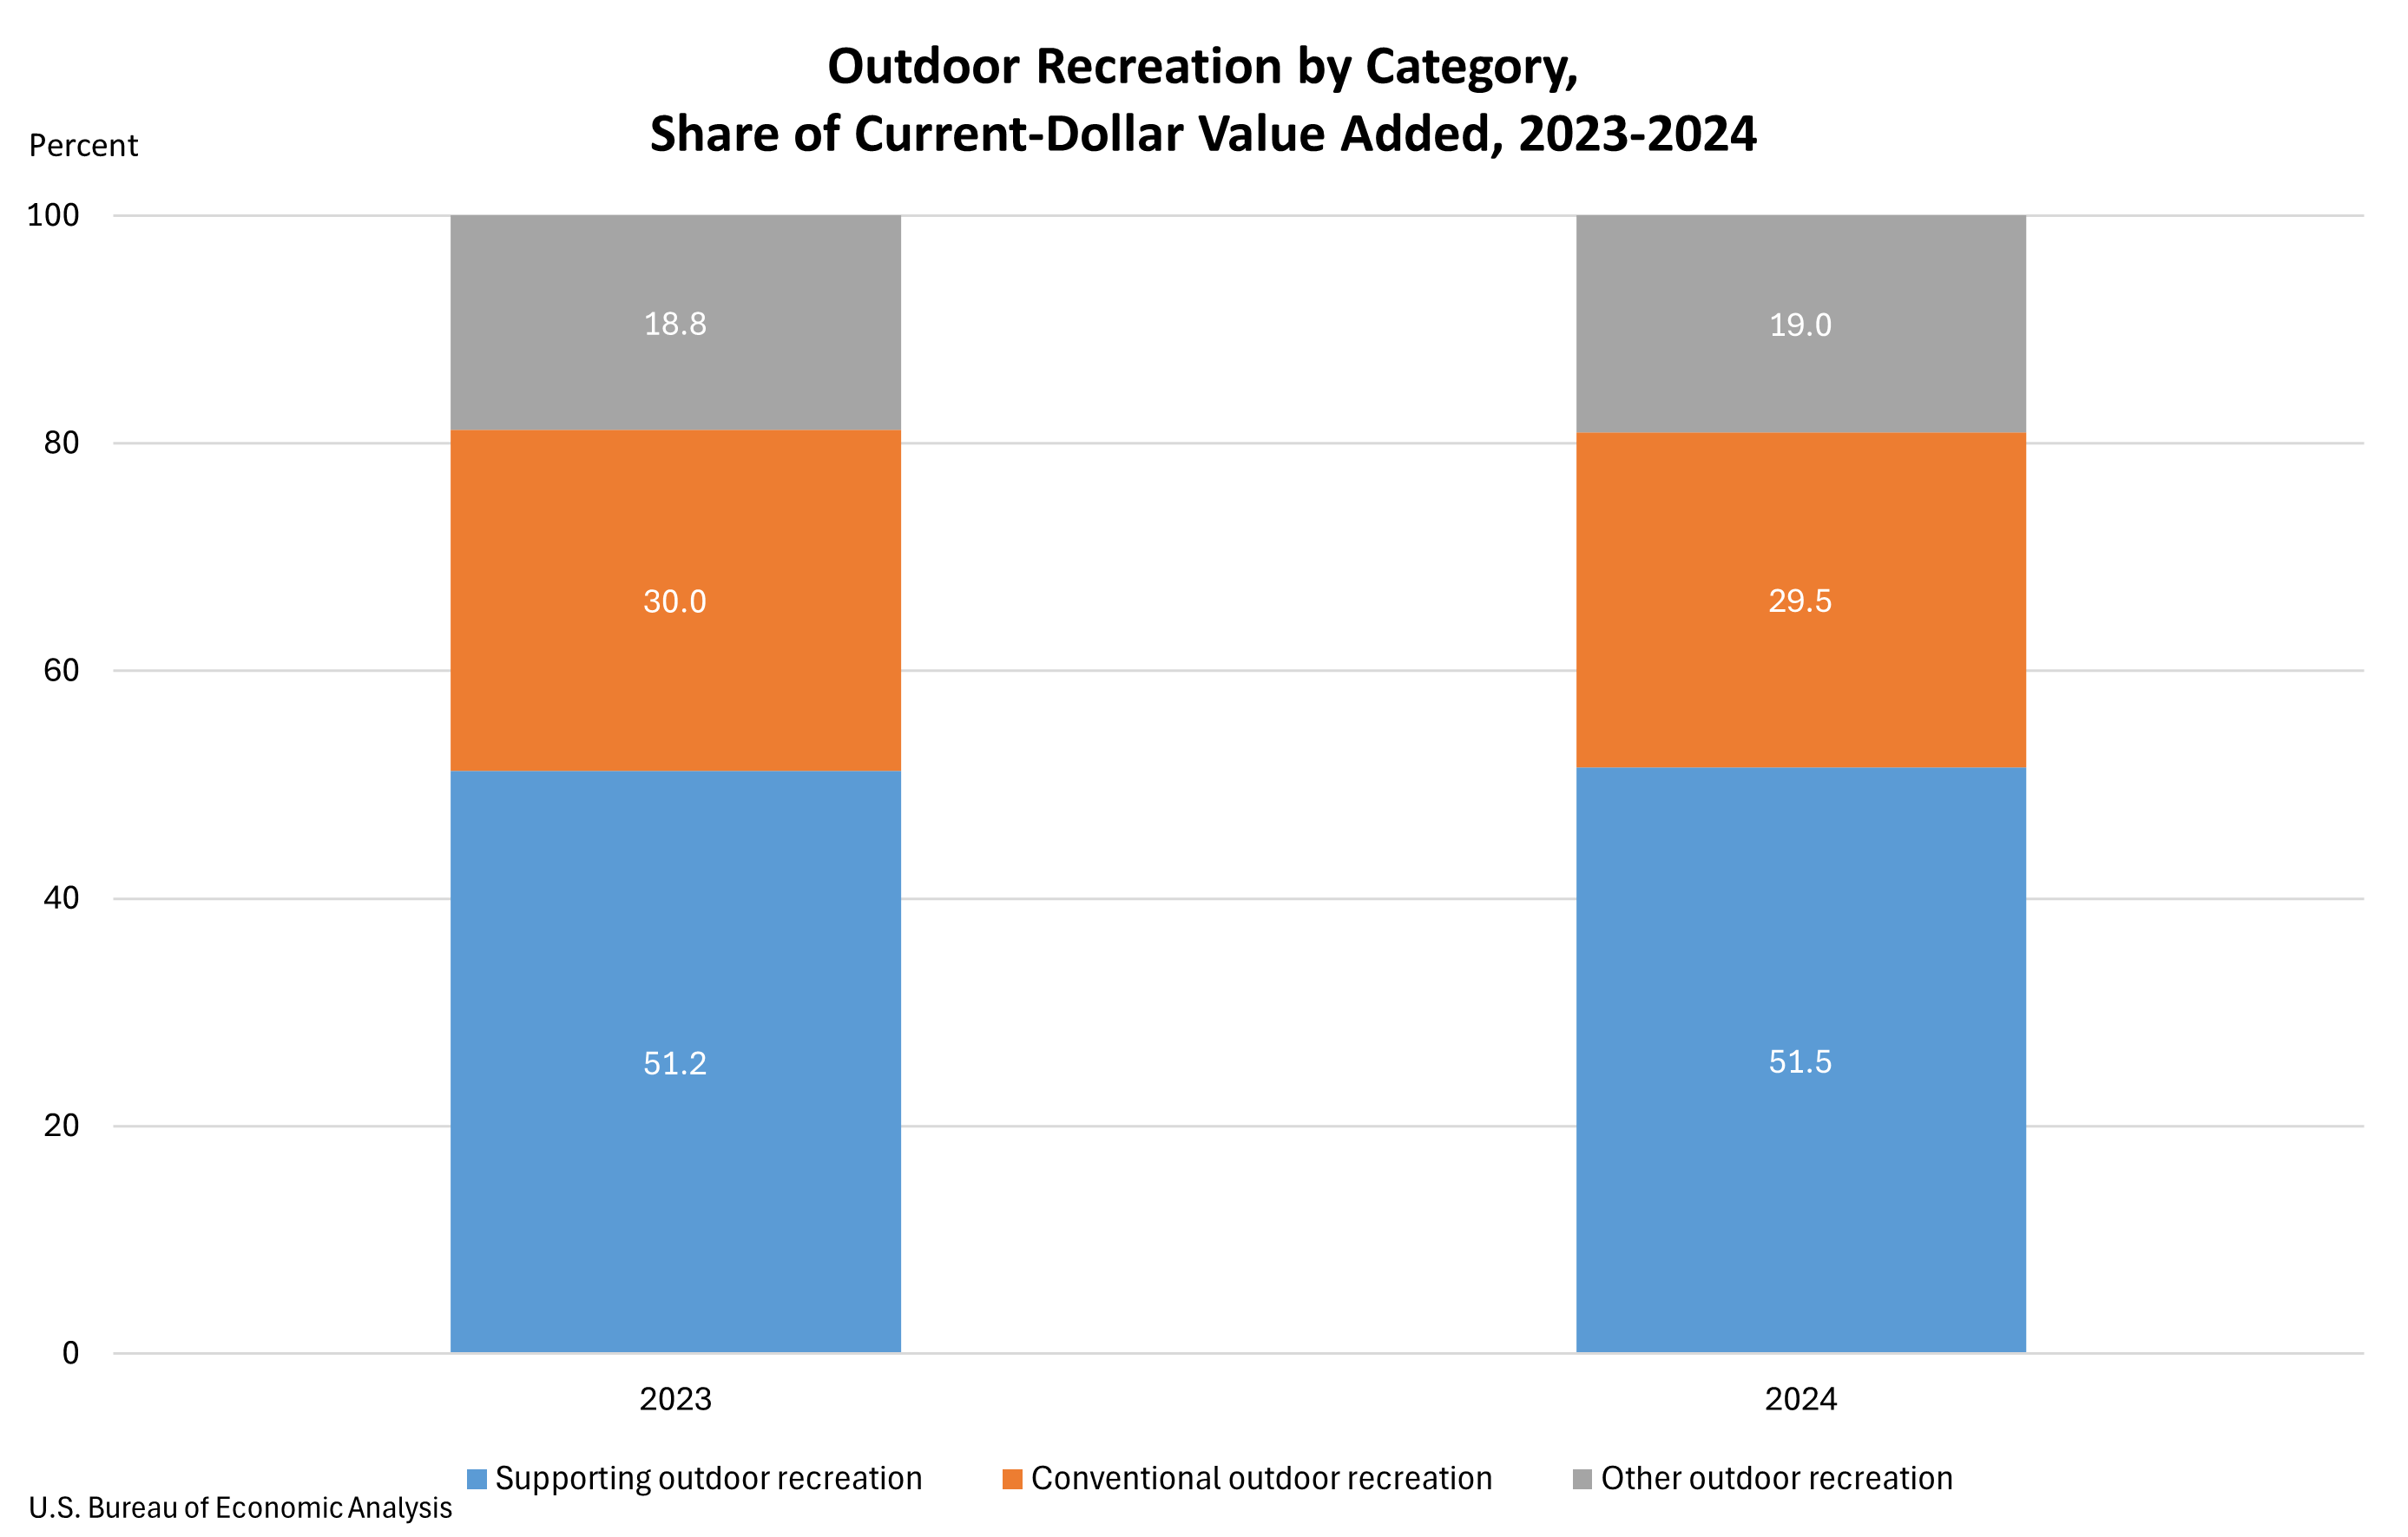
In 2024, conventional outdoor recreation activities accounted for 29.5 percent of the sector’s total value added, a slight decrease from 30.0 percent in 2023. "Other outdoor recreation" activities saw a marginal increase, representing 19.0 percent of value added, up from 18.8 percent in the previous year. The largest share, however, continued to be dominated by supporting activities, which comprised 51.5 percent of value added in 2024, compared to 51.2 percent in 2023. This growth in supporting activities was particularly driven by the travel and tourism sub-sector, which includes spending on transportation, accommodation, and food services. This indicates that while direct participation in activities like hiking and boating remains crucial, the broader ecosystem of services that enables and enhances these experiences is a significant economic driver.
The data suggest a subtle but important shift in consumer engagement. While direct participation in traditional outdoor pursuits remains strong, the growth in supporting activities points to an increasing reliance on and investment in the infrastructure and services that facilitate these experiences. This includes everything from the development of new hotels and restaurants near popular outdoor destinations to improvements in transportation networks that make these areas more accessible.
Industry Contributions to the Outdoor Recreation Economy
The BEA’s analysis also delves into the specific industries that contribute to the outdoor recreation economy. The "arts, entertainment, recreation, accommodation, and food services" industry group emerged as the largest contributor to the nation’s outdoor recreation value added in 2024, accounting for $174.4 billion, or 25.0 percent of the total. This sector is a cornerstone, providing the services and experiences that directly cater to outdoor enthusiasts. At the state level, this industry group was the leading contributor in 23 states and the District of Columbia. California, Florida, and New York led the nation in this category, with contributions of $24.1 billion, $22.7 billion, and $11.8 billion, respectively, highlighting the economic power of these states in leisure and hospitality.
The "retail trade" sector followed as the second-largest contributor nationally, generating $169.1 billion, or 24.3 percent of value added. This sector is vital for providing the equipment, apparel, and supplies necessary for a wide range of outdoor activities. Retail trade was the dominant industry in 24 states, with California, Texas, and Florida again showing significant contributions of $19.3 billion, $14.4 billion, and $13.4 billion, respectively. The strong performance of retail trade underscores the direct link between consumer spending on gear and the overall health of the outdoor recreation economy.
The "manufacturing" sector ranked third nationally, contributing $91.3 billion, or 13.1 percent of value added. This includes the production of vehicles, equipment, and apparel. Manufacturing was the largest industry contributor in two states, Indiana and Louisiana. Texas, California, and Indiana posted the highest manufacturing contributions to outdoor recreation, with figures of $13.1 billion, $11.6 billion, and $9.1 billion, respectively. This highlights the importance of manufacturing in supplying the goods that fuel outdoor pursuits, from boats and bicycles to specialized clothing.
Context and Implications of the BEA Report
The release of these detailed statistics by the BEA marks an annual update to a crucial economic dataset. The BEA has been tracking the economic impact of outdoor recreation since 2016, with the goal of providing a more comprehensive understanding of this sector’s contribution to the U.S. economy. The methodology has evolved over time, incorporating new data sources and refining analytical approaches to capture the full scope of outdoor recreation’s economic influence. The current report benefits from updates to the National Income and Product Accounts and the Industry Economic Accounts, as well as regional economic data.
The implications of this report are far-reaching. For policymakers, the data provide a strong economic rationale for investing in and supporting the outdoor recreation sector. This can include infrastructure development, conservation efforts, and policies that promote access to public lands and waters. For businesses within the sector, the report offers valuable insights into consumer trends, industry performance, and regional opportunities, enabling more informed strategic planning and investment decisions.
The slight deceleration in real GDP growth for outdoor recreation in 2024, while still positive, may prompt further analysis into the contributing factors. These could include shifts in consumer spending priorities, inflationary pressures affecting discretionary income, or the lingering effects of global economic conditions. However, the continued growth in employment and compensation suggests that the sector remains a vital source of jobs and economic opportunity.
The sustained strength of supporting activities, particularly travel and tourism, indicates that the broader economic ecosystem surrounding outdoor recreation is increasingly important. This suggests that investments in hospitality, transportation, and related services are crucial for maximizing the economic benefits of outdoor recreation. Furthermore, the report’s emphasis on state-level data underscores the need for tailored approaches to supporting and developing the outdoor recreation economy, recognizing the unique characteristics and potential of each region.
As the BEA continues to refine its methodologies and collect more granular data, future reports are expected to offer even deeper insights into the nuances of this vital economic sector. The ongoing commitment to tracking and reporting on the outdoor recreation economy by the BEA reinforces its recognition as a significant and growing contributor to national and regional prosperity. The next release of these statistics is anticipated in the Fall of 2026, covering the 2025 data.