Lana Rhoades
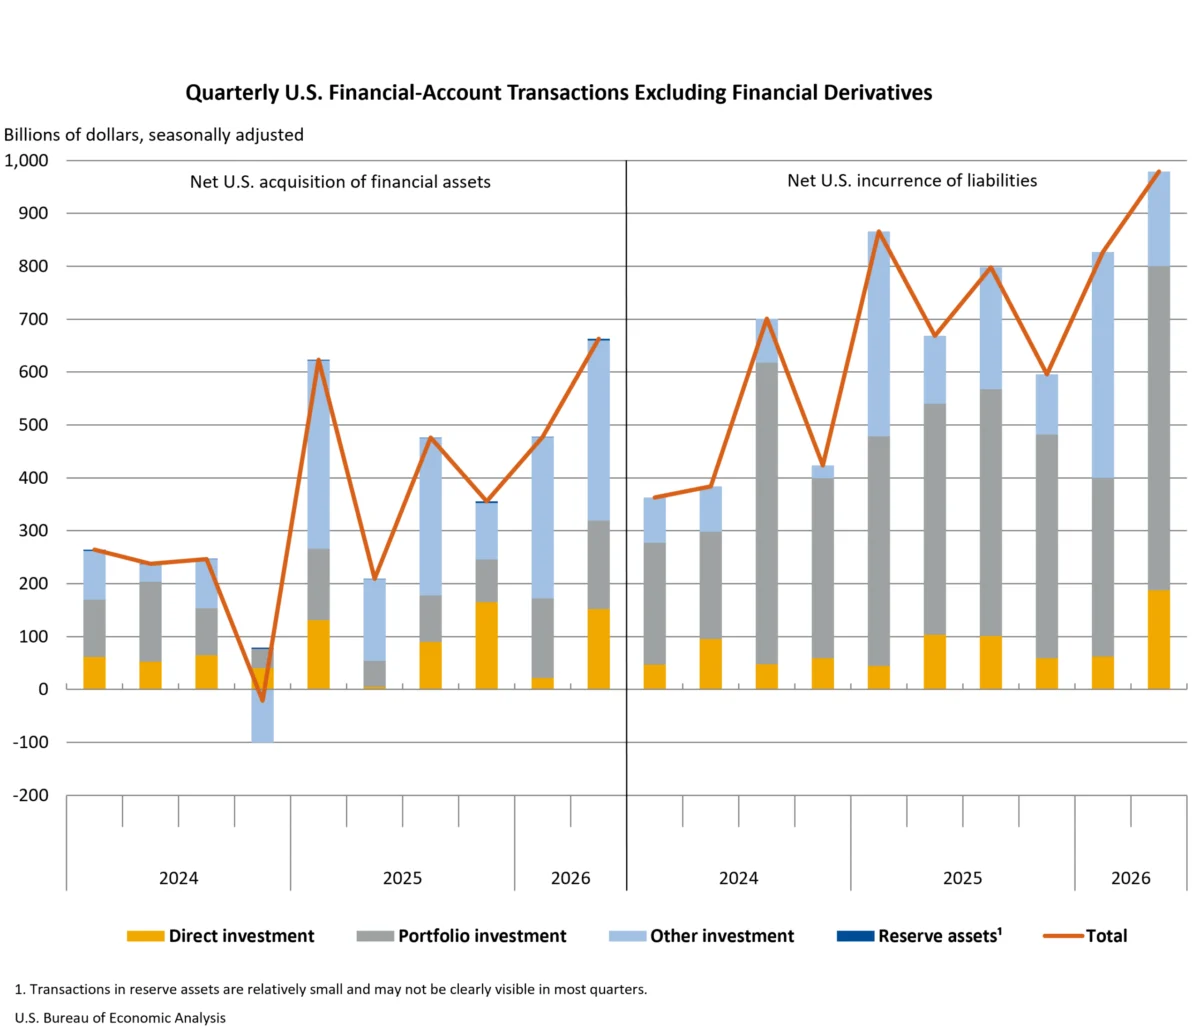
The U.S. current-account deficit, a broad measure of international economic transactions, expanded by $33.4 billion, or 15.7 percent, to reach $246.0 billion in the second quarter of 2026. This widening represents a notable shift from the revised first-quarter deficit of $212.6 billion. The deficit’s proportion of the nation’s gross domestic product (GDP) also saw an increase, rising from 2.7 percent in the first quarter to 3.0 percent in the second quarter, signaling a growing imbalance in the country’s international financial dealings.
Drivers Behind the Widening Deficit
The primary catalyst for the $33.4 billion increase in the current-account deficit was a substantial expansion in the deficit on goods. This indicates that the value of goods imported into the United States outstripped the value of goods exported at an accelerated pace during the second quarter. While this negative trend in goods trade exerted downward pressure on the overall current account, it was partially mitigated by a reduction in deficits related to primary income and secondary income.
Primary income, often referred to as earned income, encompasses earnings from investments abroad and compensation paid to foreign residents for work performed in the U.S. The reduced deficit in this category suggests that either U.S. residents earned more income from their foreign investments, or payments to foreign residents for income earned within the U.S. decreased, or a combination of both. Secondary income, which comprises current transfers such as remittances and foreign aid, also saw its deficit shrink, contributing to a slight stabilization of the current account.
Trade Dynamics: Goods Exports and Imports
The overall flow of goods and services, alongside income receipts from foreign residents, saw a significant uptick, increasing by $58.8 billion to $1.44 trillion in the second quarter. This rise was predominantly fueled by an increase in goods exports, which suggests a stronger demand for American-made products in international markets. Simultaneously, primary income receipts also contributed positively to this component.
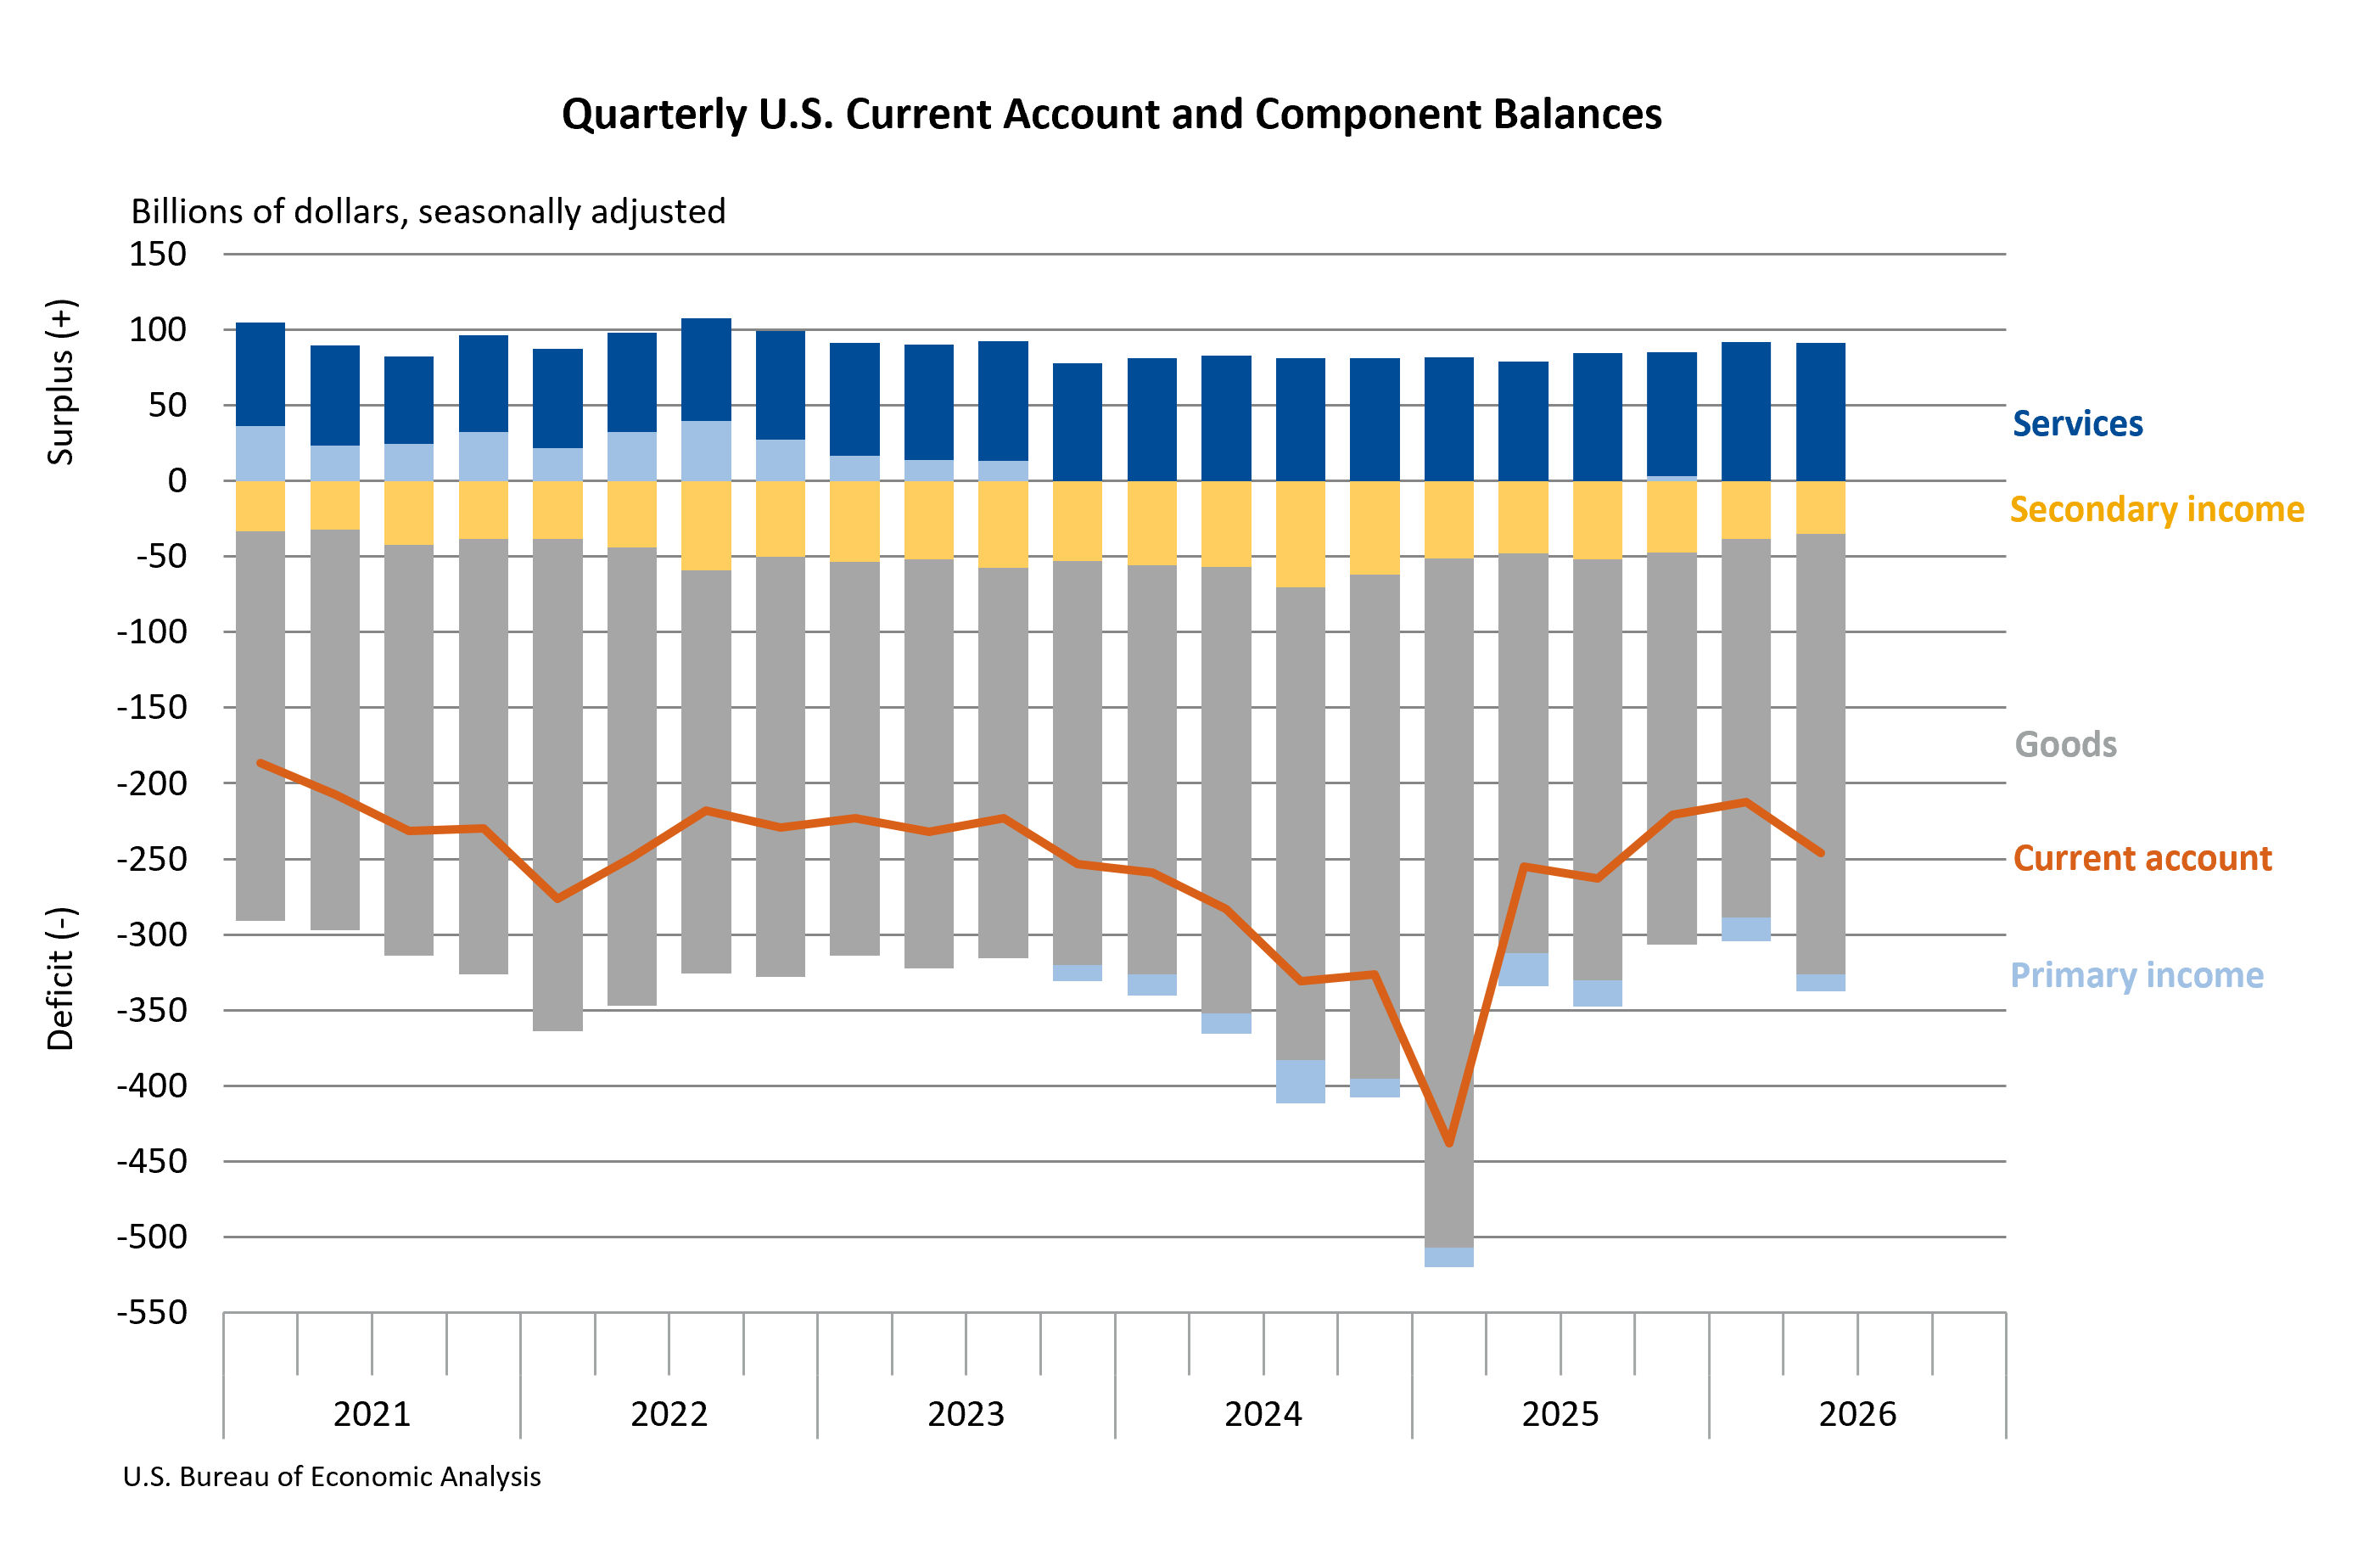
However, the surge in exports was outpaced by an even larger increase in imports of goods and services from, and income paid to, foreign residents. This category grew by $92.2 billion, reaching $1.69 trillion. The dominant factor here was the escalation in goods imports, indicating a robust domestic appetite for foreign-made products. Payments for primary income to foreign residents also rose, contributing to the overall expansion of this outflow.
The net effect of these opposing trends in exports and imports resulted in a wider trade deficit, which is a significant component of the current account. This dynamic underscores the ongoing challenges in balancing the nation’s trade in physical goods.
Capital Transfers and Financial Account Activity
Beyond the trade in goods and services and income flows, the current account also accounts for capital transfers. In the second quarter of 2026, capital-transfer receipts experienced a decrease of $1.1 billion, settling at $2.3 billion. Similarly, capital-transfer payments also declined, falling by $0.9 billion to $1.0 billion. These movements represent a net outflow of capital through transfers, albeit a relatively small one in the context of the overall current account.
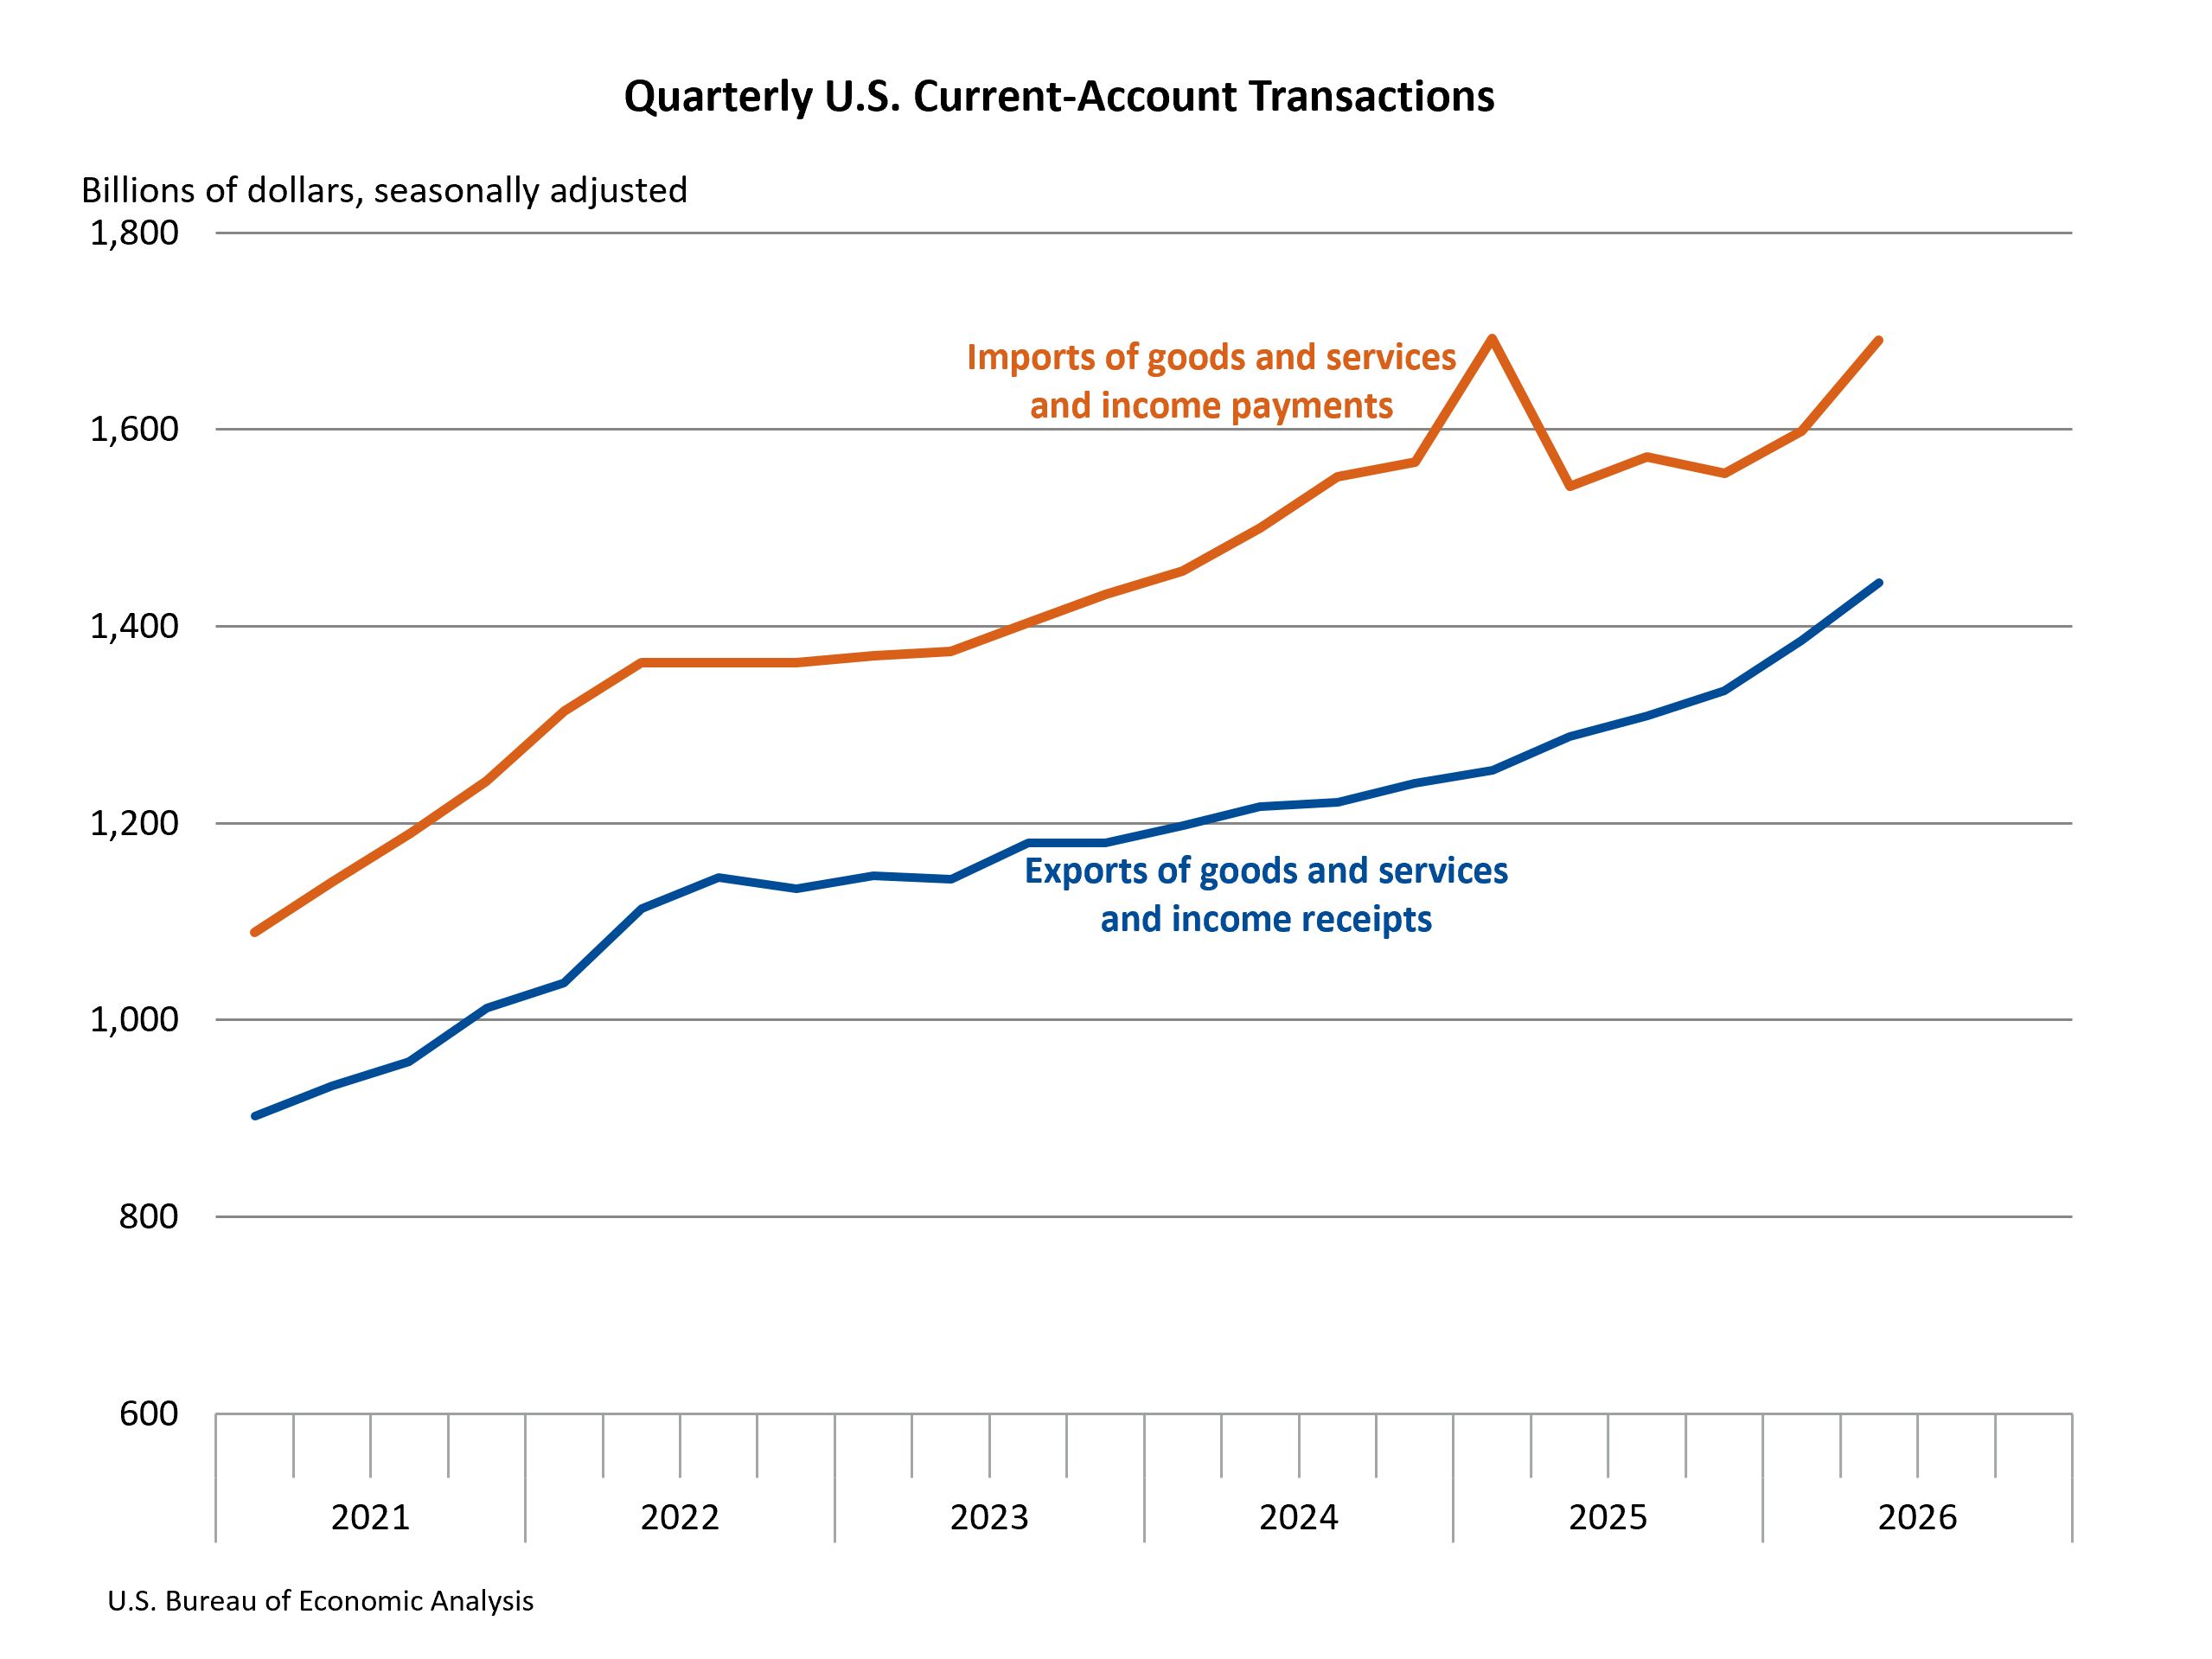
The financial account, which tracks the international movement of financial assets and liabilities, presented a significant net outflow of $369.7 billion in the second quarter. This figure signifies that, on balance, U.S. residents borrowed more from foreign residents than they lent to them. The transactions during this period led to an increase in U.S. residents’ holdings of foreign financial assets by $663.3 billion. Concurrently, U.S. liabilities to foreign residents—essentially, the amount of money foreigners invested in the U.S. or U.S. entities borrowed from abroad—surged by $978.9 billion. This substantial increase in liabilities further underscores the net borrowing position of the U.S. economy in its international financial dealings.
Net International Investment Position: A Growing Debt Burden
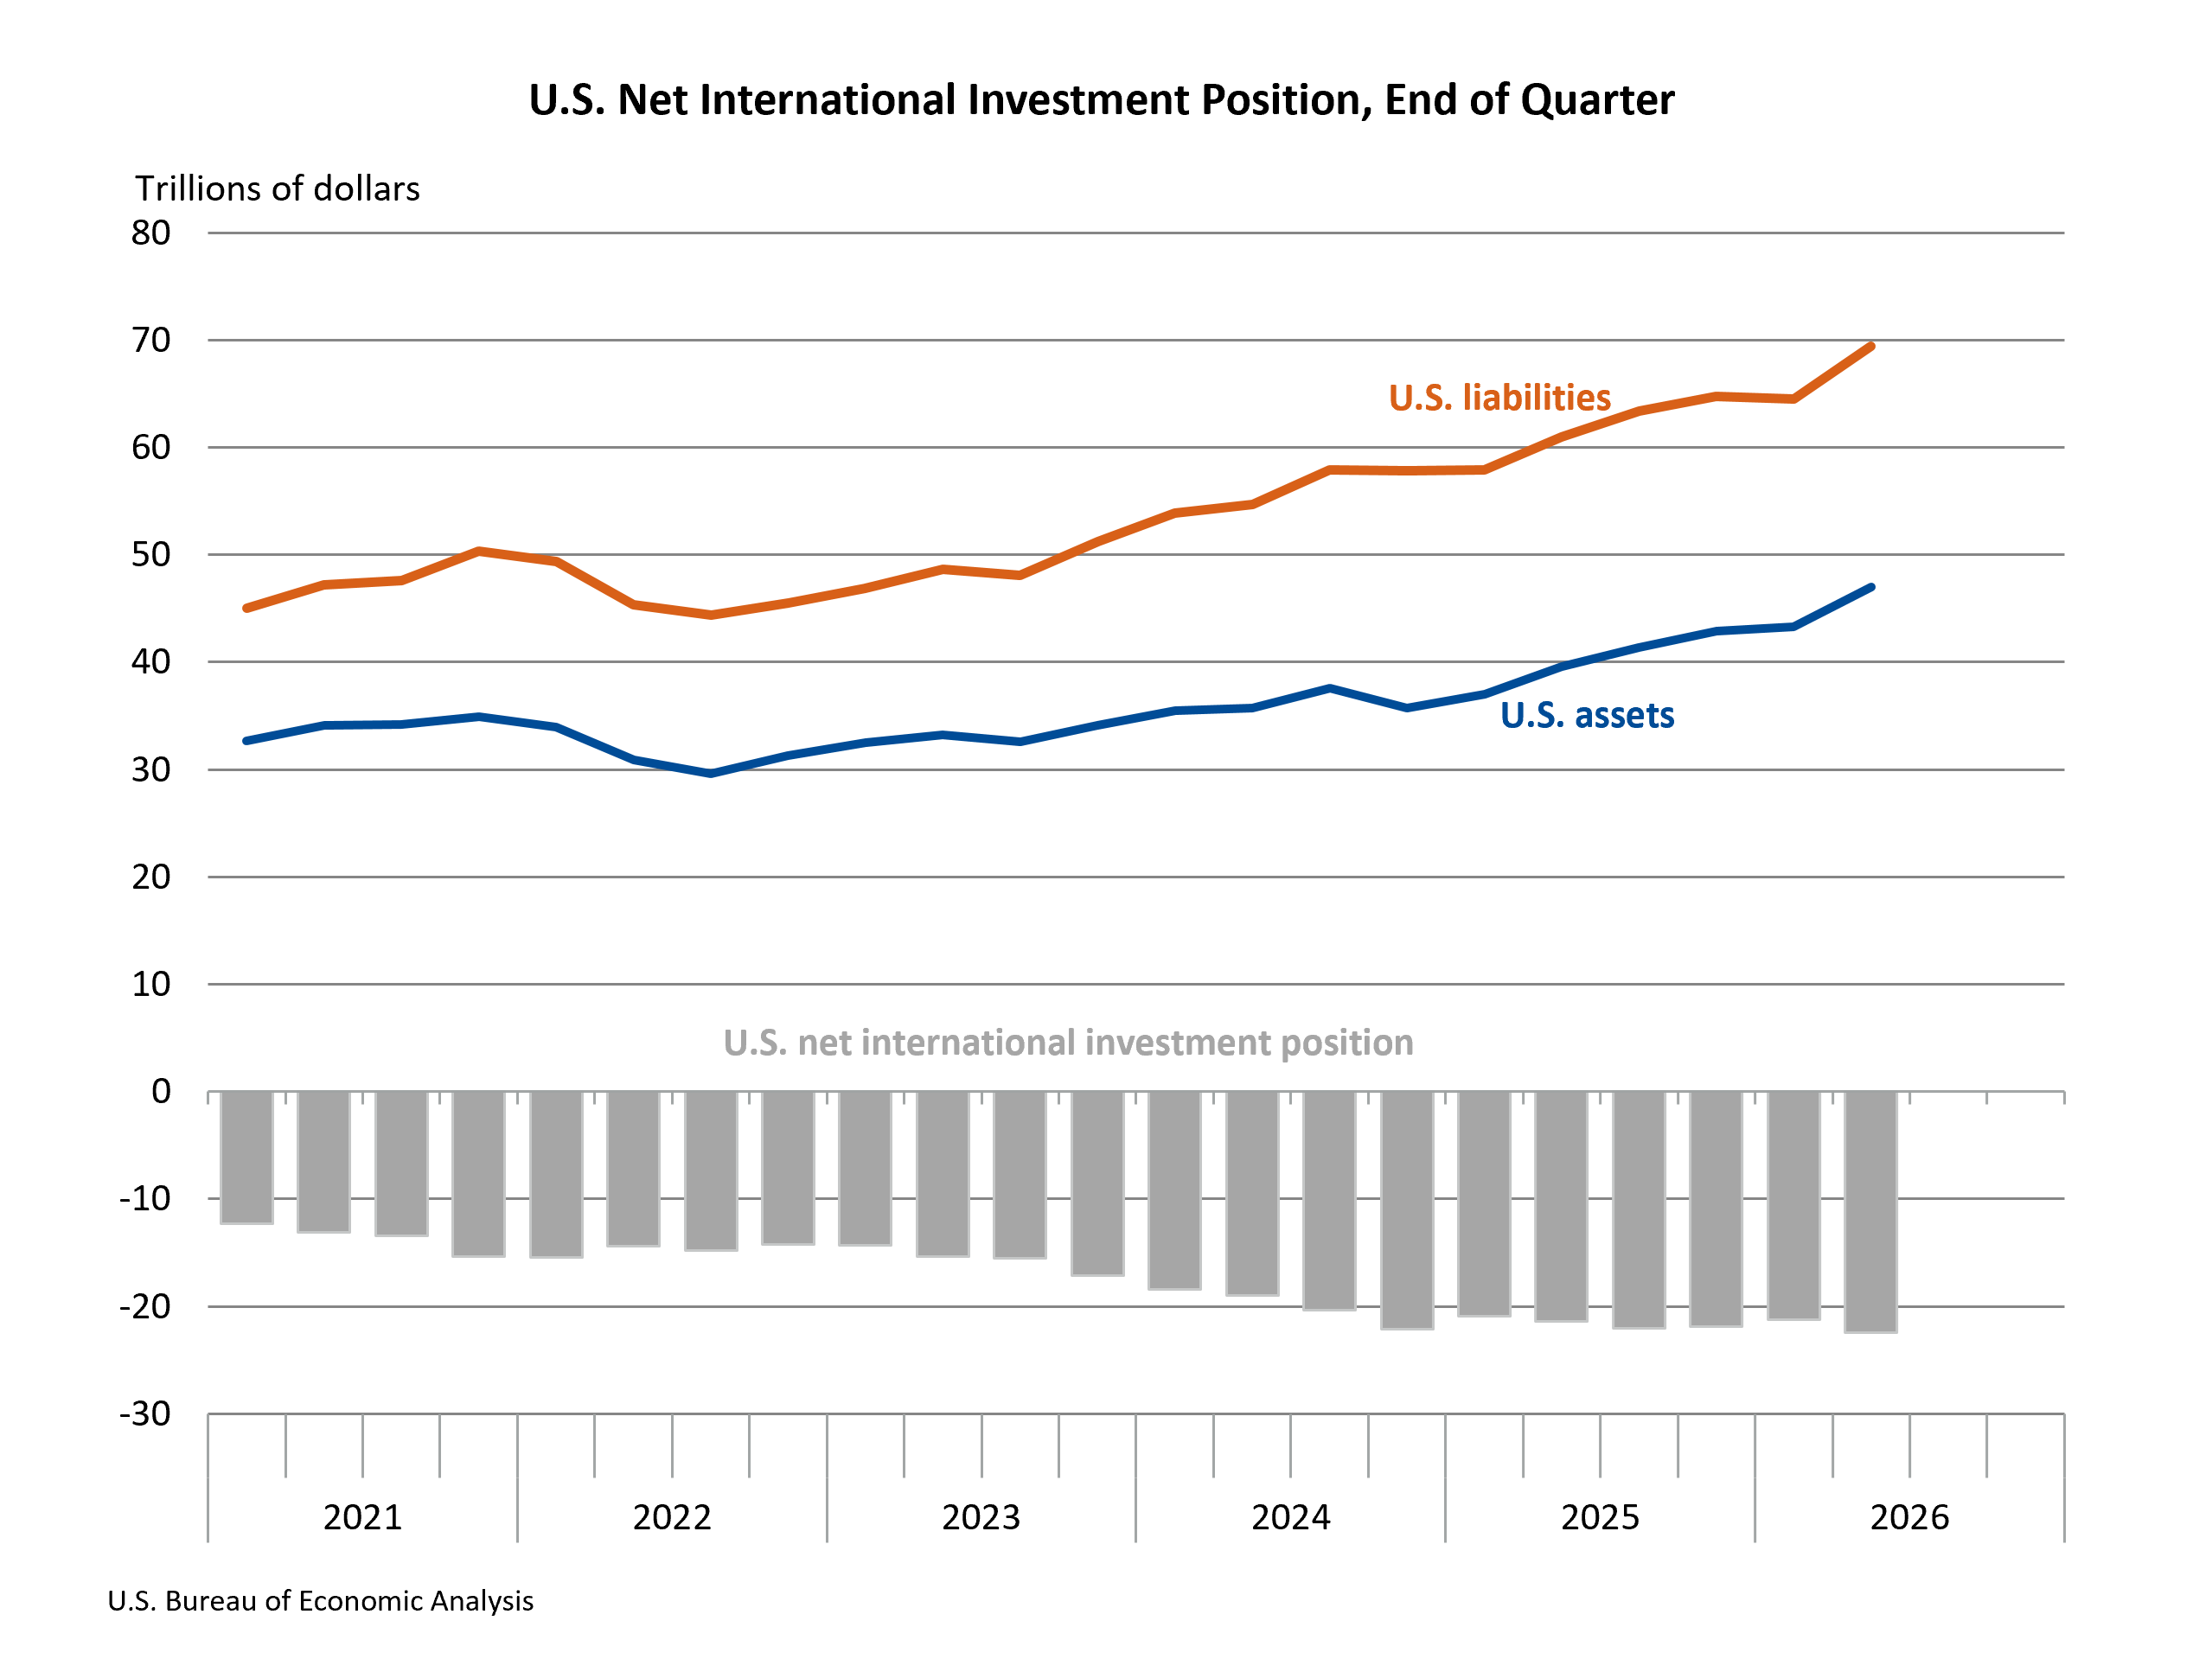
The cumulative effect of these international transactions is reflected in the U.S. net international investment position. At the close of the second quarter of 2026, this position, which represents the difference between U.S. residents’ foreign financial assets and liabilities, stood at a deficit of $22.42 trillion. This represents a worsening of the nation’s net financial standing with the rest of the world.
U.S. assets held abroad totaled $46.97 trillion, while U.S. liabilities to foreign entities amounted to $69.39 trillion. Compared to the end of the first quarter of 2026, when the net investment position was a revised -$21.27 trillion, the U.S. has accumulated further external debt.
Dynamics of Assets and Liabilities
The expansion of U.S. assets held abroad during the second quarter was substantial, increasing by $3.72 trillion. This growth was broad-based, with increases across most major investment categories, excluding reserve assets. The primary drivers of this increase were price changes, which accounted for $3.03 trillion, and financial transactions, which added $663.3 billion. This suggests that the value of U.S. investments overseas appreciated significantly, alongside new investments made by U.S. entities abroad.
Conversely, U.S. liabilities to foreign residents also saw a considerable rise, growing by $4.87 trillion in the same quarter. This increase was also widespread, with gains observed in all major investment categories, particularly in portfolio investment. Portfolio investment typically involves the purchase of foreign stocks and bonds. The overall increase in liabilities was driven by price changes, which contributed $3.95 trillion, and financial transactions, which added $978.9 billion. This indicates that foreign investments in the U.S. also appreciated in value, and foreign entities made substantial new investments in the United States.
The fact that liabilities grew at a faster pace than assets, both in absolute terms and in terms of new financial transactions, contributed to the widening net international investment position deficit.
First Quarter Revisions: A Closer Look at Previous Trends
The U.S. Bureau of Economic Analysis also provided revised estimates for the first quarter of 2026, offering a more precise picture of the preceding period. The current-account balance for the first quarter was revised upwards to a deficit of $212.6 billion, from preliminary estimates of -$226.8 billion. This revision was primarily driven by an improvement in the secondary income balance, which narrowed to a deficit of $38.0 billion from a preliminary estimate of -$47.8 billion. The services balance also saw a slight upward revision, reflecting stronger net service exports.
The net financial-account transactions for the first quarter were also significantly revised, showing a larger net borrowing from foreign residents. The revised estimate for net financial-account transactions was -$295.2 billion, a substantial increase from the preliminary estimate of -$209.0 billion. This revision suggests that international financial flows in the first quarter were more heavily skewed towards foreign investment in the U.S. than initially reported.
The U.S. net international investment position at the end of the first quarter remained unchanged at -$21.27 trillion in the revised estimates, with minor adjustments to the preliminary figures for U.S. assets and liabilities.
Broader Economic Context and Potential Implications
The widening current-account deficit in the second quarter of 2026 occurs against a backdrop of global economic activity. While the specific global economic conditions influencing these figures are not detailed in the provided data, generally, a growing current-account deficit can have several implications for an economy.
A sustained widening of the deficit can signal increasing reliance on foreign capital to finance domestic consumption and investment. While this can facilitate growth in the short term, it can also lead to a buildup of external debt, which may require higher interest payments in the future and could make the economy more vulnerable to shifts in global financial sentiment.
From a trade perspective, the expanding deficit on goods suggests that domestic demand for imported products remains strong, potentially outpacing the competitiveness of U.S. exports. This dynamic can put pressure on domestic industries and employment in sectors facing significant import competition.
The data also highlights the importance of income flows in the current account. A reduction in the deficit on primary income, as seen in the second quarter, can be a positive sign, indicating a growing return on U.S. investments abroad. However, the overall deficit on goods continues to be the dominant factor.
Analysis of Financial Account Activity
The substantial net financial-account deficit in the second quarter, driven by a significant increase in U.S. liabilities, suggests a strong inflow of foreign investment into the United States. This could be a reflection of investor confidence in the U.S. economy, attractive investment opportunities, or a combination of factors. However, it also means that a larger portion of the nation’s assets are now foreign-owned or financed by foreign debt.
The significant increase in both U.S. assets and liabilities due to price changes is also noteworthy. This indicates that market valuations of international investments, both domestic and foreign, played a considerable role in the quarter’s financial account dynamics. Fluctuations in global asset prices can significantly impact the net international investment position, even without corresponding changes in the underlying volume of transactions.
Looking Ahead: Future Releases and Data Archive
The U.S. Bureau of Economic Analysis regularly updates these statistics, providing crucial insights into the nation’s economic interactions with the rest of the world. The next release, scheduled for December 18, 2026, will provide the third-quarter 2026 data for International Transactions Accounts (ITA) and International Investment Position (IIP). This upcoming release will supersede the second-quarter data and will offer further insights into the evolving economic landscape.
For those seeking historical data and more granular details, the BEA’s Interactive Data Application and Data Archive offer extensive resources. These platforms allow users to explore past trends and conduct in-depth analysis of international economic transactions and investment positions. The detailed information available through these resources is vital for economists, policymakers, and businesses seeking to understand the complex dynamics of the U.S. economy in a globalized world. The ongoing monitoring of these indicators remains critical for assessing the nation’s economic health and its position in the international financial system.