Lana Rhoades
The regulatory landscape for digital commerce in California is undergoing a significant transformation as the state prepares to integrate Software as a Service (SaaS) and other digital products into its taxable base. Effective January 1, 2027, the California Department of Tax and Fee Administration (CDTFA) will begin taxing qualifying digital products, a move that marks one of the most substantial shifts in the state’s tax code since the implementation of the Marketplace Facilitator Act. For businesses operating within the state, particularly those utilizing quarterly filing schedules, the transition requires a rigorous approach to data management and a clear understanding of the CDTFA’s evolving online systems.
This shift comes at a time when California is looking to modernize its revenue streams to reflect a modern economy dominated by remote access and digital subscriptions. Historically, California was one of the few major economies that did not broadly tax SaaS, provided no tangible personal property was transferred. The upcoming 2027 mandate closes this gap, bringing the "Golden State" in line with dozens of other jurisdictions that have already moved toward taxing the digital economy. For compliance officers and business owners, the current challenge lies in reconciling existing sales data with the CDTFA’s reporting requirements while preparing for the increased complexity of digital product taxation.
The Legislative Context and the 2027 Digital Mandate
The decision to tax digital products is the result of years of legislative debate regarding the "erosion" of the traditional sales tax base. As consumers moved from buying physical software discs to subscribing to cloud-based platforms, state tax revenues saw a proportional decline in certain sectors. The Jan. 1, 2027, start date provides a buffer for businesses to update their accounting software and tax engines, but the complexity of "qualifying digital products" means that the preparation phase must begin immediately.
Under the new guidelines, SaaS subscriptions accessed remotely will be subject to state and district taxes. This includes not only traditional business software but also digital audio-visual works and other electronically transferred products. The CDTFA has indicated that the determination of taxability will hinge on the location of the benefit received, adding a layer of "nexus" complexity for businesses with a distributed user base. Economic analysts suggest that this move could generate upwards of $1 billion in annual revenue for the state, helping to stabilize budget fluctuations caused by shifts in consumer behavior.
Chronology of California’s Sales Tax Evolution
To understand the current filing requirements, it is essential to view them through the lens of California’s tax history:
- Pre-2018 (The Physical Presence Era): Tax collection was primarily required only for businesses with a physical office, warehouse, or employees in the state.
- June 2018 (The Wayfair Decision): The U.S. Supreme Court ruled in South Dakota v. Wayfair, Inc. that states could collect sales tax from out-of-state sellers based on economic activity (nexus), rather than just physical presence.
- October 2019 (Marketplace Facilitator Act): California shifted the burden of tax collection from individual third-party sellers to large platforms like Amazon and eBay.
- 2020–2025 (The E-commerce Surge): Rapid growth in online retail led to more frequent filing status changes for small and medium-sized enterprises (SMEs).
- January 2027 (The Digital Product Threshold): The inclusion of SaaS and digital goods into the taxable pool.
Mastering the CDTFA Filing Process
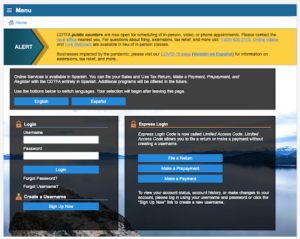
For businesses currently navigating the quarterly filing cycle, the CDTFA Online Services portal remains the primary interface for compliance. The process of moving information from an internal "expected state report" into the official government system is a critical juncture where many errors occur. Accuracy at this stage is paramount, as the CDTFA utilizes automated auditing tools to flag discrepancies between reported gross sales and bank records.
Preparation and Documentation
Before initiating a return, filers must gather comprehensive data points including gross sales, purchases subject to use tax, and a detailed breakdown of district taxes. The CDTFA assigns filing frequencies—monthly, quarterly, or yearly—based on a business’s reported sales volume. It is a common misconception that filing frequencies are static; the CDTFA frequently adjusts these based on a business’s annual revenue trends.
Reporting Gross Sales and Deductions
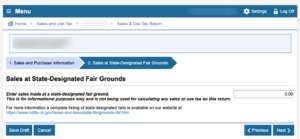
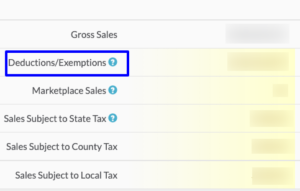
The filing begins with the entry of "Total Sales," which must encompass every transaction, including those that are non-taxable or handled by marketplace facilitators. Following this, the filer must navigate the "Deductions and Exemptions" section. This is often where the most significant filing errors occur. Common deductions include:
- Marketplace Facilitator Sales: If a platform like Amazon has already collected and remitted the tax, the seller must deduct these sales to avoid double taxation.
- Shipping Charges: In California, shipping can be exempt if it is clearly stated as a separate charge and represents the actual cost of delivery, but it becomes taxable if combined with "handling" fees.
- Returned Merchandise: Credits for returned goods that were previously taxed must be meticulously recorded.
The Role of Supplemental Schedules: A, B, and C
California’s tax structure is notoriously granular, requiring sellers to allocate taxes to specific jurisdictions. This is handled through three primary schedules:
Schedule A (District Tax)
This schedule is used to report taxes for specific cities and counties that have voter-approved "add-on" rates. Because these rates can change quarterly, filers must ensure they are using the correct rate for the specific date of the transaction. If a district rate changed mid-quarter, the CDTFA system may require two separate entries for the same location.
Schedule B (County Tax)
Schedule B is utilized for allocating county-wide pools. This typically applies to sales made into counties where the business does not have a physical footprint but has established economic nexus. It ensures that the 1% local tax is distributed correctly to the jurisdictions where the goods were consumed.
Schedule C (Physical Locations)
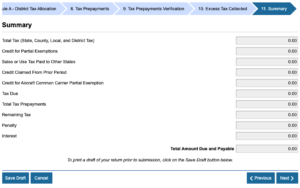
For businesses with brick-and-mortar stores or registered warehouses within California, Schedule C is mandatory. It links taxable sales to specific street addresses. This ensures that the local portion of the sales tax is returned to the specific municipality where the business operates.
Data-Driven Insights and Economic Impact
Recent data from the CDTFA suggests that sales tax remains the second-largest source of revenue for the state’s General Fund, trailing only the personal income tax. In the 2023-2024 fiscal year, sales and use taxes accounted for approximately $30 billion in state revenue. The inclusion of SaaS in 2027 is expected to increase this figure by 3.5% to 5%.
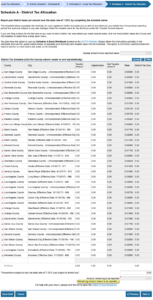
However, the complexity of this system places a heavy burden on the tech sector. A survey of California-based SaaS startups indicated that 64% of founders are concerned about the "compliance drag" associated with the new digital tax. "The challenge isn’t just the tax itself," noted one Silicon Valley CFO. "It’s the administrative overhead of tracking the exact location of every user to satisfy district-level reporting."
Official Responses and Expert Analysis
The CDTFA has consistently emphasized that its online portal is designed to minimize errors through built-in logic checks. However, tax experts warn that these checks are only as good as the data entered. Rounding issues remain a persistent thorn in the side of automated filing. While the CDTFA generally allows for small variances due to rounding, a discrepancy of more than a few dollars can trigger an "Error of Fact" notice, potentially leading to an audit.
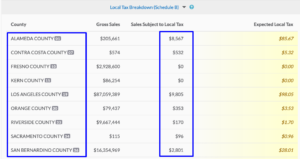
Industry analysts suggest that the 2027 change will lead to a surge in the adoption of automated tax compliance software. By integrating sales platforms directly with tax engines, businesses can automate the population of Schedules A, B, and C, significantly reducing the risk of human error. Furthermore, as the state moves toward taxing digital products, the definition of "nexus" is expected to be challenged in court, as businesses argue over what constitutes "using" software within a specific California district.
Broader Implications for the Future of Taxation
California’s move toward taxing digital products is part of a broader national trend. As of 2026, over 30 states have already implemented some form of SaaS taxation. California’s entry into this group is significant because of the sheer volume of software companies headquartered within its borders.
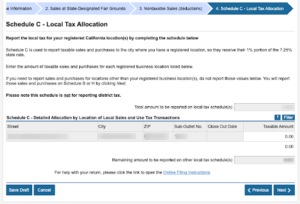
The implications extend beyond just revenue. This shift reflects a fundamental change in how the law views "property." By taxing a remote subscription as if it were a physical good, the state is effectively codifying the idea that digital access is a commodity. For the quarterly filer, this means that the "Gross Sales" line on their return will soon include a much wider array of revenue streams, necessitating a more sophisticated approach to bookkeeping and a tighter relationship with tax professionals.
As the Jan. 1, 2027, deadline approaches, the CDTFA is expected to release more specific "Industry Guides" to help SaaS providers distinguish between taxable software and non-taxable professional services (such as consulting or data analysis). For now, businesses must remain diligent with their quarterly filings, ensuring that every deduction is backed by documentation and that every district allocation is precise. In the world of California sales tax, accuracy is not just a goal—it is a requirement for survival in an increasingly complex digital economy.