Lana Rhoades
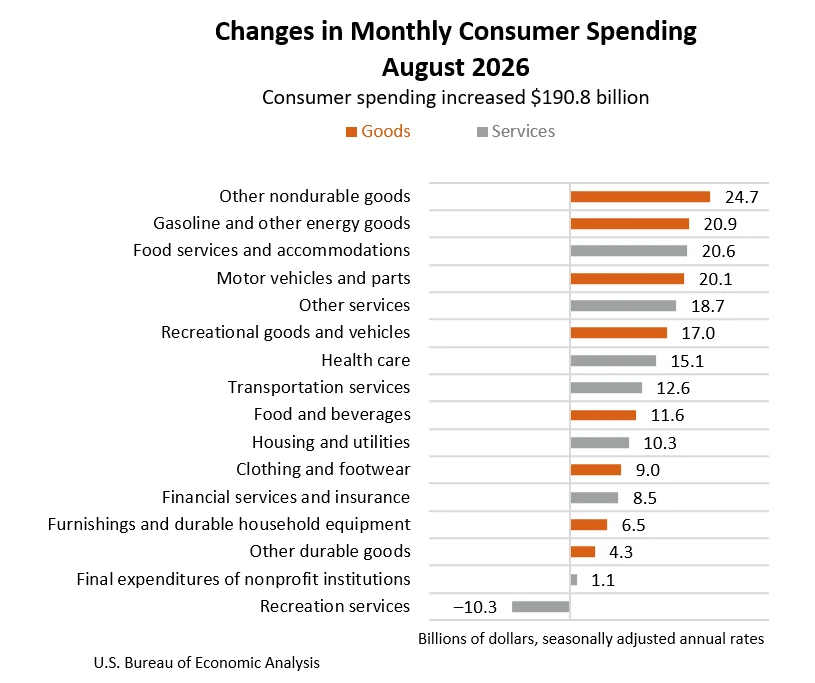
Personal income experienced a modest increase of $66.6 billion, representing a 0.2 percent rise on a monthly basis in August, according to the latest estimates released by the U.S. Bureau of Economic Analysis (BEA). This growth in overall income was accompanied by a more significant uptick in disposable personal income (DPI) – the amount of income remaining after taxes – which climbed by $68.6 billion, or 0.3 percent. Concurrently, personal consumption expenditures (PCE), a key measure of consumer spending, surged by $190.8 billion, marking a substantial 0.9 percent increase. These figures paint a picture of a U.S. economy where individuals are earning slightly more, have more to spend after taxes, and are actively increasing their consumption, though the pace of spending growth significantly outstrips income gains.
The BEA’s report, released on [Insert Date of Release, e.g., September 29, 2026], provides a critical snapshot of the nation’s economic health, offering insights into the financial well-being of households and the momentum of consumer-driven economic activity. The divergence between income growth and spending growth suggests a potential drawdown of savings or increased reliance on credit by consumers to fuel their expenditures.
Key Indicators: Income, Spending, and Savings
The $66.6 billion increase in current-dollar personal income for August was primarily driven by advancements in compensation, which includes wages, salaries, and benefits, as well as an increase in government social benefits. These contributions indicate a mixed economic landscape, with both labor market improvements and government support playing roles in bolstering household incomes.
Disposable personal income (DPI), a more direct measure of consumers’ ability to spend or save, saw a slightly stronger percentage increase at 0.3 percent. This suggests that while overall income grew, the net effect after accounting for personal current taxes was a marginally more robust gain in available funds for households.
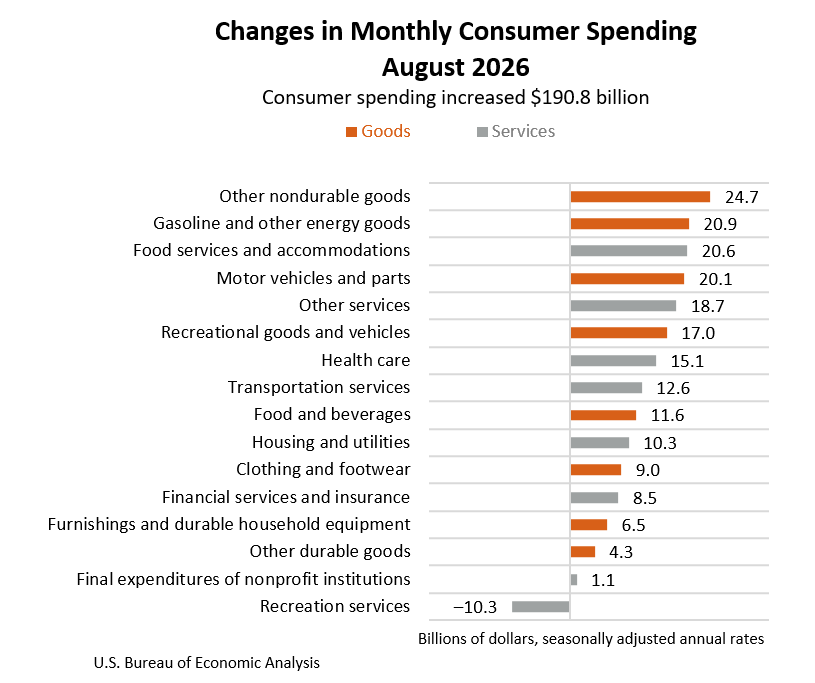
The most striking figure in the report is the 0.9 percent leap in personal consumption expenditures (PCE). This substantial increase in consumer spending, totaling $190.8 billion, outpaced the growth in both personal income and disposable personal income. This acceleration in spending is a significant driver of economic activity, but its rapid ascent relative to income growth raises questions about its sustainability and the underlying financial health of consumers.
Personal outlays, which encompass PCE along with personal interest payments and personal current transfer payments, also saw a considerable rise, increasing by $190.7 billion in August. This aligns closely with the surge in PCE, reinforcing the strong consumer spending trend observed during the month.
The consequence of this accelerated spending relative to income is reflected in personal saving. Personal saving for August stood at $990.2 billion, a notable sum but one that implies a declining savings rate. The personal saving rate, calculated as personal saving as a percentage of DPI, dipped to 4.1 percent. This rate is down from previous months and indicates that consumers are allocating a larger portion of their disposable income towards spending rather than setting it aside. A lower saving rate can signal increased consumer confidence and a willingness to spend, but it can also be a sign of financial strain if individuals are dipping into savings to cover essential expenses or accumulating debt.
Breakdown of Consumer Spending: Goods vs. Services
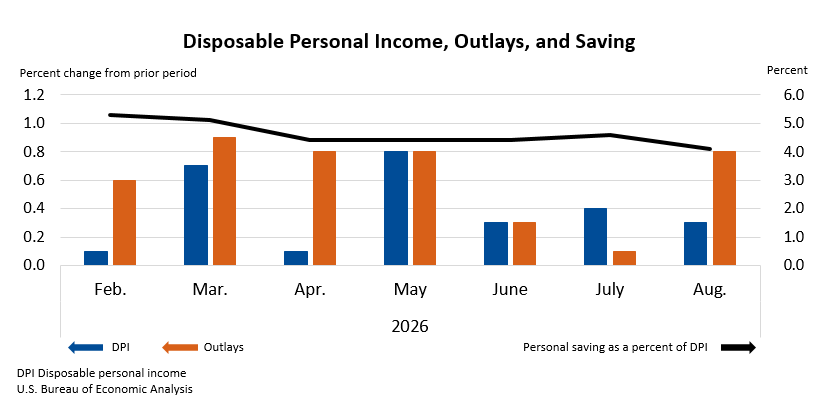
The $190.8 billion increase in current-dollar PCE was bifurcated between spending on goods and spending on services. Spending on goods saw a significant jump of $114.1 billion, while spending on services increased by $76.7 billion. This indicates robust demand across both categories of consumption. The strong performance in goods spending could be attributed to a variety of factors, including the purchase of durable goods, seasonal sales, or pent-up demand for certain products. The continued strength in services spending, which had previously been a laggard during periods of pandemic-related restrictions, suggests a sustained return to pre-pandemic consumption patterns for activities like dining out, travel, and entertainment.
Real Consumption and Inflationary Dynamics
When adjusted for inflation, real personal consumption expenditures (real PCE) also demonstrated a healthy increase, rising by $92.8 billion, or 0.6 percent, in August. This indicates that the rise in consumer spending was not solely due to price increases, but also reflected a genuine increase in the volume of goods and services consumed. The fact that real PCE growth outpaced the growth in real DPI (which remained flat at 0.0 percent for the month) further underscores the trend of consumers drawing down savings or increasing leverage to finance their purchases.
However, the BEA report also highlighted persistent inflationary pressures. The overall PCE price index rose by 0.3 percent in August. More critically, the core PCE price index, which excludes volatile food and energy prices and is closely watched by the Federal Reserve as an indicator of underlying inflation trends, increased by 0.2 percent. While these monthly increases might seem modest, they contribute to an ongoing upward trajectory in prices.
On a year-over-year basis, the PCE price index increased by 3.4 percent in August, a figure that remains above the Federal Reserve’s target inflation rate of 2 percent. The core PCE price index also showed a significant annual increase of 3.0 percent. These figures suggest that while inflation may be moderating from its peak levels seen in previous years, it remains a persistent concern for policymakers and consumers alike. The continued rise in the cost of goods and services can erode the purchasing power of incomes, potentially counteracting some of the gains in nominal income and leading to a squeeze on household budgets.
Context and Background: A Shifting Economic Landscape
The August economic data emerges against a backdrop of a complex and evolving global and domestic economic environment. In the preceding months, the U.S. economy had shown resilience, with a generally strong labor market and steady, albeit sometimes uneven, consumer spending. However, concerns about inflation, rising interest rates, and geopolitical uncertainties have continued to cast a shadow.
The Federal Reserve has been actively engaged in monetary policy tightening, aiming to curb inflation by increasing interest rates. This policy stance aims to cool down demand across the economy, including consumer spending. The data released for August suggests that while consumers are still spending robustly, the impact of higher interest rates may begin to manifest in the coming months through reduced borrowing and potentially slower spending growth.
The BEA’s revisions to compensation data, incorporating first-quarter wage and salary data from the Bureau of Labor Statistics (BLS) Quarterly Census of Employment and Wages program, and updated monthly data from the BLS CES program for April through July, highlight the dynamic nature of economic data collection. These revisions ensure that the reported figures are as accurate as possible, reflecting the most up-to-date information on employment and wages. Similarly, updates to Medicaid benefit data from the Centers for Medicare & Medicaid Services contribute to the accuracy of government social benefit figures.
Analysis and Implications: A Balancing Act for Consumers and Policymakers
The August report presents a nuanced economic picture. On one hand, the increase in personal income and the surge in consumer spending are positive indicators of economic activity and consumer confidence. This robust spending is crucial for businesses and economic growth. The strong performance in both goods and services consumption suggests a broad-based demand across the economy.
On the other hand, the widening gap between income growth and spending growth, coupled with the persistent inflation figures, presents challenges. The declining personal saving rate could signal that consumers are becoming more stretched financially, potentially leading to increased reliance on credit and a greater vulnerability to economic downturns. If inflation continues to outpace wage growth, consumers may find their purchasing power diminishing, forcing them to make difficult choices about their spending.
For policymakers, the data presents a delicate balancing act. The Federal Reserve will be closely scrutinizing these figures as they consider future interest rate decisions. While the robust consumer spending might suggest that the economy can withstand further tightening, the persistent inflation necessitates continued vigilance. The core PCE price index, in particular, will remain a key focus.
Businesses may find themselves in a favorable short-term environment with strong consumer demand, but they will also need to contend with rising input costs due to inflation and the potential for a slowdown in consumer spending if interest rates continue to rise or if household savings are further depleted.
The upcoming release of September data will be crucial in determining whether the trends observed in August represent a sustained pattern or a temporary fluctuation. The BEA’s next release, scheduled for October 29, 2026, will provide insights into September’s personal income and outlays, offering a clearer view of the ongoing economic trajectory.
Technical Notes and Data Revisions
The BEA report also includes technical notes that provide important context for interpreting the data. These notes detail the methodologies used in calculating personal income and outlays, as well as the implications of data revisions. The incorporation of updated wage and salary data from the BLS, for instance, reflects the ongoing effort to refine the accuracy of economic statistics. Such revisions are a standard part of economic reporting and ensure that the data remains a reliable guide to economic conditions.
The BEA also provides access to extensive historical data through its Interactive Data Application, allowing users to explore trends and conduct in-depth analysis. The linked data tables offer detailed breakdowns of personal income, its disposition, and price indices, empowering researchers, analysts, and the public with a comprehensive understanding of the U.S. economy.
In summary, the August economic data reveals a U.S. economy characterized by strong consumer spending fueled by modest income growth and a declining savings rate, all occurring within an environment of persistent inflationary pressures. The interplay of these factors will continue to shape economic policy and consumer behavior in the months ahead.