Pevita Pearce
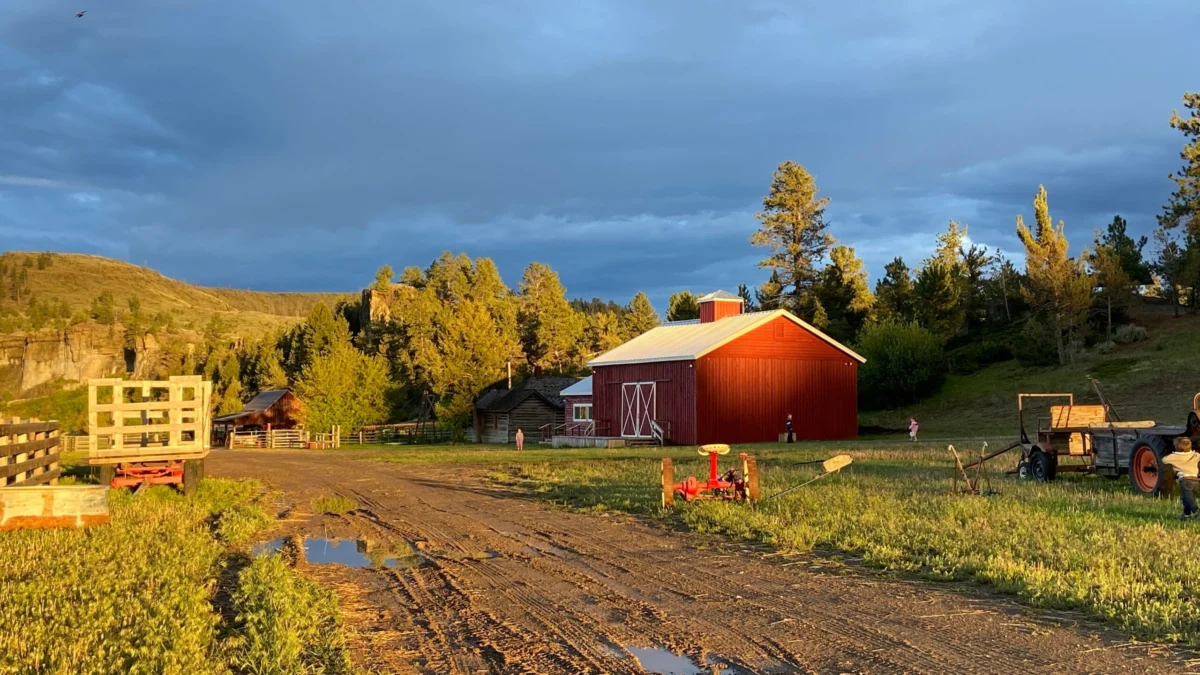
Taxpayers who sell or exchange qualified farmland to active farmers can elect to pay the tax on the gain in four equal installments under proposed regulations released by the Treasury Department and the IRS on Monday. This initiative, stemming from Section 1062 of the Internal Revenue Code, provides a crucial financial relief mechanism for agricultural landowners transitioning their properties, particularly when the sale is to a new generation of farmers or those expanding their operations. The provision aims to foster the continued use of farmland for agricultural purposes by alleviating the immediate tax burden that might otherwise deter such transactions.
The proposed regulations, officially published for public comment, outline the procedural and substantive requirements for taxpayers to utilize this installment payment option. This development is a direct result of legislative action, specifically the "One Big Beautiful Bill Act" (OBBBA), signed into law by President Donald Trump on July 4, 2025. Republicans have since rebranded this legislation as the "Working Families Tax Cuts," emphasizing its intended benefits for a broader segment of the population, including those within the agricultural sector. The inclusion of this farmland installment payment provision underscores a legislative focus on supporting agricultural continuity and the economic health of farming communities.
Background and Legislative Context
The enactment of Section 1062 of the Internal Revenue Code, as part of the broader OBBBA, marks a significant policy shift aimed at addressing the financial challenges associated with farmland succession and the transfer of agricultural operations. Historically, significant capital gains tax liability arising from the sale of appreciated farmland could present a substantial hurdle for both retiring farmers and new entrants seeking to acquire land. The immediate cash outflow required to settle these taxes could deplete a seller’s resources or make a purchase prohibitively expensive for a buyer, potentially leading to farmland being sold for non-agricultural development or falling into disuse.
The "Working Families Tax Cuts" legislation, therefore, seeks to mitigate these issues. The installment payment option for farmland sales to active farmers is a targeted measure designed to preserve agricultural land in active use. By allowing the tax liability to be spread over four years, the law provides sellers with greater financial flexibility and encourages transactions that benefit the agricultural economy. The July 4, 2025, effective date indicates a deliberate legislative intent to implement these provisions in a timely manner, aligning with the agricultural calendar and the typical transaction cycles within the sector.
Key Provisions of the Proposed Regulations
The proposed regulations provide a detailed framework for taxpayers to elect and utilize the installment payment option. To qualify for this benefit, several criteria must be met by both the farmland and the buyer.
Farmland Qualification Criteria
- Location: The farmland must be real property situated within the United States. This geographical limitation ensures that the provision supports domestic agricultural production.
- Prior Use: For substantially all of the 10 years preceding the sale or exchange, the taxpayer must have used the land for farming purposes. Alternatively, the land could have been leased to a qualified farmer for farming during this period. This requirement ensures that the provision is directed towards genuine agricultural land with a demonstrated history of farming.
- Future Use Restriction: Following the sale or exchange, the property must be subject to a legally enforceable restriction that prohibits its use for anything other than farming for a period of 10 years. This restriction is a critical element, guaranteeing that the farmland remains dedicated to agricultural purposes and does not transition to other uses, thereby fulfilling the legislative intent of preserving agricultural land.
Buyer Qualification Criteria
- Active Farmer: The buyer must be an individual who is actively engaged in farming. This ensures that the farmland is transferred to those who will continue to cultivate it and contribute to the agricultural sector. The definition of "actively engaged in farming" will likely be further clarified within the final regulations, but it implies a direct and substantial involvement in agricultural production.
Election and Payment Schedule
Taxpayers who meet these qualifications can elect to pay the tax attributable to the gain from the sale or exchange in four equal annual installments. Each installment will represent 25% of the total applicable tax liability.
- First Payment: The initial installment payment is generally due on the standard due date for the taxpayer’s federal income tax return for the year in which the sale or exchange occurred. This date is typically April 15 for calendar-year taxpayers, though extensions for filing the return do not extend the payment deadline for this first installment.
- Subsequent Payments: Each of the remaining three installment payments is generally due on the regular federal income tax return due date for each of the subsequent three taxable years. This provides a predictable and manageable payment schedule over a four-year period.
Addressing Complex Transaction Structures
The proposed regulations also extend to more complex ownership structures, ensuring that the benefits of Section 1062 are accessible to a wider range of agricultural landowners.
- Partnerships and S Corporations: For sales or exchanges conducted by partnerships or S corporations, the election to pay in installments is generally made by individual partners or shareholders with respect to their respective shares of the gain. This means that the tax burden and the installment payment option flow through to the ultimate owners.
- Trusts and Estates: Similar rules apply when gain passes through a trust or estate to a beneficiary. The beneficiary would typically make their own election concerning their portion of the gain. This ensures that the installment payment option is available at the individual level, even when the property is held in trust or managed by an estate.
Flexibility for Temporary Disruption in Farming Use
Recognizing that agricultural operations can be subject to factors beyond a taxpayer’s direct control, the proposed rules offer flexibility regarding the 10-year prior farming-use requirement. Taxpayers may still qualify for the election in certain circumstances where farmland was temporarily out of production. These include:
- Government Programs: If the land was temporarily removed from production as part of a federal or state agricultural program, such as conservation reserves or crop idling programs, this period is generally considered acceptable.
- Recognized Farming Practices: Short periods of non-use that are part of standard or recognized farming practices, such as fallow periods or crop rotation cycles, are also likely to be accommodated.
- Events Beyond Taxpayer Control: Circumstances such as natural disasters (floods, droughts, fires), or other events that were unforeseeable and beyond the taxpayer’s control, which temporarily interrupted farming use, may also be taken into account. This provision acknowledges the inherent risks and unpredictable nature of agricultural endeavors.
Public Comment Period and Next Steps
The Treasury Department and the IRS have opened a public comment period for the proposed regulations. This is a standard procedure designed to solicit feedback from stakeholders, including farmers, tax professionals, agricultural organizations, and legal experts. The agencies are inviting written or electronic comments to be submitted by November 30, 2026. The specific instructions for submitting comments are detailed within the proposed regulations themselves, which are accessible through the Federal Register. This feedback will be crucial in refining the final regulations to ensure they are practical, effective, and achieve the intended legislative goals.
Implications for the Agricultural Sector
The introduction of this installment payment option for farmland sales to active farmers is poised to have several significant implications for the agricultural sector:
- Facilitating Generational Transfer: This provision is expected to significantly ease the transition of farms from one generation to the next. Many farmers nearing retirement may have substantial equity tied up in their land. The ability to defer a large portion of the capital gains tax can provide them with more liquidity for retirement while enabling their children or other successors to acquire the farm without being immediately burdened by a massive tax bill.
- Supporting New Farmers: Aspiring farmers often face significant capital barriers, with land acquisition being the most substantial. By making farmland more accessible through installment payments on the seller’s tax liability, the cost of entry for new farmers can be effectively reduced. This can foster greater innovation and entrepreneurship within the agricultural industry.
- Preserving Farmland: The requirement for the buyer to be an active farmer and the future use restriction are designed to combat urban sprawl and the conversion of agricultural land to non-farming purposes. By keeping farmland in production, the policy supports food security, rural economies, and the environmental benefits associated with agricultural landscapes.
- Economic Stability: For rural communities, the continuity of farming operations is vital for economic stability. This provision can help maintain the viability of these communities by supporting the transfer and continuation of agricultural businesses.
- Tax Planning Opportunities: Taxpayers and their advisors will need to carefully navigate the election process and understand the detailed requirements. Proper tax planning will be essential to ensure eligibility and to optimize the benefits of the installment payment option. The proposed regulations, once finalized, will provide the definitive guidance for this.
IRS CEO Frank Bisignano, in a statement released on September 28, emphasized the practical importance of this measure. "Farmers should have practical options when farmland is sold," Bisignano stated. "The Working Families Tax Cuts helps keep farmland in agricultural use by allowing eligible sellers to spread their tax payments over four years when qualifying property is sold to active farmers." This statement highlights the direct link between the tax policy and the overarching goal of agricultural land preservation and operational continuity.
Broader Economic and Social Context
The implementation of Section 1062 comes at a time when concerns about agricultural land availability, farmer demographics, and the future of food production are at the forefront of public and policy discussions. Data from the U.S. Department of Agriculture has consistently shown an aging farmer population, with many farmers nearing retirement age. Simultaneously, the cost of farmland has continued to rise in many regions, making it increasingly difficult for young and beginning farmers to enter the profession.
This legislative and regulatory response can be viewed as a proactive measure to address these demographic and economic trends. By providing a financial incentive for the transfer of farmland to active farmers, the government aims to ensure that land remains productive and that the agricultural sector can continue to thrive. The "Working Families Tax Cuts" moniker suggests a broader agenda of supporting economic well-being for families, with the agricultural provisions being a key component of that strategy.
The success of this initiative will depend on several factors, including the clarity and practicality of the final regulations, the responsiveness of the market to these new incentives, and the continued commitment to supporting the agricultural community. The public comment period will be a critical step in ensuring that the final rules are robust and effectively serve their intended purpose. The Treasury Department and IRS are seeking comprehensive feedback to address any potential ambiguities or unforeseen challenges.