Julia Chirkova
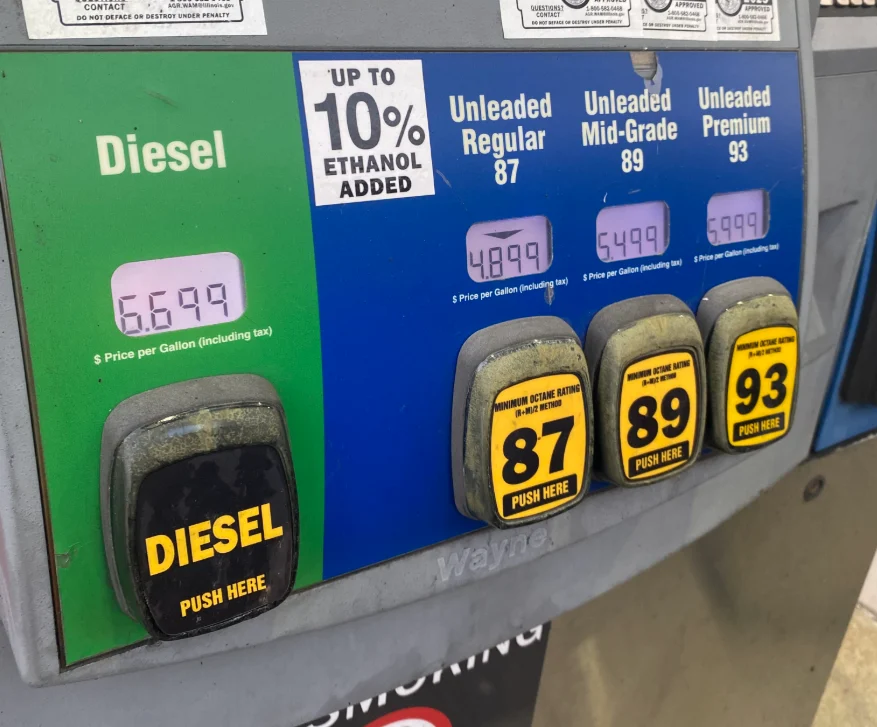
The Internal Revenue Service (IRS) announced late Wednesday evening a significant, temporary suspension of federal tax penalties associated with the sale or use of dyed diesel fuel on public highways across the nation. This measure, effective retroactively from October 1, 2026, and extending through December 31, 2026, provides immediate relief to a broad spectrum of diesel fuel users and sellers. The IRS clarified in an October 14 media release that this relief is applicable to "any person who sells dyed diesel fuel or uses dyed diesel fuel for highway use."
This pivotal decision stems directly from an executive order issued by President Donald Trump on October 5, 2026. The order’s primary objective is to alleviate the financial burden on diesel fuel consumers by enhancing the accessibility of dyed diesel for on-road purposes through the remainder of the calendar year. The executive order not only permits the temporary use of dyed diesel for highway applications but also defers associated federal taxes without imposing penalties or interest until year-end. Furthermore, it mandates that the Secretary of the Treasury, in collaboration with the Secretary of Defense, explore avenues to eliminate the obligation to pay these deferred taxes altogether.
Understanding Dyed Diesel Fuel and its Tax Implications
Ordinarily, dyed diesel fuel is exempt from federal excise taxes because it is intended for uses outside of public roadways. These exempt uses typically include agricultural operations, such as powering farm equipment, or for other off-road applications like construction machinery or heating systems. The distinctive red dye serves as a visual indicator for law enforcement to distinguish this tax-exempt fuel from on-road diesel, which is subject to taxation.
However, the tax regulations become applicable if dyed diesel fuel is sold for highway use or is actually utilized to power a vehicle on public roads. Under normal circumstances, the liability for this tax typically falls upon the retailer selling the dyed diesel fuel at the point of sale. If the fuel is not purchased at retail, the responsibility rests with the operator of the motor vehicle, for instance, if dyed diesel fuel is stored in a tank on a farm and subsequently used on a highway. The IRS has historically enforced these regulations to ensure tax compliance and prevent the diversion of tax-exempt fuel for taxable purposes.
IRS Suspends Enforcement and Collection Procedures
During this designated relief period, the IRS has pledged to suspend its standard collection and enforcement protocols concerning dyed diesel fuel used on highways. This includes a reassignment of all IRS fuel compliance officers to alternative duties, effectively halting any federal inspections specifically focused on the on-road usage of dyed fuel. Crucially, taxpayers are no longer required to maintain the meticulous records that would typically be necessary to substantiate their eligibility for tax relief during this period.
The tax agency has unequivocally stated that it will not impose any penalties related to the excise tax on dyed diesel fuel sold for or used in diesel-powered vehicles on highways nationwide. This broad relief encompasses penalties for failing to make timely semimonthly tax deposits, as well as penalties for inadequate record-keeping. Furthermore, sellers and distributors are explicitly absolved of any obligation to investigate or document the ultimate end-use of dyed fuel sold during the relief period, simplifying compliance for businesses in the fuel supply chain.
Navigating Potential Discrepancies and Future Guidance
Despite the sweeping nature of this relief, the IRS acknowledges that taxpayers who believe they qualify for this exemption but may receive a penalty notice are advised to follow the instructions provided within that notice. Alternatively, they are encouraged to contact the IRS directly for clarification and assistance. This proactive communication aims to address any potential administrative oversights and ensure that eligible taxpayers receive the intended benefits of the policy change.
The IRS has indicated its intention to issue further guidance to clarify the specifics of this tax postponement. This forthcoming guidance will also address how the relief will be applied to the Quarterly Federal Excise Tax Return (Form 720) and any other pertinent tax forms. The agency is also actively exploring additional measures, as directed by the executive order, to potentially eliminate the obligation to pay any taxes that have been deferred under this program.
State-Level Considerations and Broader Impact
It is imperative for taxpayers to understand that this relief is exclusively applicable to federal tax obligations. The IRS has reiterated that this initiative has no bearing on state fuel taxes and any associated penalties that individual states may impose on the use of dyed diesel fuel on their highways. While many states have independently enacted similar relief measures to align with the federal directive, this is not universally the case. Consequently, the IRS strongly urges taxpayers to consult with their respective state tax agencies for the most current and accurate guidance regarding state-level fuel tax relief.
The implications of this executive action and subsequent IRS announcement are multifaceted. For commercial truckers, agricultural businesses, and other heavy diesel users, the immediate effect is a reduction in operating costs and a simplification of compliance procedures for the remainder of 2026. By making dyed diesel a viable, penalty-free option for on-road use, the government aims to inject some economic stimulus into sectors heavily reliant on diesel fuel, potentially mitigating inflationary pressures and supporting businesses facing increased transportation expenses.
Background and Chronology of Events
The sequence of events leading to this announcement highlights a swift governmental response to perceived economic pressures. The initial executive order on October 5, 2026, signaled the administration’s intent to address rising diesel costs. This was followed by the IRS’s formal announcement of the penalty suspension on Wednesday evening, October 12, 2026, with the relief retroactively applying from October 1, 2026. This timeline demonstrates a coordinated effort to implement the policy swiftly.
Historically, the distinction between dyed and clear diesel fuel has been a cornerstone of federal fuel tax collection. The introduction of dyed fuel in the late 1980s was a response to widespread tax evasion schemes involving the diversion of untaxed off-road diesel for on-road use. The red dye became a readily identifiable marker, simplifying enforcement. The current executive order represents a significant, albeit temporary, departure from this established system, underscoring the administration’s prioritization of immediate economic relief over traditional enforcement mechanisms in this specific instance.
Economic Analysis and Potential Implications
The decision to allow dyed diesel for highway use, even temporarily, could have several economic ramifications. On the demand side, it could lead to increased consumption of dyed diesel, potentially impacting the supply dynamics of both dyed and clear diesel. Some analysts suggest that this could lead to a temporary decrease in the price differential between dyed and clear diesel, though the extent of this shift would depend on market responses and the duration of the policy.
On the supply side, fuel distributors and retailers will need to adapt their operations to accommodate the increased demand for dyed diesel for on-road purposes. The suspension of penalties simplifies this transition, removing a significant barrier. However, the long-term implications of potentially normalizing the use of dyed diesel for on-road applications, even for a limited period, are a subject of ongoing discussion. Concerns may arise regarding the potential for renewed tax evasion schemes once the relief period concludes, necessitating robust enforcement and clear communication from the IRS and state tax authorities.
The executive order’s directive to explore the elimination of deferred tax obligations adds another layer of complexity. If successful, this could represent a substantial financial windfall for diesel users who have utilized dyed fuel for highway purposes during the relief period. However, the feasibility and legal framework for such a broad tax forgiveness will likely be subject to intense scrutiny and debate.
The IRS’s commitment to issuing further guidance is crucial for providing clarity and ensuring smooth implementation. The details concerning Form 720 and other relevant tax filings will be critical for businesses to accurately report their activities and comply with the evolving regulatory landscape. As the relief period progresses, continued monitoring of market conditions, state-level responses, and official pronouncements will be essential for all stakeholders involved in the diesel fuel industry.