Candice Horbacz
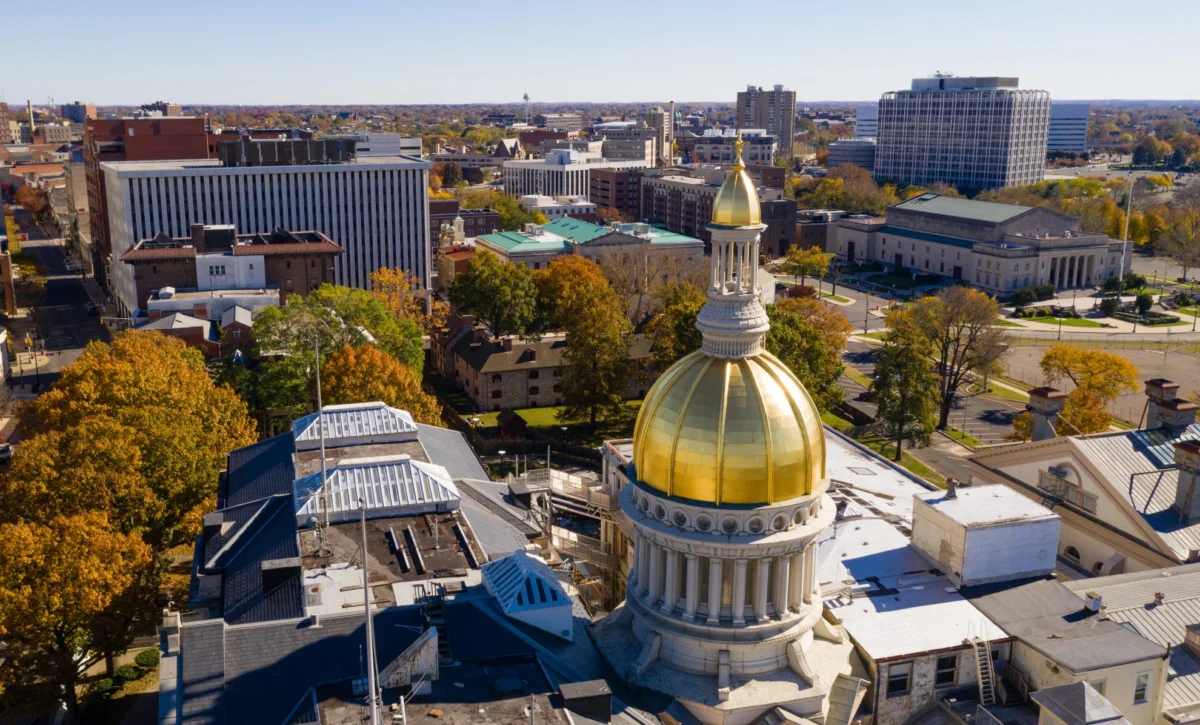
New Jerseyans will soon be checking their mailboxes for a property tax rebate courtesy of the ANCHOR property tax relief program, but a growing number of those boxes will likely turn up empty, signaling a deepening concern over the state’s unindexed tax policies amidst persistent inflation. The Affordable New Jersey Communities for Homeowners and Renters (ANCHOR) program, designed to alleviate the burden of the nation’s highest property taxes, maintains a gross income cutoff of $250,000 that has not been adjusted for inflation since the first rebate checks were distributed in 2023, based on residents’ 2019 income. This static threshold, coupled with a significant rise in the cost of living, means that many middle-income families whose earnings have merely kept pace with inflationary pressures are now finding themselves inadvertently disqualified from a crucial financial lifeline.
The ANCHOR program itself was enacted to replace the previous Homestead Benefit program, aiming to provide more direct and substantial property tax relief to a broader segment of homeowners and renters. When it launched, it was hailed as a significant step towards making New Jersey more affordable. For the initial round of payments, disbursed in the spring of 2023 and based on 2019 income, eligible homeowners earning up to $150,000 received $1,500, while those earning between $150,001 and $250,000 received $1,000. Renters earning up to $150,000 received $450. These amounts were intended to provide meaningful relief in a state where the average property tax bill routinely exceeds $9,000, placing an immense strain on household budgets. The program’s rollout was largely successful, with over 1.7 million residents receiving rebates, injecting hundreds of millions of dollars back into local economies. However, the foundational flaw in its design – the absence of an inflation adjustment mechanism for its income thresholds – has begun to manifest, threatening to erode its effectiveness and fairness.
The Erosion of Eligibility: Inflation’s Silent Tax
The core of the issue lies in the relentless march of inflation. Between 2019, the income year used for the first ANCHOR payments, and 2025, the projected year for the upcoming rebate distribution, prices have surged by approximately 26 percent. This figure, derived from consumer price index data, represents a substantial erosion of purchasing power. A household earning $200,000 in 2019 would need to earn roughly $252,000 in 2025 just to maintain the same standard of living. If such a household saw their income rise to $250,000 or $255,000 in 2025, they might feel they are merely treading water, yet under the ANCHOR program’s current rules, they would cross the $250,000 gross income threshold and receive no rebate at all. This phenomenon, often referred to as "bracket creep" when applied to income tax, effectively pushes taxpayers into higher eligibility tiers or out of eligibility entirely, not because their real income has increased, but because their nominal income has risen alongside inflation.
For many New Jerseyans, particularly those in the upper-middle income brackets who are already struggling with the state’s high cost of living, missing out on a rebate of $1,000 or $1,500 can be genuinely disheartening. It represents a tangible loss of financial relief, especially when they perceive their financial situation as stagnant or even worsening due to rising costs for groceries, fuel, and other essentials. This unintended consequence of a fixed income cap not only diminishes the program’s intended benefits but also fosters a sense of inequity among taxpayers who diligently manage their finances but are penalized by a system that fails to acknowledge economic realities.
Beyond ANCHOR: The Broader Problem of Unindexed Tax Brackets
While the ANCHOR program’s static income cutoff garners immediate attention due to the direct impact on rebate checks, it is merely a symptom of a much larger, systemic issue within New Jersey’s tax code: the state’s graduated-rate income tax thresholds also do not adjust for inflation. New Jersey operates on a progressive income tax system, meaning higher earners pay a larger percentage of their income in taxes. The state has several income tax brackets, with rates ranging from 1.4% to 10.75%. For instance, as of 2024, the 5.525% bracket applies to taxable incomes between $50,001 and $75,000, while the 6.37% bracket covers incomes from $75,001 to $150,000. These thresholds, like the ANCHOR cutoff, remain fixed year after year, regardless of economic conditions.
The failure to index income tax brackets to inflation results in what economists call "hidden tax increases." As wages nominally increase to keep pace with inflation, taxpayers are pushed into higher tax brackets, even though their real purchasing power remains unchanged or even declines. This means they are paying a larger share of their income in state taxes without any legislative action to raise tax rates. This bracket creep disproportionately affects middle-income earners, as they are most likely to cross into a higher bracket with modest nominal raises. Over time, this erosion of real income due to unindexed tax brackets can amount to significantly more than a missed ANCHOR rebate, quietly draining New Jerseyans’ wallets year after year.
A Look at the Data and Public Sentiment
New Jersey consistently ranks among the states with the highest tax burdens in the nation, a significant factor driving residents and businesses away. According to the Tax Foundation, New Jersey’s property taxes are indeed the highest in the country, with an average effective rate of 2.23% as of 2023, more than double the national average. This context underscores the critical importance of relief programs like ANCHOR. When such programs falter due to design flaws, public trust in government initiatives can erode.
Anecdotal evidence from local community forums and social media suggests a growing frustration among residents. Many express confusion and anger when they discover they are no longer eligible for a rebate they previously received, especially if their income increase was modest and merely reflective of cost-of-living adjustments. This sentiment is often echoed by local officials who frequently field inquiries from constituents baffled by their sudden disqualification. The feeling of being "taxed more for doing the same" resonates deeply with a population already contending with a high cost of living.
Reactions from Stakeholders and Policy Experts
The issue of unindexed tax provisions has not gone unnoticed by lawmakers and tax policy experts. Janelle Fritts, a Senior Policy Analyst with the Tax Foundation’s Center for State Tax Policy, whose work focuses on modernizing state tax codes, has consistently highlighted this problem. "The failure to index tax brackets and relief program thresholds to inflation is a pervasive issue in many states, but it hits particularly hard in high-cost-of-living areas like New Jersey," Fritts noted in a recent analysis. "It’s a silent tax increase that undermines the fairness and transparency of the tax system. Programs like ANCHOR are designed to provide relief, but without inflation adjustments, their effectiveness wanes over time, and they inadvertently penalize residents whose incomes are simply keeping pace with economic realities."
Some state legislators have begun to champion proposals for indexing. Assemblyman John Smith (D-15th District), for instance, recently introduced a bill (A-XXXX) that would mandate annual adjustments to the ANCHOR income thresholds and state income tax brackets based on the Consumer Price Index (CPI). "It’s a matter of fairness and common sense," Assemblyman Smith stated in a press conference. "Our constituents are seeing their grocery bills, gas prices, and utility costs skyrocket. When their wages adjust to reflect that, they shouldn’t be penalized by losing their property tax rebate or pushed into a higher tax bracket. We need a tax code that reflects the economic realities of our residents, not one that punishes them for merely keeping their heads above water."
However, such legislative efforts often face challenges. The primary concern cited by the Governor’s office and legislative leadership traditionally revolves around the potential fiscal impact. Indexing thresholds could lead to a reduction in state tax revenue or an increase in ANCHOR outlays, which would require offsetting budget cuts or new revenue sources. Governor Phil Murphy’s administration, while acknowledging the pressures of inflation on New Jersey families, has historically emphasized the need for fiscal prudence. A spokesperson for the Treasury Department indicated that while the administration is "always reviewing ways to improve the fairness and efficiency of our tax system," any changes would need to be carefully weighed against the state’s broader budgetary priorities and commitments.
The Broader Economic and Equity Implications
The cumulative effect of unindexed tax provisions extends beyond individual households. It impacts the state’s overall economic health and perpetuates issues of economic equity. When middle-income families face an increasing tax burden without a corresponding increase in their real income, their disposable income shrinks. This can lead to reduced consumer spending, which in turn can slow economic growth. Businesses, particularly local small businesses, rely on consumer spending to thrive.
Furthermore, the lack of indexing can exacerbate wealth disparities. Lower and middle-income families typically spend a larger percentage of their income on essential goods and services, making them more vulnerable to inflation. When their nominal income increases push them out of eligibility for relief programs or into higher tax brackets, it disproportionately affects their ability to save, invest, or absorb unexpected expenses. This creates a regressive outcome within a supposedly progressive tax system, undermining efforts to create a more equitable economic landscape.
Compared to other states, New Jersey lags in adopting inflation-adjusted tax codes. A significant number of states, including those with graduated income tax systems, have already implemented some form of indexing for their income tax brackets or standard deductions. States like California, New York, and Pennsylvania, all with substantial populations and diverse economies, have mechanisms in place to automatically adjust for inflation, thereby preventing bracket creep. This comparison highlights that implementing such adjustments is not an unprecedented or impossible task, but rather a policy choice.
Looking Ahead: Potential Solutions and the Path Forward
Addressing this issue requires a multifaceted approach. The most direct solution involves legislative action to amend the ANCHOR program and the state income tax code to include automatic inflation adjustments. This would involve tying the income thresholds to a recognized economic indicator, such as the Consumer Price Index for All Urban Consumers (CPI-U), which is widely used at the federal level and in many other states. Such a mechanism would ensure that the tax code evolves with economic conditions, maintaining the real value of relief programs and preventing hidden tax increases.
Another potential avenue could involve a periodic review and manual adjustment of thresholds by the legislature, although this approach is less ideal as it can become politicized and may not keep pace with rapid inflationary changes. Some policy analysts also suggest exploring targeted relief measures for specific income groups most impacted by the current ANCHOR cutoff.
The debate over indexing tax provisions is ultimately a question of fiscal philosophy and economic fairness. While the state government must balance its budget and fund essential services, it also has a responsibility to ensure its tax system is transparent, equitable, and does not inadvertently penalize residents for nominal income gains. As New Jerseyans brace for another round of ANCHOR rebates, the underlying issue of unindexed tax thresholds remains a pressing concern, one that demands comprehensive legislative attention to safeguard the financial well-being of its citizens in an ever-changing economic landscape. The ongoing discussion surrounding these policies will undoubtedly shape the future of tax relief and economic equity in the Garden State.