Candice Horbacz
- Federal Tax Law & IRS Updates
- August 27, 2026
- 47 views
Poland’s Restrictive Tax Loss Provisions Impede Investment and Economic Growth, Report Finds
Poland’s stringent corporate tax rules regarding net operating losses (NOLs) are significantly hampering business investment, innovation, and expansion, placing the nation at a competitive disadvantage within Europe, according to a…
- Federal Tax Law & IRS Updates
- August 27, 2026
- 59 views
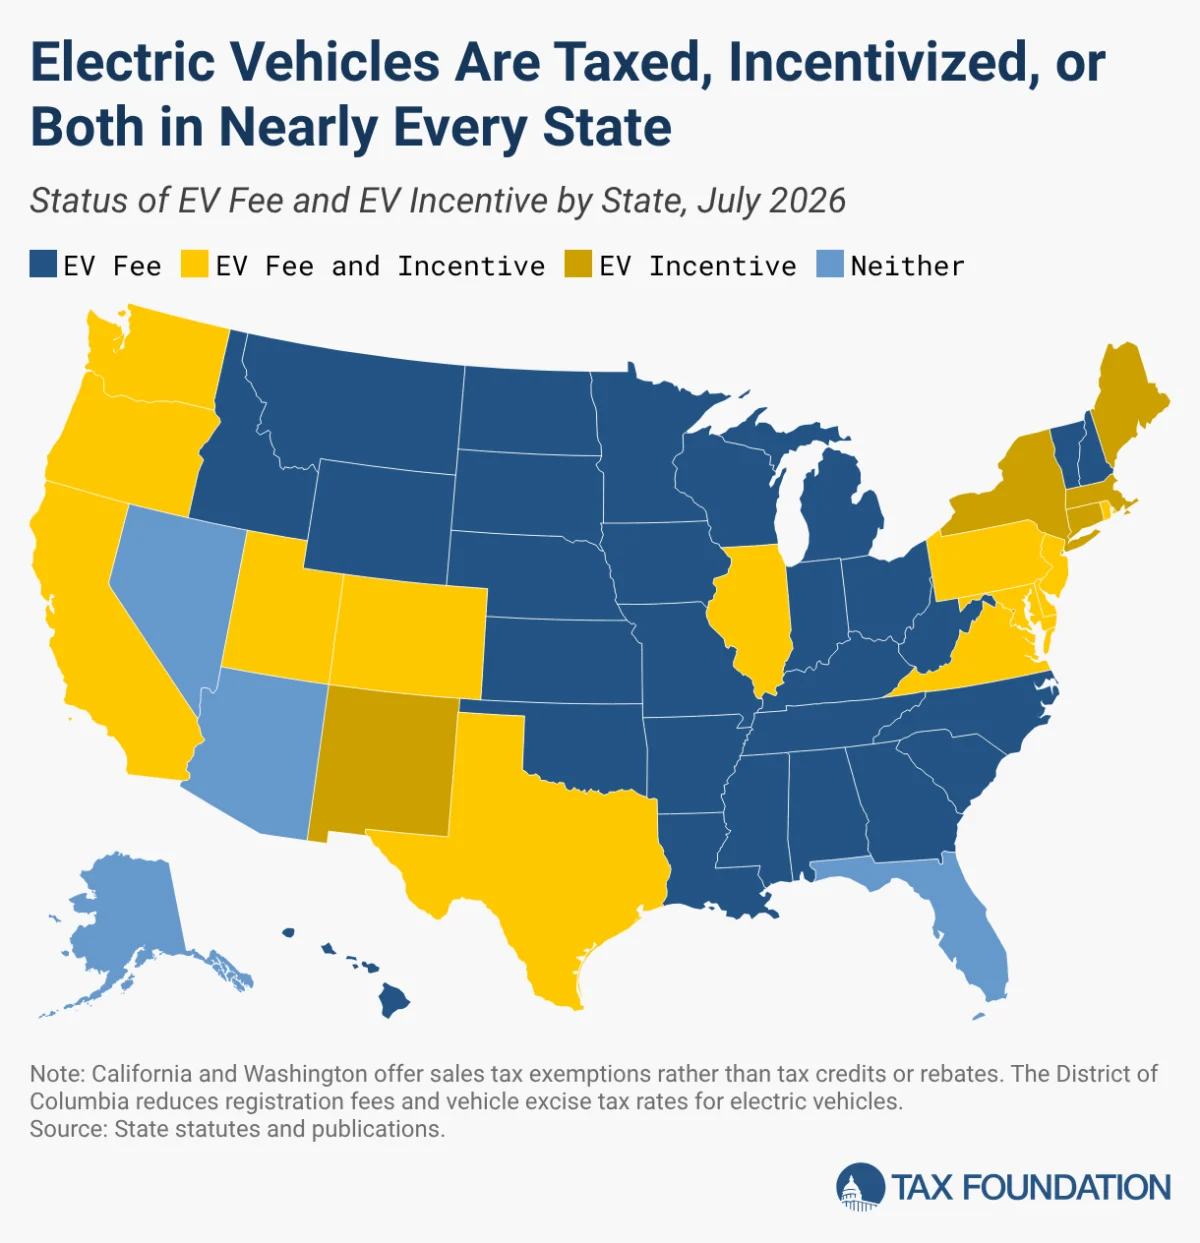
States Apply a Variety of Tax Treatments to Electric Vehicles: An Examination of Annual Fees and Purchase Incentives by State as of July 2026.
As the electric vehicle (EV) market continues its rapid expansion across the United States, state legislatures are grappling with the complex task of integrating these transformative technologies into existing fiscal…
- Federal Tax Law & IRS Updates
- August 27, 2026
- 46 views
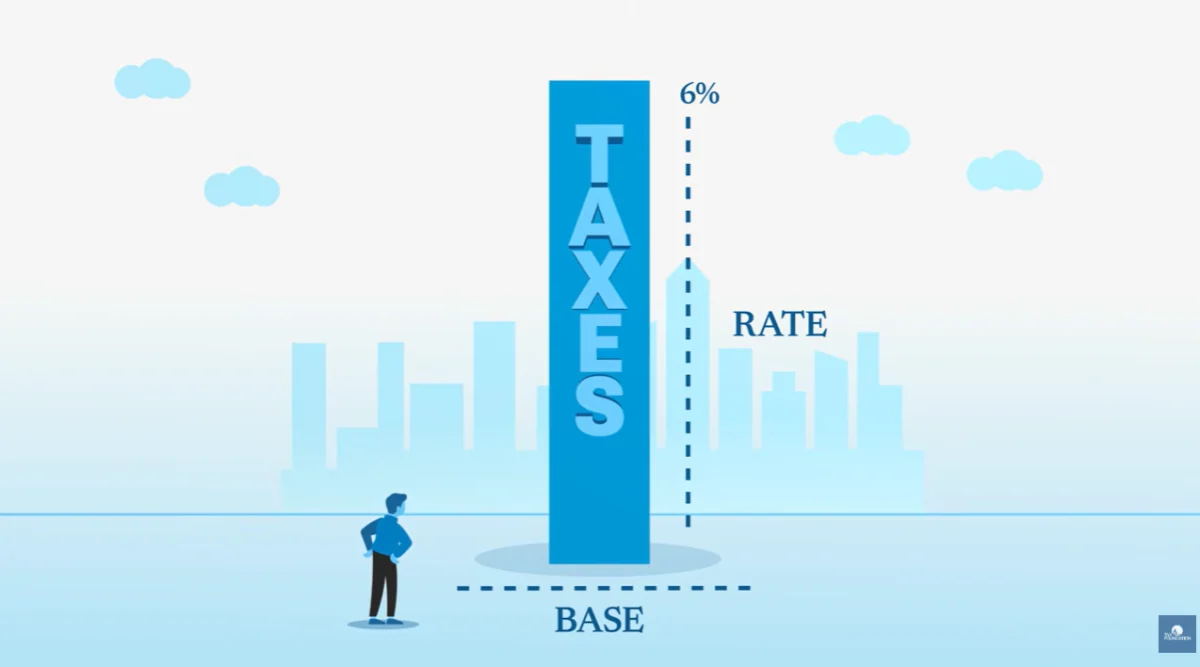
The Hidden Half of Taxation: Why the Tax Base Matters as Much as the Rate
When the question, "How high are my taxes?" arises, public discourse almost invariably fixates on the tax rate—the percentage of income, property value, or transaction cost levied by the government.…
- Federal Tax Law & IRS Updates
- August 27, 2026
- 44 views
Addressing the Looming Fiscal Crisis: Evaluating Tax Reforms for Sustainable US Spending
As debt held by the public reaches 101 percent of Gross Domestic Product (GDP) and Social Security risks insolvency by 2032, lawmakers are confronted with the urgent imperative to steer…
- Federal Tax Law & IRS Updates
- August 27, 2026
- 50 views
The Complex Unraveling of Trump Accounts: A Critical Look at America’s Latest Savings Experiment
Last year’s One Big Beautiful Bill Act (OBBBA) has been the most consequential piece of economic legislation of President Trump’s second term in office. Championed as a landmark reform designed…
- Federal Tax Law & IRS Updates
- August 26, 2026
- 43 views
Dr. Heidi Overton Nominated as FDA Commissioner, Facing Urgent Calls for Tobacco Policy Reform
Last week, President Trump formally nominated Dr. Heidi Overton, a prominent White House domestic policy aide, to assume the critical role of Commissioner of the Food and Drug Administration (FDA).…
- Federal Tax Law & IRS Updates
- August 25, 2026
- 39 views
Dominican Republic’s Rapid Tax Reform Raises Concerns Over Process, Certainty, and International Standards
The Dominican Republic’s accelerated approach to tax reform in June has sparked significant debate, drawing criticism for its rapid legislative timeline and perceived lack of stakeholder consultation. Enacted within a…
- Federal Tax Law & IRS Updates
- August 24, 2026
- 44 views
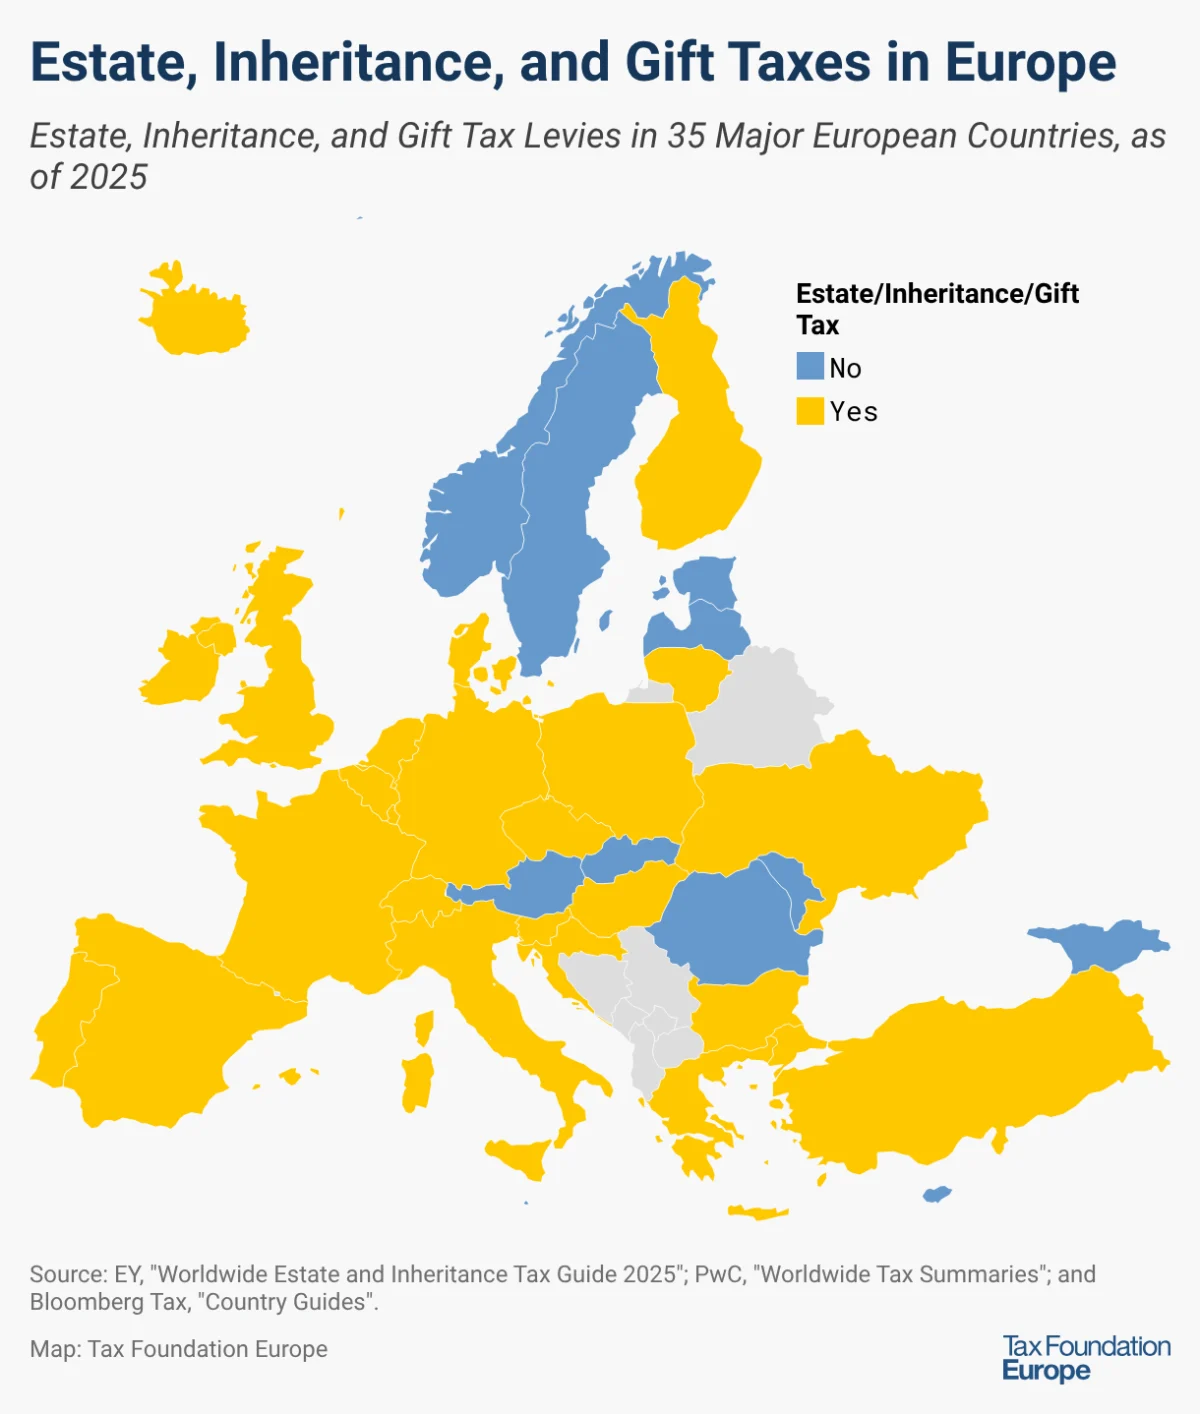
The Global Tapestry of Wealth Transfer Taxation: Navigating Estate, Inheritance, and Gift Levies
The tax rates applied to estates, inheritances, and gifts often depend on the level of familial closeness to the inheritor, as well as the specific amount of wealth to be…
- Federal Tax Law & IRS Updates
- August 24, 2026
- 80 views
How Expensing for Capital Investment Transforms Project Economics: A Case Study Approach
The Tax Foundation, utilizing its macroeconomic model, has consistently identified improvements to cost recovery as one of the most potent pro-growth policy options available. This assessment is based on the…
- Federal Tax Law & IRS Updates
- August 24, 2026
- 77 views
If Amendment 5 Passes, Lawmakers Need a Zephyr, not a Gale, to Sail Missouri to Tax Competitiveness
Understanding Amendment 5: The Core Proposal At its heart, Amendment 5 mandates a gradual phase-out of Missouri’s individual income tax. This is a significant shift, as the individual income tax…