Lina Irawan
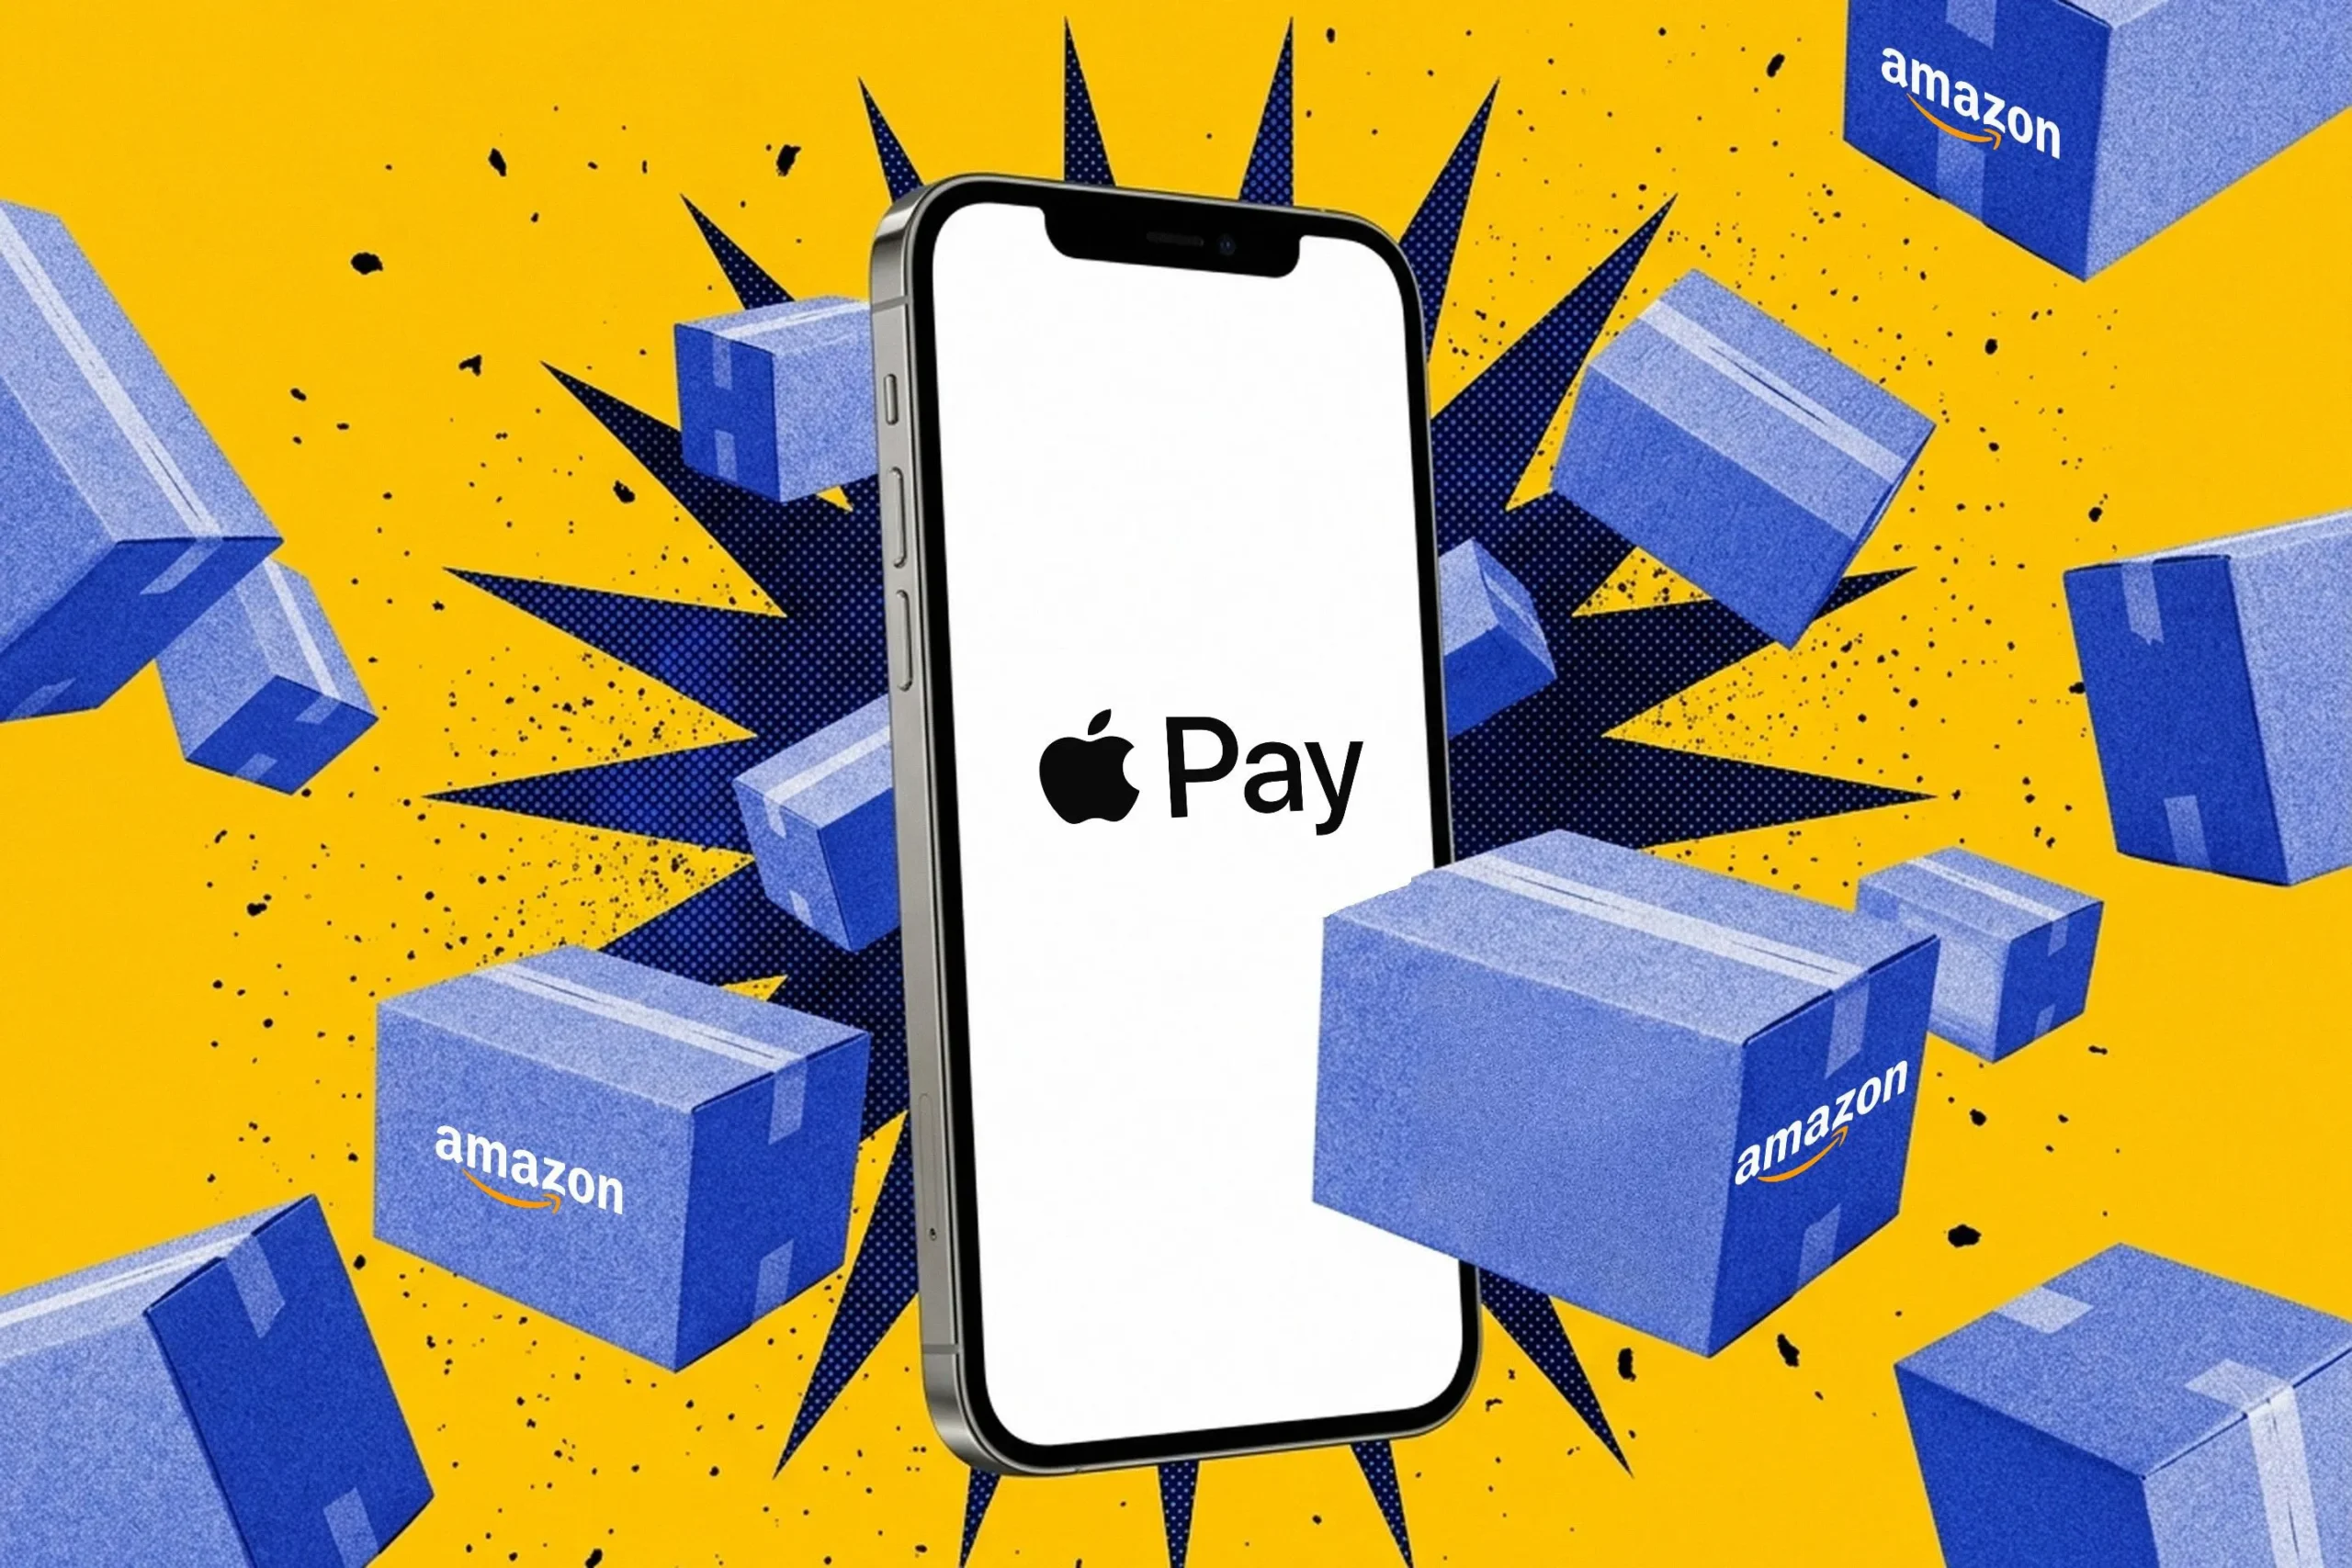
While a growing number of the nation’s largest retailers and marketplaces, including prominent names like Target, Home Depot, and eBay, have embraced Apple Pay as a standard checkout option, Amazon, the undisputed leader in U.S. online retail, remains a notable holdout. This persistent refusal to integrate Apple’s popular mobile payment service has puzzled consumers and industry observers alike, particularly in the wake of Walmart’s recent decision to adopt Apple Pay in its physical stores after years of customer demand. The move by Walmart, announced in August, has intensified speculation about whether Amazon might eventually follow suit, or if its entrenched strategic considerations will continue to keep Apple Pay at bay.
Apple Pay has solidified its position as a dominant force in the digital payment sphere, boasting acceptance at over 85% of U.S. retailers and empowering millions of iPhone users to conduct transactions with a simple tap. Its pervasive presence is hardly surprising, given that Apple ships more than half of all smartphones in the United States. The convenience of a double-press of the side button, a tap, and a swift payment has become synonymous with modern retail efficiency. Yet, Amazon has never publicly articulated its reasons for eschewing Apple Pay, and Apple itself has remained silent on the matter, declining to respond to inquiries. This silence only fuels the ongoing debate surrounding Amazon’s unique stance in an increasingly digitized payment ecosystem.
The Shifting Sands of Retail Payments: Walmart’s Embrace of Tap-to-Pay
Walmart’s decision to integrate tap-to-pay functionality across its vast network of 4,600 U.S. stores by the end of 2026 marks a significant milestone in the broader adoption of digital wallets. This strategic pivot acknowledges the burgeoning popularity of mobile payment solutions and directly addresses long-standing customer requests. The news was met with widespread enthusiasm across online forums and even celebrated in unexpected venues, highlighting the consumer demand for frictionless payment experiences.
However, it is crucial to note the specific scope of Walmart’s implementation: the change applies exclusively to its brick-and-mortar locations, not to Walmart.com. This distinction is vital for understanding the complexities involved. Online payment systems often operate under different frameworks and strategic priorities than in-store point-of-sale systems. In this respect, Amazon and Walmart now find themselves on remarkably similar ground: both accept Apple Pay in their respective physical store chains (Amazon through its Whole Foods subsidiary, which it acquired in 2017), but neither accepts it on their primary online retail platforms. Whole Foods, with its 540 U.S. brick-and-mortar locations, has long accepted Apple Pay, confirming Amazon’s practical ability to integrate the service when strategically aligned.
Amazon’s "Frictionless" Legacy and the Appeal to New Customers
Industry experts, such as Eric Cohen, founder and CEO of Merchant Advocate, generally predict that Amazon will maintain its resistance to Apple Pay. Cohen points to Amazon’s deeply ingrained "1-Click" checkout system, a pioneering innovation that has defined frictionless online shopping for decades. This patented technology, one of the most famous in software history, allows regular Amazon shoppers, especially its more than 200 million Prime members in the U.S., to complete purchases instantly with a stored card number, bypassing multiple steps. "Amazon has their one-click. It’s frictionless," Cohen emphasizes, suggesting that the company perceives less urgency in adopting an external system for its established customer base.
While Apple Pay may offer minimal added convenience for Amazon’s loyal existing customers, its potential to attract new users represents a compelling argument. For first-time Amazon shoppers, particularly those navigating the platform on an iPhone, the ability to bypass the manual entry of a 16-digit credit card number and associated details on a small mobile screen could significantly enhance the onboarding experience. This seamless integration could remove a potential barrier for hundreds of millions of global Apple Pay users, translating into a wider customer funnel for Amazon. Cohen suggests that Amazon is likely "crunching these kinds of numbers behind the scenes," evaluating the trade-offs between current system efficiency and potential customer acquisition.
The Strategic Imperative: Data Control and Operational Efficiency
Amazon’s reluctance to accept Apple Pay appears to be less about transaction costs — Apple notably does not charge merchants a special fee for accepting Apple Pay, whether in stores or online — and more about fundamental control over critical business data. "It’s about control of data," Cohen states, pinpointing a core strategic differentiator.
When a customer uses Apple Pay, the actual payment card number and associated sensitive data are masked for security purposes through a process called tokenization. Instead of receiving the raw card number, merchants like Amazon would receive a unique, tokenized number for each transaction. While highly secure and beneficial for preventing fraud at the point of sale, this masking of data creates several operational challenges for Amazon.
Aaron McPherson, principal and founder of AFM Consulting, explains that access to raw card data is instrumental for Amazon in building robust risk models. These models are crucial for accurately assessing the likelihood of fraud, managing chargebacks, and understanding transaction patterns. Without this granular data, Amazon’s ability to refine its fraud detection algorithms and minimize costly chargeback incidents could be compromised. Given the massive scale of Amazon’s operations, even minor increases in fraud or chargebacks could translate into significant financial losses. Therefore, Amazon has a strong vested interest in retaining access to customer card data to safeguard its financial integrity and operational efficiency.
Furthermore, Amazon benefits from a legal requirement, particularly on debit card transactions, that mandates retailers be given a choice from at least two unaffiliated networks for routing. This choice allows companies to optimize transaction costs by selecting the network with the lowest fees. McPherson suggests that accepting Apple Pay could potentially limit Amazon’s ability to leverage this multi-network routing advantage for debit transactions, thereby increasing its overall processing costs. This financial implication, while not a direct fee from Apple, contributes to Amazon’s calculated resistance.
The Echoes of a Tech Rivalry: Apple vs. Amazon
Beyond data and operational considerations, the long-standing and often intense rivalry between Amazon and Apple undoubtedly plays a significant role in the ongoing payment standoff. As two of the world’s most valuable and influential technology companies, their competitive spheres inevitably overlap across numerous industries. "When you’re talking about these giants, there’s got to be a little bit of this… ego," Cohen remarks, characterizing their relationship as "friendly enemies." The idea of Amazon prominently displaying the Apple logo at checkout, thereby subtly endorsing a competitor, is likely a difficult pill for the e-commerce titan to swallow.
The history of this rivalry stretches back over 15 years, punctuated by notable clashes. A particularly illustrative incident occurred in 2010 when Apple CEO Steve Jobs and his executives internally debated how to respond to an Amazon commercial promoting the Kindle. The ad depicted a customer using an iPhone to purchase books via the Kindle app, then seamlessly switching to an Android phone to continue reading. Phil Schiller, then Apple’s senior vice president, expressed his displeasure in an email, calling it "Not fun to watch." Jobs’s response was direct and telling: he suggested that Apple’s "first step might be to say they must use our payment system for everything, including books… let’s force them to use our far superior payment system."
These emails, which first surfaced during the U.S. Department of Justice’s 2012 e-book antitrust case against Apple, recently became a key opening example in the DOJ’s 2024 "smartphone monopoly" antitrust complaint against Apple. The year following the Kindle ad, Apple indeed implemented a policy requiring a 30% cut from Amazon and other retailers on in-app e-book purchases, leading Amazon to disable the purchase feature within its app to avoid the exorbitant fee. This historical animosity and strategic maneuvering underscore a deep-seated competitive dynamic. "They [Amazon] definitely see Apple as a big rival, and so I think it’s unlikely that they would do anything to help Apple out," McPherson concludes, highlighting the strategic implications of such a rivalry.
The Antitrust Lens: Apple’s NFC Control and Competing Payment Ecosystems
The ongoing 2024 DOJ antitrust case against Apple further illuminates the broader context of this payment dispute. The lawsuit alleges that Apple has maintained its dominant market position, in part, by preventing other digital wallets from accessing its Near Field Communication (NFC) chip for tap-to-pay functionality on iPhones. The complaint explicitly states, "While Apple actively encourages banks, merchants, and other parties to participate in Apple Wallet, Apple simultaneously exerts its smartphone monopoly to block these same partners from developing better payment products and services for iPhone users." This allegation underscores Apple’s tight control over its ecosystem, a control that directly impacts competitors and potential partners alike.
In this landscape, Amazon is not merely a retailer but also a proprietor of its own digital wallet: Amazon Pay. While Google Pay serves as Apple Pay’s most direct parallel for Android users, Amazon Pay represents Amazon’s strategic foray into the payment processing arena. Tony DeSanctis, vice president at Cornerstone Advisors, argues that Amazon’s ambitions for Amazon Pay are a primary reason why Apple Pay is unlikely to appear on Amazon.com anytime soon.
Amazon Pay not only facilitates payments on Amazon.com but also extends its reach to thousands of third-party non-Amazon retailers, including popular brands like Grubhub, Casper, and Fashion Nova. This expansion is central to Amazon’s strategy to generate revenue by drawing smaller merchants into its payment ecosystem. "They’re trying to generate revenue off of that by bringing smaller merchants into their ecosystem, and so they’re actually doing exactly what Apple’s doing," DeSanctis explains. From Amazon’s perspective, integrating Apple Pay would mean "emboldening their own competitor, Apple Pay, by giving them all of that Amazon volume."
For everyday shoppers, both Amazon Pay and Apple Pay offer similar benefits of convenience, allowing users to leverage stored payment information for seamless checkout experiences. In a January 2024 comment to the Consumer Financial Protection Bureau, Amazon articulated that digital wallets are "additive, not limiting, in terms of consumer options" and "often promote consumer safety." However, an Amazon spokesperson notably declined to confirm whether it views Apple Pay through the same lens, maintaining the company’s characteristic reticence on the specific issue.
Broader Implications for Consumers and the Future of Digital Commerce
The standoff between Amazon and Apple over payment integration has significant implications for consumers and the future trajectory of digital commerce. For iPhone users who prefer the convenience and security of Apple Pay, Amazon’s refusal represents a persistent friction point, forcing them to revert to manual card entry or utilize Amazon’s proprietary payment solutions. This limits consumer choice and can detract from the otherwise seamless experience that digital wallets promise.
From an industry perspective, Amazon’s continued resistance highlights the ongoing battle for control over payment ecosystems and valuable customer data. As digital payments continue their exponential growth, the ability to collect, analyze, and leverage transaction data becomes an increasingly critical competitive advantage. Companies like Amazon and Apple are not just competing on products and services, but on the underlying infrastructure that facilitates commerce.
The regulatory scrutiny surrounding Apple’s control over its NFC chip, as evidenced by the DOJ lawsuit, could potentially introduce new dynamics. Should regulatory actions compel Apple to open its NFC technology to third-party wallets, the competitive landscape for digital payments could shift dramatically, potentially influencing Amazon’s long-term calculus. However, such developments are often protracted and their outcomes uncertain.
Ultimately, analyst predictions suggest that a resolution to the Amazon-Apple Pay impasse is not imminent. Amazon’s deeply entrenched payment systems, its strategic focus on Amazon Pay, and the historical animosity with Apple create a formidable barrier. While the allure of attracting new customers remains a consideration, it appears to be outweighed by Amazon’s desire for data control, operational efficiency, and the strategic imperative to grow its own payment ecosystem. For the foreseeable future, consumers seeking to use Apple Pay will continue to find Amazon.com a notable exception in the rapidly expanding world of digital payments.