Pevita Pearce
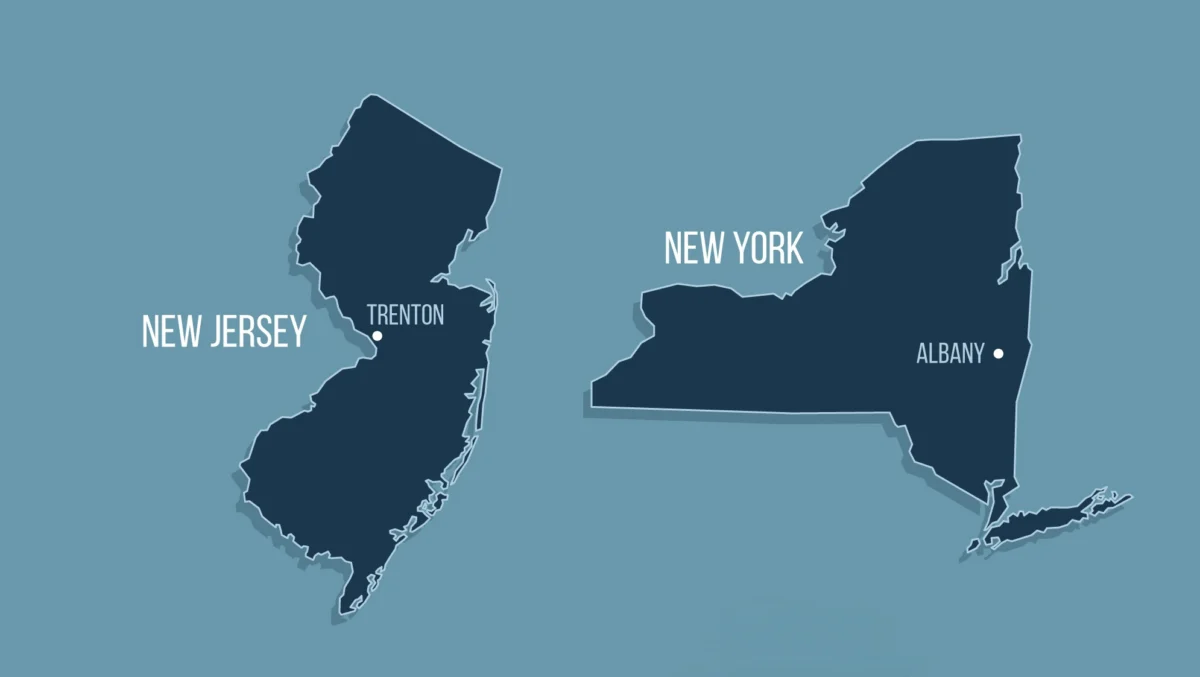
Every December, tax preparers grapple with a recurring challenge: a client’s purchase of a substantial SUV or significant piece of equipment before the year-end. While the federal deduction is often substantial and the calculations straightforward, the subsequent preparation of New York or New Jersey state returns can become a complex minefield if treated as a mere extension of federal law. Neither state follows the federal lead, and their approaches diverge significantly, creating a scenario where a single asset acquisition can result in three distinct year-one deductions across federal, New York, and New Jersey tax filings.
This divergence stems from fundamental differences in how these states approach asset depreciation and modifications to federal adjusted gross income (AGI). New York, for instance, begins with federal AGI and applies specific state modifications, some of which are permanent. New Jersey, on the other hand, largely disregards the federal basis for an asset, maintaining its own calculations that are ultimately reconciled upon the asset’s sale. This intricate interplay of state-specific tax codes necessitates a meticulous examination of acquisition dates, vehicle classifications, and state conformity rules to ensure accurate tax compliance and optimal tax planning for businesses and individuals.
Understanding Federal Depreciation Rules: A Foundation for State Compliance
The cornerstone of this tax complexity lies in the federal depreciation rules, particularly the bonus depreciation and Section 179 expensing provisions. For property acquired and placed in service after January 19, 2025, the 100 percent bonus depreciation rate will be available. However, property acquired after September 27, 2017, and before January 20, 2025, falls under a phasedown schedule. For assets placed in service in 2026, the bonus depreciation rate will be 20 percent, as outlined in IRS Revenue Procedure 2026-15. This timeline is critical: a vehicle ordered in 2024 but delivered in 2026 will be subject to the lower 20 percent rate. Taxpayers and their advisors must meticulously track not just the delivery date but also the order date to accurately determine applicable depreciation rates.
For the 2026 tax year, the Section 179 expense deduction limit is set at $2,560,000, with a phase-out beginning at $4,090,000. A specific limitation exists for heavy sport utility vehicles (SUVs), capping the deduction at $32,000, as detailed in IRS Revenue Procedure 2025-32. The definition of a qualifying SUV under Section 179(b)(5) is a four-wheeled passenger vehicle, not subject to Section 280F limitations, and rated at no more than 14,000 pounds gross vehicle weight. This SUV cap is mutually exclusive of the luxury automobile caps under Section 280F. A passenger-bodied vehicle exceeding 6,000 pounds gross vehicle weight rating (GVWR) qualifies for the $32,000 SUV cap and is exempt from Section 280F limitations. Conversely, lighter vehicles are subject to Section 280F caps and do not benefit from the SUV provision. The crucial determinant for this classification is the GVWR indicated on the vehicle’s door-jamb label, not the curb weight found in manufacturer brochures.
New York’s Approach: Bonus Depreciation Reinstated, Section 179 Limited
New York State generally conforms to federal AGI on a rolling basis but then decouples through specific provisions within its tax law. Two key sections, 612(b)(8) and 612(k), govern the treatment of qualified property. Section 612(b)(8) mandates the add-back of federal Section 168(k) bonus depreciation for qualified property placed in service on or after June 1, 2003, irrespective of the asset’s weight. Subsequently, Section 612(k) permits depreciation based on what would have applied had the property been acquired on September 10, 2001, essentially allowing for ordinary MACRS depreciation under pre-bonus law. This creates a timing difference, as the federal deduction is effectively deferred. When the asset is sold, Section 612(l) adjusts the gain or loss to reflect the depreciation taken.
On New York State Form IT-225, these adjustments are represented by modification A-209 (add-back of federal bonus depreciation), S-213 (substitution for ordinary depreciation), and S-214 at the time of disposition. The underlying computation for this adjustment is detailed on Form IT-398. Consequently, taxpayers who elect out of bonus depreciation federally will find the add-back and substitute amounts to be identical, effectively neutralizing the federal election’s impact in New York for timing purposes.
The treatment of Section 179 expensing, particularly for heavy SUVs, is markedly different and more restrictive in New York. Section 612(b)(36) requires an add-back of any Section 179 deduction claimed for a sport utility vehicle that is not classified as a passenger automobile under Section 280F(d)(5), unless the taxpayer is an eligible farmer. This weight-based classification mirrors the federal determination but leads to a contrary outcome in New York. The only corresponding subtraction is found in Section 612(c)(37), which allows a deduction solely for amounts required to be recaptured under Section 179(d).
On Form IT-225, these adjustments appear as A-208 (add-back of Section 179 for SUVs) and S-212 (recapture). Crucially, New York does not provide a substitute depreciation code or a disposition adjustment for Section 179 deductions related to these vehicles. This means that the federal basis of the asset is effectively reduced to near zero for New York tax purposes, and any gain recognized at the federal level upon sale is subject to New York tax without a corresponding adjustment for the previously disallowed Section 179 deduction. This effectively results in a permanent loss of the Section 179 deduction in New York for such assets.
New York also employs its own definition of a sport utility vehicle in the instructions for Form IT-225. It is defined as "any four-wheeled passenger vehicle manufactured primarily for use on public streets, roads, and highways," with exclusions for ambulances, hearses, vehicles used for hire, and "any truck, van, or motor home." This definition lacks a bed-length test and does not cross-reference federal exclusions. Therefore, a crew-cab pickup truck with a bed under six feet, which might be capped as an SUV federally, could be classified as a truck in New York, avoiding the SUV limitation. Conversely, a heavy, passenger-bodied SUV could be subject to the SUV cap in both jurisdictions. Taxpayers making significant asset elections based on borderline vehicle classifications are advised to seek clarity through a New York Advisory Opinion rather than relying on assumptions.
The strategic implication for New York taxpayers acquiring heavy SUVs is clear: elect bonus depreciation over Section 179 expensing. Bonus depreciation is recovered over the asset’s recovery period through the IT-398 process. Section 179, however, offers no such recourse. Furthermore, Section 179(c)(2) allows taxpayers to revoke a Section 179 election without IRS consent, providing an opportunity to amend prior-year returns if a heavy SUV election was mistakenly made.
New Jersey’s Independent System: Maintaining Separate Financial Records
New Jersey officially decoupled from federal depreciation rules in 2004 with the enactment of P.L. 2004, c.65, which added Section 5-1.2 to the Gross Income Tax Act for assets placed in service on or after January 1, 2004. Since then, New Jersey has maintained its independent depreciation regime. The state’s return instructions offer minimal guidance, with all operative rules residing in Worksheet GIT-DEP, revised in October 2025.
This worksheet imposes a strict maximum Section 179 deduction of $25,000, a figure that is not indexed for inflation. Notably, there are no business income limitations, and unused Section 179 deductions cannot be carried forward. Similarly, any unused adjustment cannot be carried back or applied against other income categories. New Jersey does not recognize the federal bonus allowance as it currently exists, and the GIT-DEP worksheet makes no mention of specific vehicle rules, including SUV or luxury automobile caps, or provisions for listed property. Consequently, a heavy SUV in New Jersey is treated simply as any other business asset.
However, what New Jersey disallows in the year of acquisition, it generally restores upon the asset’s sale. The GIT-DEP worksheet is applied until the asset is fully depreciated or disposed of. Adjustments to the gain or loss from disposition are made in Part IV of the worksheet, flowing to Schedule NJ-DOP. Any amount previously denied by New Jersey is effectively recouped as a reduced capital gain. The $25,000 ceiling on Section 179 is, therefore, a timing difference rather than a permanent loss.
A critical procedural trap exists within New Jersey’s system. The worksheet states that if the initial New Jersey adjustment was not reported—either due to a reporting error or because the taxpayer did not have a New Jersey filing requirement in the initial year—the asset’s New Jersey basis will default to its federal tax basis. In such cases, a New Jersey depreciation adjustment is neither required nor allowable in subsequent years. This underscores the importance of correctly reporting the initial New Jersey depreciation adjustment on the GIT-DEP worksheet, as missing this first opportunity locks the asset’s basis to federal calculations for its entire life in New Jersey.
The Lease as a Strategic Alternative: Navigating Tax Implications
For certain assets, particularly heavy SUVs, leasing can present a more straightforward tax path, provided the arrangement is structured as a true lease. Federal Section 179(d)(1)(C) limits the expensing election to property "acquired by purchase for use in the active conduct of a trade or business." Under a true lease, the lessee does not acquire ownership, thereby precluding eligibility for Section 179 expensing or bonus depreciation. Instead, the lessee claims rental expenses.
Both New York and New Jersey tax regimes are designed to align with federal depreciation deductions. New York’s add-back provision (A-208 on Form IT-225) is triggered "if you claimed an IRC § 179 deduction." Similarly, New Jersey’s Worksheet GIT-DEP applies only where "Special Depreciation Allowance or Section 179 expense were deducted." A genuine lease of a heavy SUV effectively sidesteps these state-specific add-backs and limitations.
It is important to note that the federal government still imposes limitations on the deductibility of lease payments for lighter vehicles classified as listed property under Section 280F(c)(2). These limitations, designed to be "substantially equivalent" to ownership caps, reduce the deductible lease amount by an "allowable percentage." However, these ownership caps apply only to passenger automobiles. Therefore, a leased vehicle with a GVWR exceeding 6,000 pounds would not be subject to these inclusion amounts, further enhancing the tax efficiency of leasing such vehicles.
The substance of the transaction is paramount. A lease agreement with a nominal buyout price, a term that mirrors the asset’s useful life, or provisions that build equity for the lessee will likely be recharacterized as a purchase by tax authorities, thereby bringing all the aforementioned depreciation and expensing rules back into play.
Case Illustration: One Asset, Three Divergent Outcomes
To illustrate the impact of these differing tax treatments, consider an $80,000 passenger-bodied SUV with a GVWR exceeding 6,000 pounds, used 100 percent for business, and acquired and placed in service in the fourth quarter of 2026.
-
Federal: Assuming the 2026 bonus depreciation rate of 20% (per Rev. Proc. 2026-15), the federal deduction would be $16,000. Alternatively, if Section 179 is elected and the taxpayer qualifies for the full amount, up to $2,560,000 can be expensed, capped at $32,000 for this SUV. A strategic choice between bonus depreciation and Section 179 would depend on the taxpayer’s overall tax situation.
-
New York: New York requires an add-back of the federal bonus depreciation under Section 612(b)(8). The taxpayer would then claim ordinary MACRS depreciation. For Section 179, New York requires an add-back of the deduction under Section 612(b)(36), and this deduction is permanently lost. Therefore, if Section 179 were elected federally, New York would disallow it, and no substitute depreciation would be allowed.
-
New Jersey: New Jersey’s Worksheet GIT-DEP limits the Section 179 deduction to $25,000. The state does not recognize federal bonus depreciation. Therefore, a taxpayer could claim up to $25,000 in year one under Section 179. Any remaining basis would be depreciated over the asset’s life according to New Jersey’s rules. Upon sale, any disallowed portion of depreciation would be reflected as a reduction in capital gain.
This example underscores the critical need for state-specific tax planning. Relying solely on federal calculations can lead to significant underpayment or overpayment of state taxes.
Year-End Tax Planning Checklist for Business Asset Acquisitions
To mitigate these complexities, tax preparers and their clients should consider the following year-end checklist:
- Verify Acquisition and Service Dates: Confirm the exact date property was ordered and when it was placed in service. This is crucial for determining applicable bonus depreciation rates and Section 179 limitations.
- Confirm Vehicle Classification: Obtain the Gross Vehicle Weight Rating (GVWR) from the vehicle’s door-jamb label to accurately classify it as a heavy SUV or standard vehicle for federal and state purposes.
- Review State Conformity Rules: Understand each state’s specific rules regarding bonus depreciation and Section 179 expensing, including any add-backs, subtractions, or unique definitions.
- Analyze Lease vs. Purchase: Evaluate the tax implications of leasing versus purchasing an asset, especially for heavy vehicles, considering state-specific rules.
- Consult State-Specific Guidance: Refer to state tax forms, instructions, and publications (e.g., New York Form IT-225, New Jersey Worksheet GIT-DEP) for precise requirements.
- Consider State Advisory Opinions: For borderline cases or significant asset acquisitions, obtaining a formal advisory opinion from the state tax authority can provide definitive guidance.
- Document All Elections: Maintain meticulous records of all federal and state depreciation and expensing elections, including any revocations or amendments.
- Plan for Asset Dispositions: Understand how each state will treat the gain or loss upon sale of an asset, particularly if prior depreciation was treated differently across jurisdictions.
The federal tax system, while complex, often serves as a starting point for state tax calculations. However, the divergence in state tax laws, particularly in New York and New Jersey concerning the treatment of heavy asset purchases, demands a proactive and nuanced approach. A federal-only model can easily lead to incorrect state tax liabilities, as the same asset placed in service the same week can result in a timing difference in Trenton, a permanent loss in Albany, and a full deduction in Washington D.C. Accurate tax compliance and strategic planning begin with understanding the acquisition date and the vehicle’s weight rating, not just the invoice price.
About the Author: Myung Keon Kim, CPA, is the owner of Myung Keon Kim CPA, a tax and accounting practice based in New York. The firm serves small businesses and individuals across New York, New Jersey, and Connecticut, offering services in both English and Korean. Mr. Kim also holds the CPIM designation in planning and inventory management. Further information is available at https://keonadvisory.com.
Photo credit: magnific/Freepik