Lana Rhoades
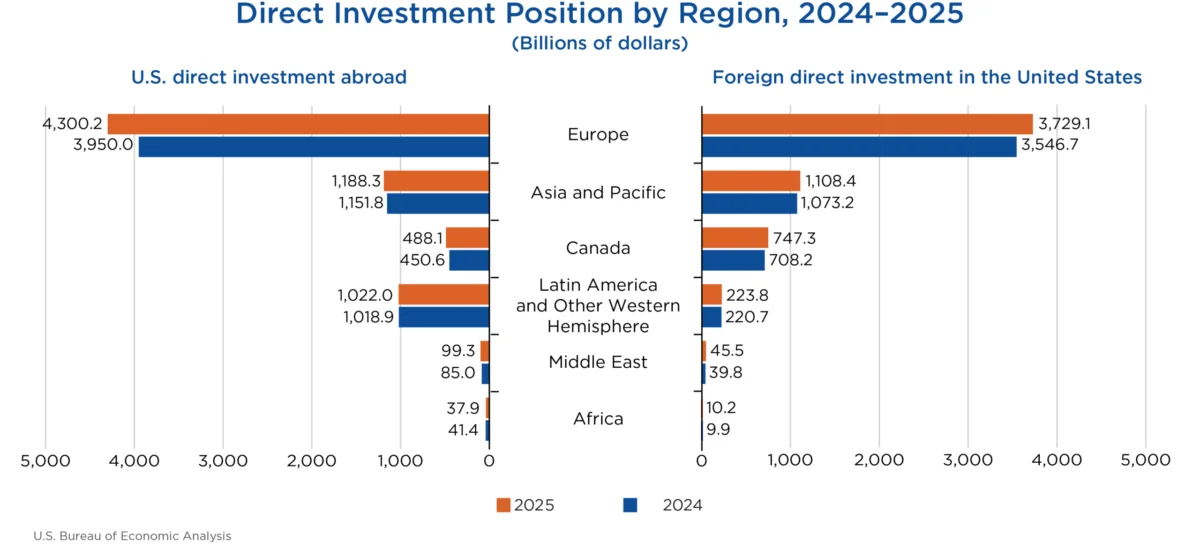
The cumulative level of U.S. direct investment abroad surged to $7.14 trillion by the end of 2025, marking a significant increase of $438.1 billion from the previous year. This substantial growth, as detailed in the latest statistics released by the U.S. Bureau of Economic Analysis (BEA), was predominantly fueled by a $350.2 billion expansion in investment within Europe, with the United Kingdom and Luxembourg emerging as key destinations. Manufacturing sectors, particularly chemical manufacturing, led this outward investment trend. Concurrently, foreign direct investment (FDI) in the United States also experienced robust growth, climbing by $266.0 billion to reach a total position of $5.86 trillion. Europe was also the primary driver of this inward investment, contributing an increase of $182.4 billion. German and Canadian multinationals spearheaded this surge, with investment positions growing by $49.0 billion and $39.2 billion, respectively. The manufacturing sector in the U.S. also saw the most substantial increase in foreign investment, driven by the electrical equipment and components industry.
Overview of 2025 Investment Landscape
The BEA’s comprehensive report for 2025 paints a picture of dynamic international capital flows, underscoring the interconnectedness of the global economy and the strategic importance of the United States as both an investor and a recipient of foreign capital. The dual increases in outward and inward direct investment signal a period of heightened economic activity and confidence among multinational enterprises (MNEs). This trend reflects a broader global economic recovery and a renewed focus on strategic investments in key industries and geographic regions. The data provides crucial insights into the economic strategies of U.S. corporations and international firms, highlighting their confidence in the long-term prospects of both domestic and international markets.
U.S. Direct Investment Abroad: Expanding Global Footprint
U.S. multinational enterprises demonstrated a significant appetite for overseas ventures in 2025, with their cumulative direct investment abroad reaching an impressive $7.14 trillion. This represents a notable increase of $438.1 billion compared to the preceding year. The geographical distribution of this outward investment reveals a strong preference for European markets, which accounted for the largest portion of the growth, adding $350.2 billion to the overall position. Within Europe, the United Kingdom and Luxembourg stood out as particularly attractive investment hubs.
By industry, manufacturing emerged as the leading sector for U.S. MNEs looking to expand their global reach. This sector saw the most substantial increase, with chemical manufacturing specifically driving this upward trend. This suggests a strategic focus on bolstering supply chains, accessing new markets for chemical products, and potentially leveraging production efficiencies in overseas locations.
Key Destinations for U.S. Outward Investment:
While U.S. MNEs invest in a vast array of countries, a significant portion of their direct investment abroad is concentrated in a few key economies. In 2025, over half of the total U.S. direct investment abroad was situated in five countries:
- United Kingdom: This remained the top destination, with a cumulative investment position of $1,114.7 billion.
- Netherlands: Following closely, the Netherlands held a position of $1,044.0 billion.
- Luxembourg: This financial hub continued to attract substantial U.S. investment, reaching $645.3 billion.
- Ireland: With a position of $511.9 billion, Ireland demonstrated its importance as an investment location.
- Canada: Proximity and strong economic ties maintained Canada’s position as a major recipient of U.S. direct investment, totaling $488.1 billion.
The concentration of investment in these countries underscores their roles as established centers for international business, financial services, and strategic market access for U.S. corporations.
Industry Breakdown of U.S. Outward Investment:
When examining the investment by the industry of the directly owned foreign affiliate, a clear pattern emerges:
- Holding Companies: These entities accounted for the largest share of the overall U.S. investment position abroad in 2025, representing 45.8 percent. This indicates a strategic use of holding companies for managing international assets, facilitating intra-company financial flows, and potentially optimizing tax structures.
- Manufacturing Affiliates: Ranking second, manufacturing accounted for 15.9 percent of U.S. outward investment. This reinforces the earlier observation about the manufacturing sector’s prominence.
- Finance and Insurance Affiliates: This sector comprised the third-largest share, at 13.5 percent, highlighting the continued importance of financial services in global U.S. investment strategies.
Furthermore, analyzing the investment by the industry of the U.S. parent company reveals that MNEs engaged in manufacturing were the most active in overseas investments, contributing 50.2 percent of the total position. MNEs in the finance and insurance sectors followed, representing 15.8 percent of the outward investment. This dual perspective—examining both the foreign affiliate’s industry and the U.S. parent’s industry—provides a more nuanced understanding of the motivations and structures behind U.S. direct investment abroad.
Income Generated from Overseas Investments:
In 2025, U.S. MNEs generated substantial income from their cumulative investments abroad. The total income earned reached $660.1 billion, marking an 11.1 percent increase from the previous year. The most significant growth in income was observed in holding companies, which saw an increase of $40.0 billion. Conversely, income derived from finance and insurance affiliates experienced a decline of $6.3 billion compared to 2024, suggesting potential shifts in market dynamics or profitability within that specific sector.
Foreign Direct Investment in the United States: A Magnet for Global Capital
The United States continued to be a prime destination for foreign investors in 2025, with foreign direct investment in the U.S. increasing by $266.0 billion to reach a total position of $5.86 trillion. Mirroring the trend in U.S. outward investment, Europe was also the leading source of this inbound capital, contributing an additional $182.4 billion to the overall position.
Key Sources of Foreign Investment:
When analyzed by the country of the foreign parent, four nations accounted for more than half of the total FDI in the United States:
- Japan: Emerged as the top investing country, with a position of $776.3 billion.
- Netherlands: Held the second-largest position at $751.8 billion.
- Canada: Demonstrated strong investment ties, with a position of $747.3 billion.
- United Kingdom: Continued to be a significant investor, with a position of $738.3 billion.
Ultimate Beneficial Owner (UBO) Perspective:
A deeper analysis, considering the country of the ultimate beneficial owner (UBO)—the entity at the apex of the global ownership chain—provides a more refined view of investment origins. On a UBO basis, Japan remained the top investing country with $827.1 billion. Canada followed with $819.8 billion, and Germany secured the third position with $706.2 billion. Notably, the UBO data revealed that investment originating from the Netherlands and Luxembourg was considerably lower than indicated by the country of foreign parent. This suggests that a substantial portion of investment channeled through these European financial centers was ultimately owned by investors in other countries, highlighting the role of these nations as conduits for international capital.
Industry Concentration of FDI in the U.S.:
The U.S. manufacturing sector attracted the largest share of foreign direct investment in 2025, accounting for 42.8 percent of the total position. This significant inflow amounted to $2.51 trillion. Within manufacturing, chemical manufacturing was a particularly strong recipient, capturing one-third of this total, or $835.9 billion. Beyond manufacturing, substantial foreign investment was also directed towards the finance and insurance sectors ($629.7 billion) and wholesale trade ($534.0 billion).
Income Generated by Foreign Investors in the U.S.:
Foreign MNEs earned $310.1 billion in income from their cumulative investments in the United States during 2025. This figure represents a slight decrease of 1.9 percent compared to the income reported in 2024, suggesting a moderation in the profitability of foreign-owned enterprises operating within the U.S. economy during the period.
Historical Context and Revisions
The release of the 2025 data also includes revisions to previously published statistics for 2022, 2023, and 2024. These revisions are standard practice in economic data reporting, allowing for the incorporation of newly available and more comprehensive source data. For instance, U.S. direct investment abroad data for 2023 and 2024 has been revised, as has foreign direct investment in the United States data for 2022 through 2024. These adjustments ensure the accuracy and reliability of the economic indicators used by policymakers, businesses, and researchers. The table below summarizes these key revisions:
| Year | U.S. Direct Investment Abroad (Billions of dollars) | Foreign Direct Investment in the United States (Billions of dollars) | ||
|---|---|---|---|---|
| Previously Published | Revised | Previously Published | Revised | |
| 2022 | …. | …. | 5,124 | 5,110 |
| 2023 | 6,620 | 6,598 | 5,376 | 5,338 |
| 2024 | 6,827 | 6,698 | 5,708 | 5,598 |
Note: U.S. direct investment abroad data not revised for 2022.
These revisions, though often minor in percentage terms, are crucial for understanding long-term trends and for making informed economic decisions. They reflect the dynamic nature of data collection and analysis, particularly in complex areas like international investment flows.
Implications and Broader Economic Impact
The robust growth in both U.S. outward investment and foreign direct investment in the United States in 2025 signals a healthy global economic environment and a strong confidence in the stability and future growth prospects of the U.S. economy. For the United States, increased FDI contributes to job creation, technological advancement, and economic output. It also signifies the nation’s continued appeal as a stable and lucrative market for international businesses.
The significant investment in U.S. manufacturing, particularly in sectors like chemicals and electrical equipment, suggests a strategic interest in strengthening domestic production capabilities and supply chains. This could have positive implications for U.S. industrial competitiveness and resilience. Simultaneously, the expansion of U.S. investment abroad, especially in manufacturing and financial services, points to a strategy of global market penetration, access to new technologies, and diversification of business operations.
The BEA’s commitment to providing detailed data, including breakdowns by country and industry, as well as the distinction between foreign parent and ultimate beneficial owner, is invaluable. This granular information allows for a deeper understanding of the complex web of international investment and its drivers. As the global economic landscape continues to evolve, these statistics will serve as critical benchmarks for assessing economic health, policy effectiveness, and future investment trends. The BEA’s ongoing updates and the introduction of new disclosure avoidance methods, such as coarsening, aim to enhance the availability of granular data while maintaining respondent confidentiality, further enriching the public’s understanding of these vital economic flows. The next release of Direct Investment by Country and Industry is anticipated in July 2027, covering data for 2026.