

 Lina Irawan
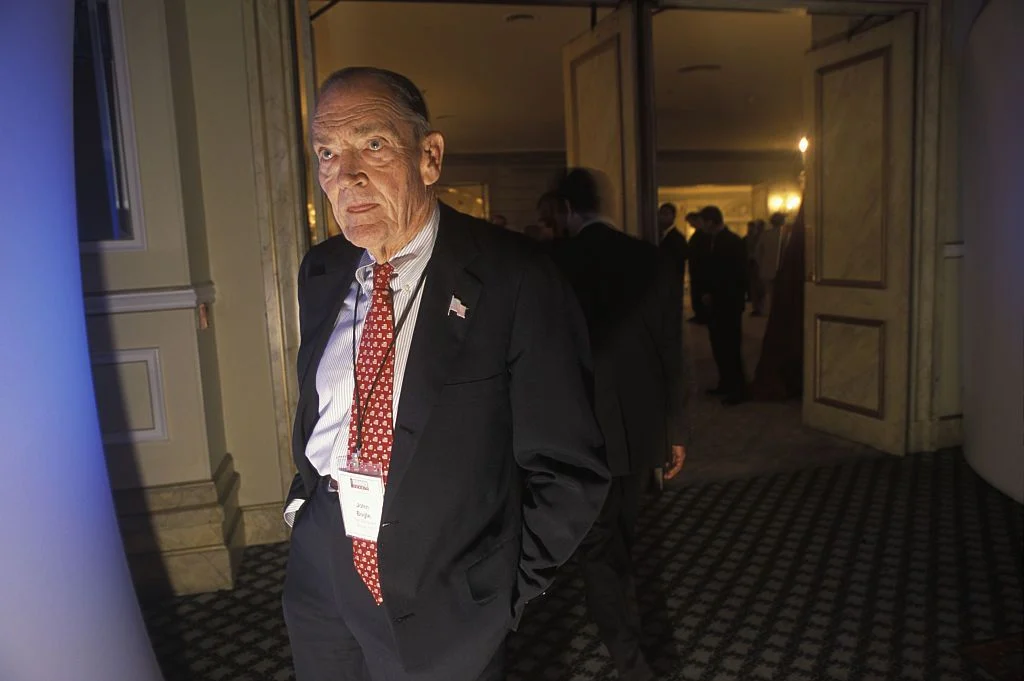
For many individuals approaching their fifties, the landscape of personal finance often shifts from aggressive growth to prudent preservation and strategic accumulation, with an acute awareness of impending retirement. In this crucial phase, the timeless principles championed by Vanguard founder Jack Bogle—a titan of modern investing—offer a clear, unshakeable path to financial security. Bogle’s philosophy, rooted in simplicity, cost-efficiency, and long-term discipline, provides a compelling alternative to the often-overwhelming complexities of active trading and market speculation, proving particularly relevant for those seeking to safeguard and grow their nest egg without taking undue risks.
The Genesis of Simplicity: Jack Bogle’s Vision
John C. "Jack" Bogle (1929-2019) was a revolutionary figure in the financial world, best known for founding The Vanguard Group in 1975 and creating the first index fund available to individual investors. His vision was born out of a deep-seated belief that active money management, with its high fees and frequent trading, consistently failed to outperform the broader market over the long term. Bogle advocated for a common-sense approach: instead of trying to beat the market, simply own the market. This philosophy, initially met with skepticism and even derision from Wall Street, has since become a cornerstone of modern financial planning, influencing generations of investors and fundamentally reshaping the investment industry. For individuals in their fifties, Bogle’s tenets are not just theoretical guidelines but practical imperatives, offering a roadmap to minimize pitfalls and maximize the potential of their remaining working years to build wealth.
I. Embracing the Haystack: The Power of Broad Market Indexing
Bogle famously advised investors to "own the haystack, not search for the needle." This metaphor succinctly captures the essence of index investing. Rather than attempting the arduous and often fruitless task of identifying a handful of "winner" stocks that will significantly outperform, index investors opt to own a diversified portfolio that mirrors the performance of an entire market segment, such as the S&P 500.
The S&P 500, for instance, represents 500 of the largest publicly traded companies in the United States, spanning various sectors. Investing in an S&P 500 index fund or exchange-traded fund (ETF) provides immediate diversification across these market leaders. Historically, the S&P 500 has delivered an average annual return of approximately 10% over many decades, including reinvested dividends. This long-term average has proven robust enough to outpace inflation and facilitate substantial wealth accumulation.
A Deeper Dive into Diversification and Risk Mitigation
For investors in their fifties, diversification is paramount. At this stage, capital preservation becomes as critical as growth. A portfolio concentrated in a few individual stocks, no matter how promising they appear, carries inherent idiosyncratic risk—the risk specific to a particular company or industry. A single negative event, such as a product recall, a regulatory fine, or a shift in consumer preference, can significantly impair the value of such concentrated holdings.
In contrast, an index fund inherently mitigates this risk. While individual companies within the S&P 500 may falter, the overall index is designed to reflect the aggregate performance of the U.S. economy. Underperforming companies are eventually replaced by emerging leaders, ensuring the index remains relevant and robust. This automatic rebalancing and broad exposure significantly reduce the likelihood of catastrophic losses that could jeopardize retirement plans. The stability offered by broad market exposure allows investors to capture market gains with reduced volatility compared to a stock-picking strategy.
The Evidence Against Active Management
Numerous studies, including the widely cited S&P Dow Jones Indices SPIVA® (S&P Index Versus Active) U.S. Scorecard, consistently demonstrate that the vast majority of actively managed funds fail to outperform their respective benchmarks over extended periods, particularly 5, 10, or 15 years. This underperformance is often attributed to higher fees, trading costs, and the inherent difficulty of consistently timing the market or picking winning stocks. For an investor nearing retirement, relying on an active manager who may or may not beat the market adds an unnecessary layer of uncertainty and cost, potentially eroding precious savings.
II. The Tyranny of Costs: Minimizing Expense Ratios and Fees
Bogle’s second core principle, "keep costs low," is arguably the most impactful for long-term investors. Fees, seemingly minor in isolation, exert a compounding negative effect on portfolio returns over decades. Expense ratios, trading commissions, and advisory fees can quietly—and significantly—chip away at an investor’s net worth, often without them fully realizing the long-term damage.
Understanding the Impact of Fees
Consider a hypothetical portfolio of $1 million. An actively managed mutual fund with a 1% annual expense ratio would cost an investor $10,000 per year. Over 20 years, assuming a modest 7% annual return before fees, those fees alone would amount to hundreds of thousands of dollars in lost wealth, not just from the direct fee payments but also from the lost compounding on those fees.
In stark contrast, many broad market index funds boast expense ratios as low as 0.03% to 0.10%. For the same $1 million portfolio, a 0.10% expense ratio translates to just $1,000 in annual fees. This seemingly small difference of 0.9% compounded over two decades can easily amount to a difference of several hundred thousand dollars in favor of the lower-cost fund. For someone in their fifties, with potentially 15-20 years of pre-retirement accumulation and then 20-30 years of retirement drawdowns, minimizing these frictional costs is absolutely vital to ensuring their savings last.
The Cost Advantage of Index Funds
Index funds are inherently cheaper to operate than actively managed funds. They do not require extensive research teams, high-frequency trading, or complex analytical models. Their strategy is simply to replicate an index, which is a rules-based and often automated process. This operational efficiency translates directly into lower expense ratios for investors. Moreover, index funds typically have lower portfolio turnover, meaning fewer trades, which results in lower trading costs and potentially more tax efficiency for investors in taxable accounts.
The financial industry, initially resistant to Bogle’s low-cost model, has gradually been compelled to adapt. The proliferation of low-cost index funds and ETFs has put downward pressure on fees across the board, benefiting all investors. However, vigilance is still required to ensure one’s investments are not silently eroded by excessive charges.
III. Navigating the Storm: The Discipline of Staying the Course
"Stay the course through market noise" encapsulates Bogle’s unwavering commitment to long-term discipline and his strong opposition to market timing. The financial news cycle is rife with predictions of impending booms and busts, creating an environment ripe for emotional decision-making. Investors, especially those nearing retirement, can be particularly susceptible to the fear of missing out (FOMO) during rallies or panic selling during downturns.
The Perils of Market Timing
Attempting to time the market—buying low and selling high—is an exceedingly difficult, if not impossible, endeavor to do consistently. Research consistently shows that even professional money managers struggle to time market entries and exits effectively. Investors who chase "soaring stocks" during a rally often end up buying at elevated prices, only to sell at a loss when the rally inevitably fades or a correction occurs. This speculative behavior is not only financially costly due to transaction fees and potential capital losses but also emotionally draining.
For an investor in their fifties, the stakes are even higher. A significant market loss close to retirement leaves less time for the portfolio to recover. Younger investors have the luxury of decades for market fluctuations to average out, but pre-retirees have a shorter runway. Therefore, maintaining a steady, disciplined approach, rather than reacting to every headline, is crucial.
Dollar-Cost Averaging as a Counter-Strategy
A cornerstone of "staying the course" is dollar-cost averaging. This strategy involves investing a fixed amount of money at regular intervals (e.g., monthly) regardless of market conditions. When prices are high, the fixed amount buys fewer shares; when prices are low, it buys more. Over time, this averages out the purchase price and removes the emotional element from investing. Many index investors automate these transfers, ensuring consistent contributions and eliminating the temptation to try and predict market movements. This steady, unemotional approach allows investors to benefit from market recoveries without the stress and potential losses associated with active trading.
IV. Age-Appropriate Allocation: Balancing Risk and Return
As investors age, their financial circumstances and risk tolerance naturally evolve. While growth remains important, the emphasis gradually shifts towards capital preservation and income generation. Bogle understood this dynamic and advocated for an age-based asset allocation strategy that adjusts the proportion of stocks to bonds in a portfolio.
The Role of Stocks and Bonds
Stocks, while offering higher growth potential over the long term, are inherently more volatile. Bonds, on the other hand, generally offer lower returns but provide greater stability, income, and diversification, particularly during stock market downturns. For someone in their fifties, a portfolio consisting solely of stocks might be too aggressive, exposing them to significant fluctuations just as they need their capital most.
Guidelines for Asset Allocation
A commonly cited rule of thumb, sometimes attributed to Bogle, suggests subtracting your age from 120 (or 110, or 100, depending on the variant) to determine the percentage of your portfolio that should be allocated to stocks. For example, a 55-year-old using the "120 minus age" rule would allocate 65% (120 – 55 = 65) to stocks and the remaining 35% to bonds. This framework suggests a gradual reduction in stock exposure and an increase in bond exposure as one approaches and enters retirement.
It is crucial to remember that these are general guidelines, not rigid rules. Individual circumstances, such as health status, other income sources (e.g., pensions, social security), family obligations, and personal risk tolerance, should all factor into the final asset allocation decision. A person with a secure pension and excellent health might comfortably maintain a higher stock allocation than someone relying entirely on their investment portfolio with potential health concerns.
The Importance of Rebalancing
Regardless of the chosen allocation, periodic rebalancing is essential. Over time, market movements can cause the portfolio’s actual allocation to drift from its target. For example, if stocks perform exceptionally well, their percentage in the portfolio might exceed the target. Rebalancing involves selling a portion of the overperforming asset (e.g., stocks) and buying more of the underperforming asset (e.g., bonds) to restore the desired allocation. This disciplined process helps maintain the intended risk level and ensures the portfolio remains aligned with the investor’s changing time horizon and goals.
Broader Implications and Enduring Legacy
Jack Bogle’s principles have profoundly influenced the financial industry. His advocacy for the common investor sparked a revolution that led to the widespread availability of low-cost investment products, forcing traditional active managers to justify their higher fees. His work has been lauded by countless financial experts, including Warren Buffett, who often recommended index funds for most investors.
For those in their fifties, Bogle’s legacy is particularly powerful. It offers a counter-narrative to the often-intimidating world of finance, empowering individuals to take control of their financial future through simple, proven methods. By focusing on broad market exposure, minimizing costs, maintaining discipline, and adjusting risk appropriately with age, investors can build a resilient portfolio capable of supporting a comfortable retirement. In an era of increasing financial complexity, Bogle’s enduring wisdom provides a refreshing and effective roadmap to long-term financial success, proving that sophisticated returns often come from refreshingly simple strategies.








