Lana Rhoades
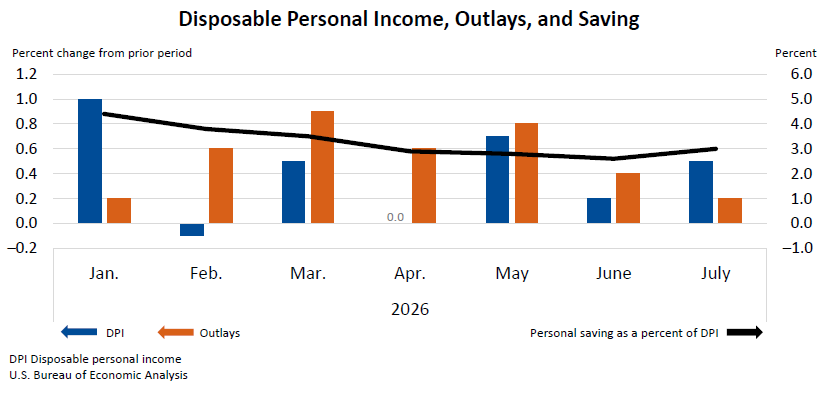
Personal income in the United States experienced a notable increase in July, climbing by $115.1 billion, or 0.4 percent on a monthly basis, according to the latest estimates from the U.S. Bureau of Economic Analysis (BEA). This growth in overall income outpaced the rise in personal consumption expenditures (PCE), a key indicator of consumer spending. Disposable personal income (DPI), which represents personal income after taxes, saw a more substantial jump of $125.9 billion, a 0.5 percent increase, signaling a potentially stronger financial position for households.
The BEA’s report, released on [Insert Date of BEA Release, e.g., August 30, 2026], painted a picture of a moderately expanding economy where income growth is outstripping the pace of consumer outlays. Personal consumption expenditures, which encompass spending on goods and services, rose by $36.3 billion, a more modest 0.2 percent increase. This divergence suggests that consumers, while continuing to spend, are also accumulating a larger portion of their income.
Key Economic Indicators for July
The figures released by the BEA provide a granular look at the financial health of American households.
- Personal Income: Increased by $115.1 billion (0.4 percent). This marks a steady upward trend, reflecting broad-based economic activity.
- Disposable Personal Income (DPI): Saw a significant rise of $125.9 billion (0.5 percent). This indicates that after tax obligations, consumers had more money at their disposal.
- Personal Consumption Expenditures (PCE): Grew by $36.3 billion (0.2 percent). This suggests a more cautious approach to spending or a shift in spending patterns.
- Personal Outlays: The sum of PCE, personal interest payments, and personal current transfer payments, increased by $36.6 billion. This figure is closely aligned with PCE, indicating that interest payments and transfers had a minimal impact on overall spending growth.
- Personal Saving: Stood at $712.0 billion in July. This substantial figure reflects the growing gap between income and spending.
- Personal Saving Rate: Ticked up to 3.0 percent of disposable personal income. This rate, while still historically moderate, shows an increase in the proportion of income being saved by individuals.
Drivers of Income Growth
The uptick in current-dollar personal income during July was primarily attributed to several key factors:
- Compensation: This broad category, which includes wages, salaries, and benefits, saw an increase. This suggests a healthy labor market with consistent wage growth and potentially expanding employment. The BEA’s technical notes indicate that revisions to compensation estimates were influenced by updated data from the U.S. Bureau of Labor Statistics (BLS) on employment, hours, and earnings, reflecting the latest available information.
- Government Social Benefits: A rise in government social benefits contributed to the overall income growth. This could encompass a range of programs, including social security, unemployment insurance, and other forms of public assistance. Revised information from the Centers for Medicare & Medicaid Services also played a role in the updated estimates for Medicaid benefits.
- Personal Income Receipts on Assets: Income generated from investments, such as dividends, interest, and capital gains, also saw an increase. This component of income can be sensitive to market performance and prevailing interest rates.
Consumer Spending Patterns: A Tale of Two Sectors
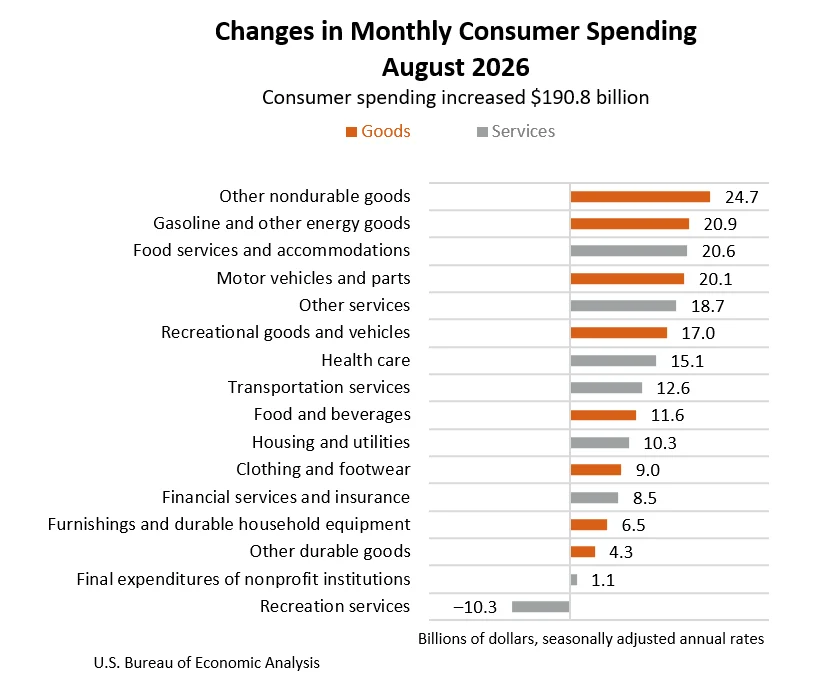
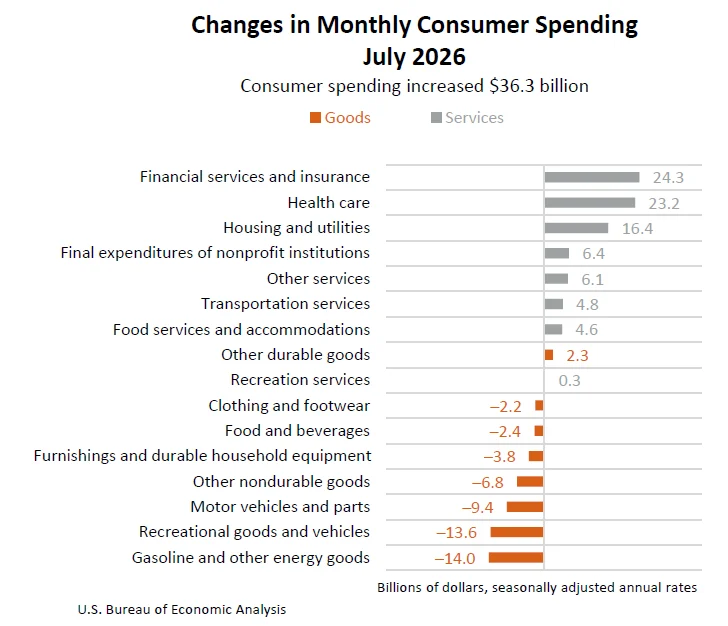
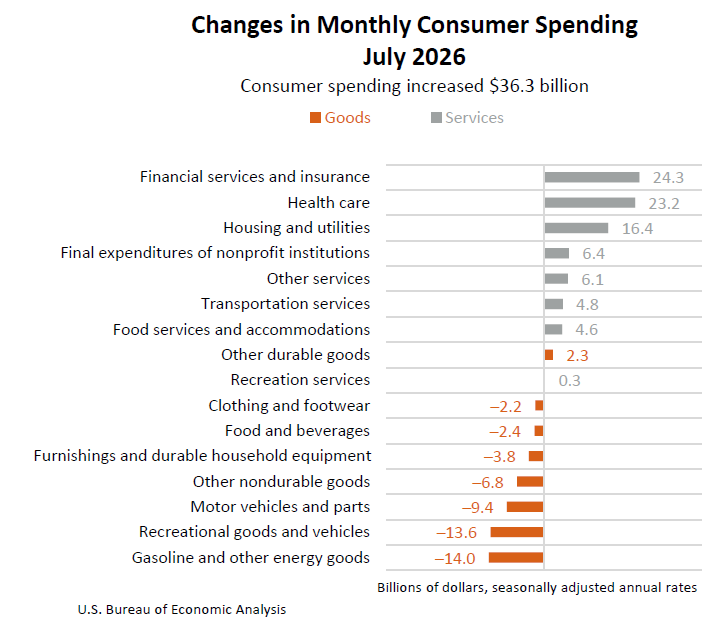
The moderate growth in personal consumption expenditures (PCE) in July was characterized by divergent trends in spending on goods and services. While overall PCE increased by $36.3 billion, this figure masks a significant shift in consumer behavior.
Spending on services surged by $86.2 billion. This robust increase suggests that consumers are allocating a larger portion of their discretionary funds towards services, which can include everything from dining out and travel to healthcare and entertainment. This trend has been a notable feature of the post-pandemic economic recovery, as individuals prioritize experiences and services they may have foregone during periods of stricter health measures.
Conversely, spending on goods experienced a decrease of $49.9 billion. This contraction in spending on tangible items could indicate several things: a potential saturation of demand for certain goods after a period of increased purchasing, a shift in consumer priorities towards services, or perhaps a response to inflationary pressures on goods. The BEA’s data on PCE by major type of product will offer further insights into which specific categories of goods saw the most significant declines.
Real Consumption and Inflationary Pressures
When adjusted for inflation, the picture of consumer spending becomes even clearer. Real PCE, which measures the actual volume of goods and services consumed, increased by a marginal $1.3 billion, or less than 0.1 percent at a monthly rate. This minimal growth in real terms, despite nominal increases in spending, highlights the impact of inflation on purchasing power. Consumers are spending more dollars, but the quantity of goods and services they are able to purchase has remained relatively stagnant.
The PCE price index, a key measure of inflation for consumer spending, increased by 0.2 percent in July compared to the previous month. Crucially, this inflation rate remained consistent even when excluding the volatile categories of food and energy, indicating broad-based price pressures across the economy.
On an annual basis, the PCE price index for July showed a more significant increase of 3.7 percent compared to the same month in the prior year. The core PCE price index (excluding food and energy) also saw a substantial year-over-year increase of 3.3 percent. These figures suggest that while monthly inflation may be moderating, the cumulative effect of price increases over the past year continues to be a significant factor for consumers. The persistent inflation, even in core categories, underscores the challenges faced by households in maintaining their purchasing power, even as incomes rise.
Background and Context: A Shifting Economic Landscape
The July data arrives amidst a complex economic environment. Following a period of robust post-pandemic recovery, the U.S. economy has been navigating the dual challenges of persistent inflation and a tightening monetary policy by the Federal Reserve. The BEA’s monthly Personal Income and Outlays report is a critical tool for economists, policymakers, and businesses to gauge the health of the consumer, which is a primary driver of U.S. economic activity.
The BEA’s release also serves as a prelude to its upcoming Annual Update of the National and Regional Economic Accounts, scheduled for September 30, 2026. This comprehensive update will incorporate revised data for GDP, gross domestic income, and various other economic indicators, providing a more refined understanding of economic performance over the past year. The concurrent release of national, industry, and regional data is a new initiative aimed at improving the timeliness and consistency of BEA’s statistical products.
Analysis and Implications
The divergence between income growth and spending growth in July suggests several potential implications for the broader economy.
Increased Savings Capacity: The higher personal saving rate indicates that households are building their financial reserves. This could lead to increased consumer confidence and a potential boost to future spending, especially if inflation continues to moderate. Alternatively, it could signal consumer caution in the face of economic uncertainty.
Impact of Inflation on Real Consumption: The minimal increase in real PCE, despite nominal spending growth, underscores the erosive effect of inflation on consumer purchasing power. Even with rising incomes, households may feel they are not getting ahead if prices continue to climb at a faster pace. This can influence consumer behavior, leading to prioritization of essential spending and a pullback on discretionary purchases.
Sectoral Shifts in Spending: The strong performance of services spending relative to goods suggests a potential long-term shift in consumer preferences. As the economy matures and experiences normalize, consumers may continue to prioritize experiences and services over the acquisition of physical goods. This has implications for businesses in both sectors, requiring strategic adjustments to meet evolving demand.
Monetary Policy Considerations: The Federal Reserve closely monitors PCE price index data for insights into inflationary pressures. The continued rise in the PCE price index, particularly the core measure, may reinforce the Fed’s stance on maintaining a restrictive monetary policy to bring inflation back to its target. However, the moderating nominal spending growth might offer some reassurance that the economy is not overheating.
Official Statements and Reactions (Inferred)
While direct statements from officials are not provided in the source material, the BEA’s release itself serves as an official communication of economic conditions. Economists and market analysts are likely to interpret these figures as a sign of a resilient but moderating economy.
- BEA Commentary: The BEA’s technical notes and descriptions of the data provide an objective overview of the trends. The emphasis on revisions to compensation and government benefits highlights the data refinement process and the factors driving income growth.
- Potential Market Reaction: Investors and financial markets would be closely observing these figures. A strong income growth coupled with moderate spending and persistent inflation presents a mixed picture that could influence market sentiment and investment strategies.
Looking Ahead: The August Data and Beyond
The BEA announced that the next release of Personal Income and Outlays data, covering August 2026, is scheduled for September 30, 2026, at 8:30 a.m. EDT. This upcoming report will provide further insights into whether the trends observed in July – income growth outpacing spending and persistent inflation – continue or if there are shifts in consumer behavior and price pressures.
The ongoing annual updates to the National and Regional Economic Accounts will also offer a more comprehensive and revised picture of the U.S. economy. These updates are crucial for understanding the long-term trajectory of economic growth, inflation, and consumer financial health.
The data presented for July offers a snapshot of an economy grappling with inflation while demonstrating underlying strength in income generation. The interplay between rising incomes, cautious consumer spending, and persistent price pressures will continue to be a critical focus for economic analysis and policy decisions in the months to come. The ability of households to maintain their purchasing power while saving for the future will be a key determinant of the nation’s economic trajectory.