Lana Rhoades
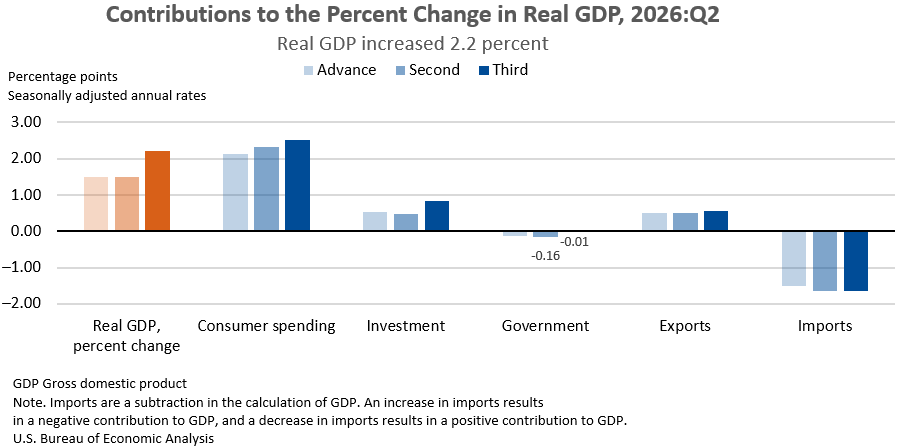
The United States economy demonstrated robust growth in the second quarter of 2026, with real gross domestic product (GDP) expanding at an annual rate of 2.2 percent. This upward revision, the third estimate from the U.S. Bureau of Economic Analysis (BEA), signifies a strengthening economic momentum compared to the 2.5 percent increase observed in the first quarter. The latest figures reflect a significant upward adjustment of 0.7 percentage point from the second estimate, primarily fueled by stronger-than-anticipated contributions from investment, consumer spending, and government expenditures. This revised growth rate underscores the economy’s capacity to absorb various economic pressures and maintain a steady expansionary path.
The BEA’s comprehensive analysis, released on September 26, 2026, highlights that the upward revisions were particularly pronounced in key sectors. Investment, a critical driver of long-term economic health, saw a notable increase, indicating heightened business confidence and a willingness to allocate capital towards future growth. Consumer spending, the bedrock of the U.S. economy, also contributed significantly, demonstrating sustained household demand. Furthermore, government spending, which can play a crucial role in stabilizing and stimulating economic activity, added to the positive growth trajectory.
Key Drivers of Second-Quarter Growth
The increase in real GDP during the second quarter was propelled by a combination of factors. Consumer spending, as always, played a pivotal role, reflecting the purchasing power and confidence of American households. Investment, encompassing both business fixed investment and residential investment, also provided a substantial boost, signaling a healthy appetite for expansion and innovation within the corporate sector. Exports, a vital component of GDP that represents goods and services sold to foreign buyers, also contributed positively to the growth figures. Conversely, imports, which represent spending on foreign goods and services by domestic consumers and businesses and are subtracted in GDP calculations, also saw an increase. This rise in imports, while a subtraction from GDP, can also indicate robust domestic demand and economic activity.
Industry-Level Performance and Sectoral Contributions
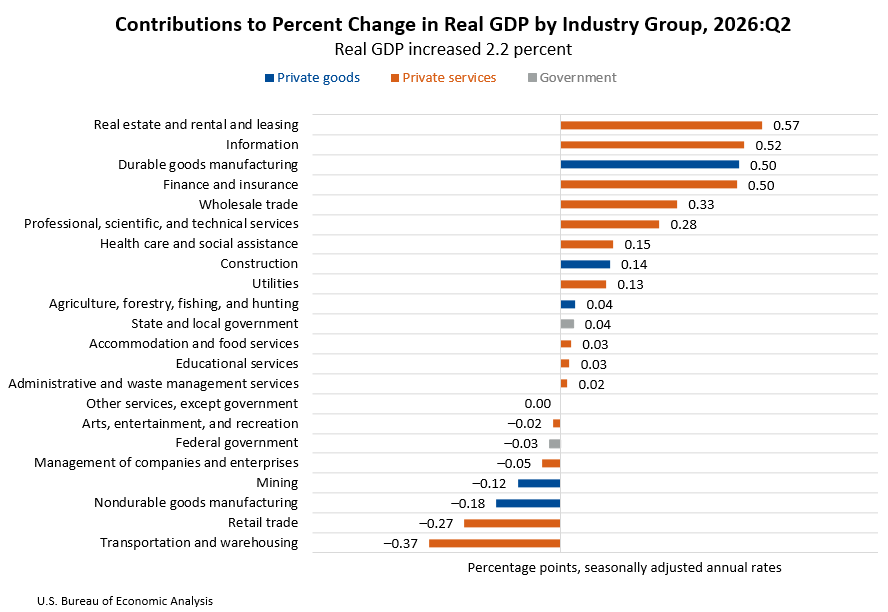
A deeper dive into industry-specific data reveals a broad-based expansion across various sectors of the economy. Real value added for private services-producing industries grew by an impressive 2.5 percent, underscoring the continued dominance of the service sector in driving economic output. Private goods-producing industries also exhibited healthy growth, with real value added increasing by 2.3 percent, suggesting a strong performance in manufacturing and construction. Government sectors contributed positively, albeit at a more modest rate of less than 0.1 percent.
Several industries stood out as leading contributors to the overall increase in real GDP. The real estate and rental and leasing sector demonstrated significant strength, likely reflecting a dynamic housing market and robust commercial property activity. The information sector also showed strong performance, indicative of the ongoing digital transformation and the growing importance of data and technology-driven services. Durable goods manufacturing and the finance and insurance sectors also played key roles in bolstering GDP growth, signaling healthy activity in capital goods production and financial markets.
However, the growth was not uniform across all industries. Offsetting these gains were decreases in certain sectors, notably transportation and warehousing, retail trade, and nondurable goods manufacturing. These declines may reflect shifts in consumer behavior, supply chain adjustments, or sector-specific challenges that warrant further monitoring.
Broader Economic Indicators and Revisions
Beyond the headline GDP figures, several other economic measures provide a more nuanced picture of the second quarter’s performance. Real final sales to private domestic purchasers, a key indicator of underlying domestic demand excluding inventories and net exports, increased by a robust 4.6 percent. This upward revision of 0.4 percentage point from the previous estimate further solidifies the narrative of strong consumer and business spending.
Real gross output, which measures the total value of goods and services produced by all sectors of the economy, also experienced a significant increase of 5.0 percent. This expansion was driven by strong growth in private services-producing industries (6.0 percent), private goods-producing industries (3.0 percent), and government (2.6 percent).
Real gross domestic income (GDI), an alternative measure of economic activity that reflects income generated by production, increased by 2.6 percent. This represents an upward revision of 0.4 percentage point from the prior estimate. The BEA also reported the average of real GDP and real GDI, which increased by 2.4 percent, an upward revision of 0.6 percentage point. This convergence of GDP and GDI provides a more stable and comprehensive view of economic growth.
Corporate profits from current production, a key measure of business profitability, also saw a substantial increase of $384.0 billion. While this represents a downward revision of $16.9 billion from the previous estimate, it still indicates a healthy environment for corporate earnings.
Inflationary pressures, as measured by the price index for gross domestic purchases, increased by 5.6 percent in the second quarter, a downward revision of 0.2 percentage point. The personal consumption expenditures (PCE) price index, a closely watched inflation gauge, rose by 5.0 percent, also revised down by 0.3 percentage point. The core PCE price index, which excludes volatile food and energy prices, increased by 3.3 percent, a downward revision of 0.3 percentage point. These downward revisions in inflation indicators suggest that while price pressures remain, they may be moderating more than initially anticipated.
State-Level Economic Performance
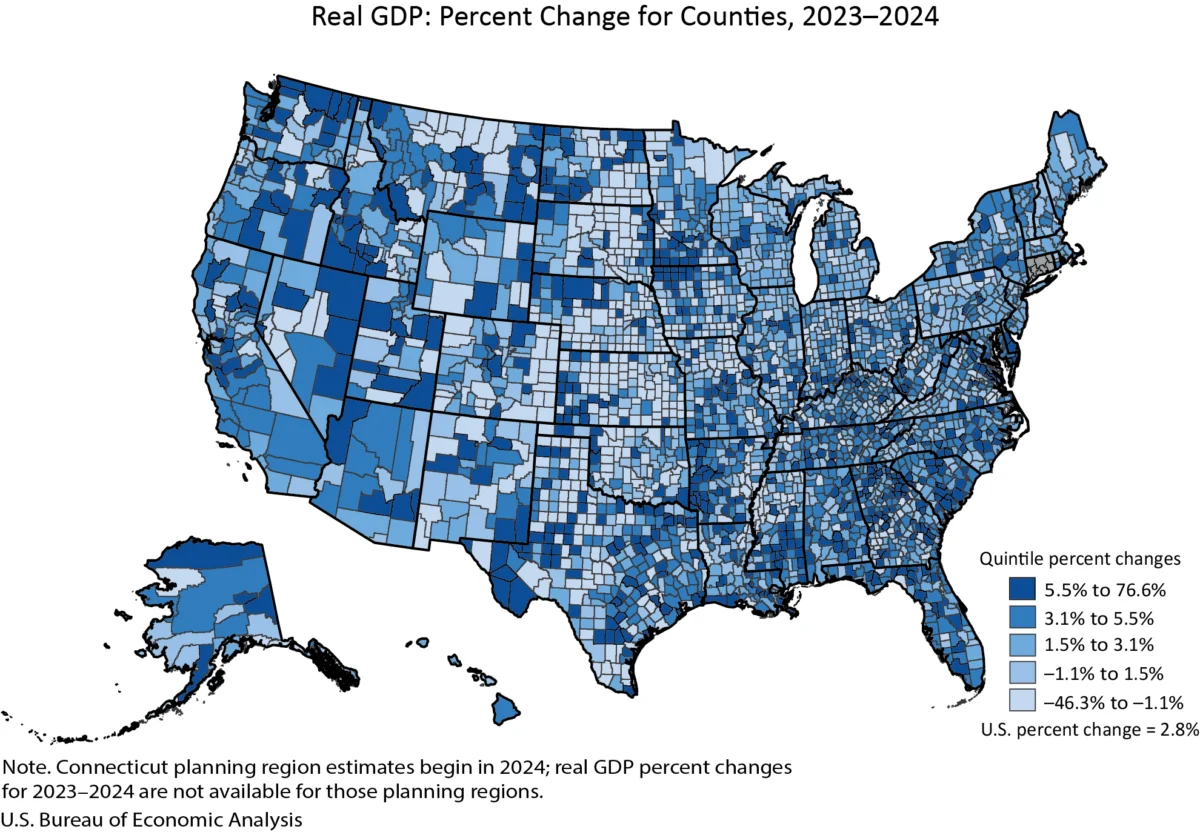
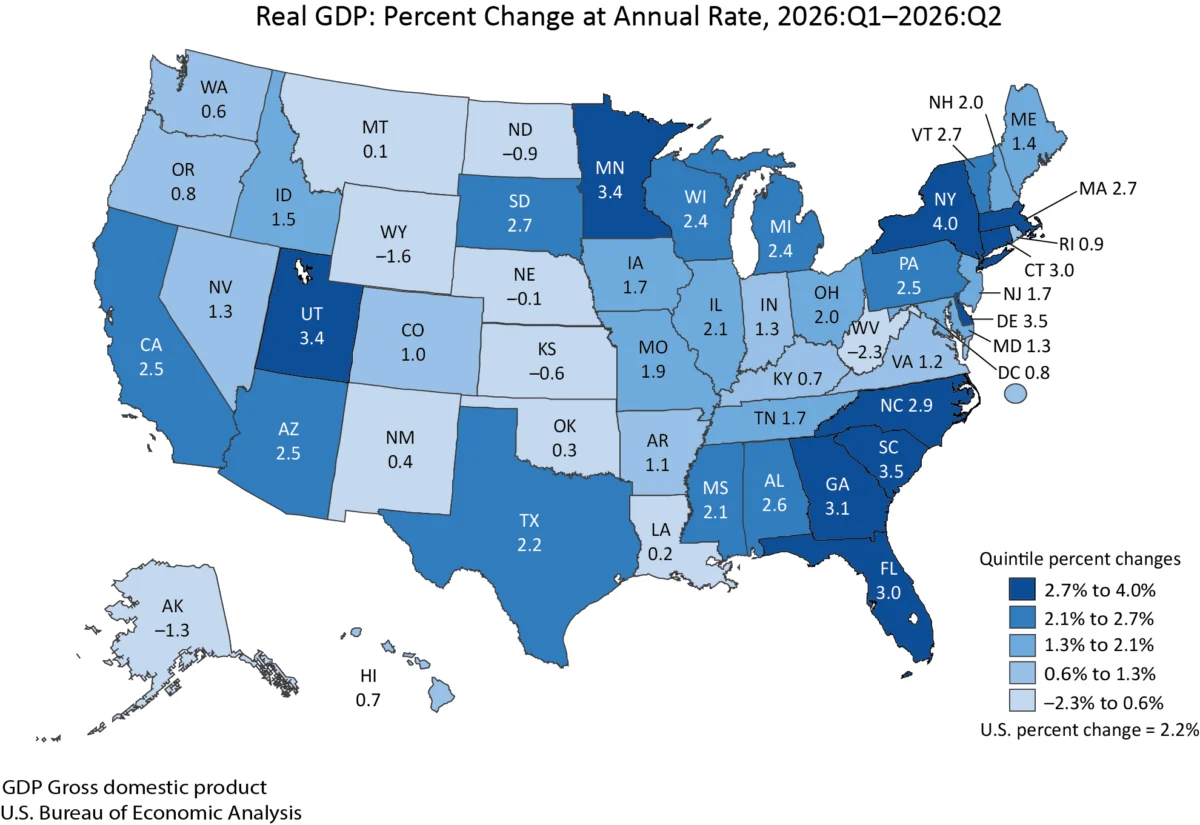
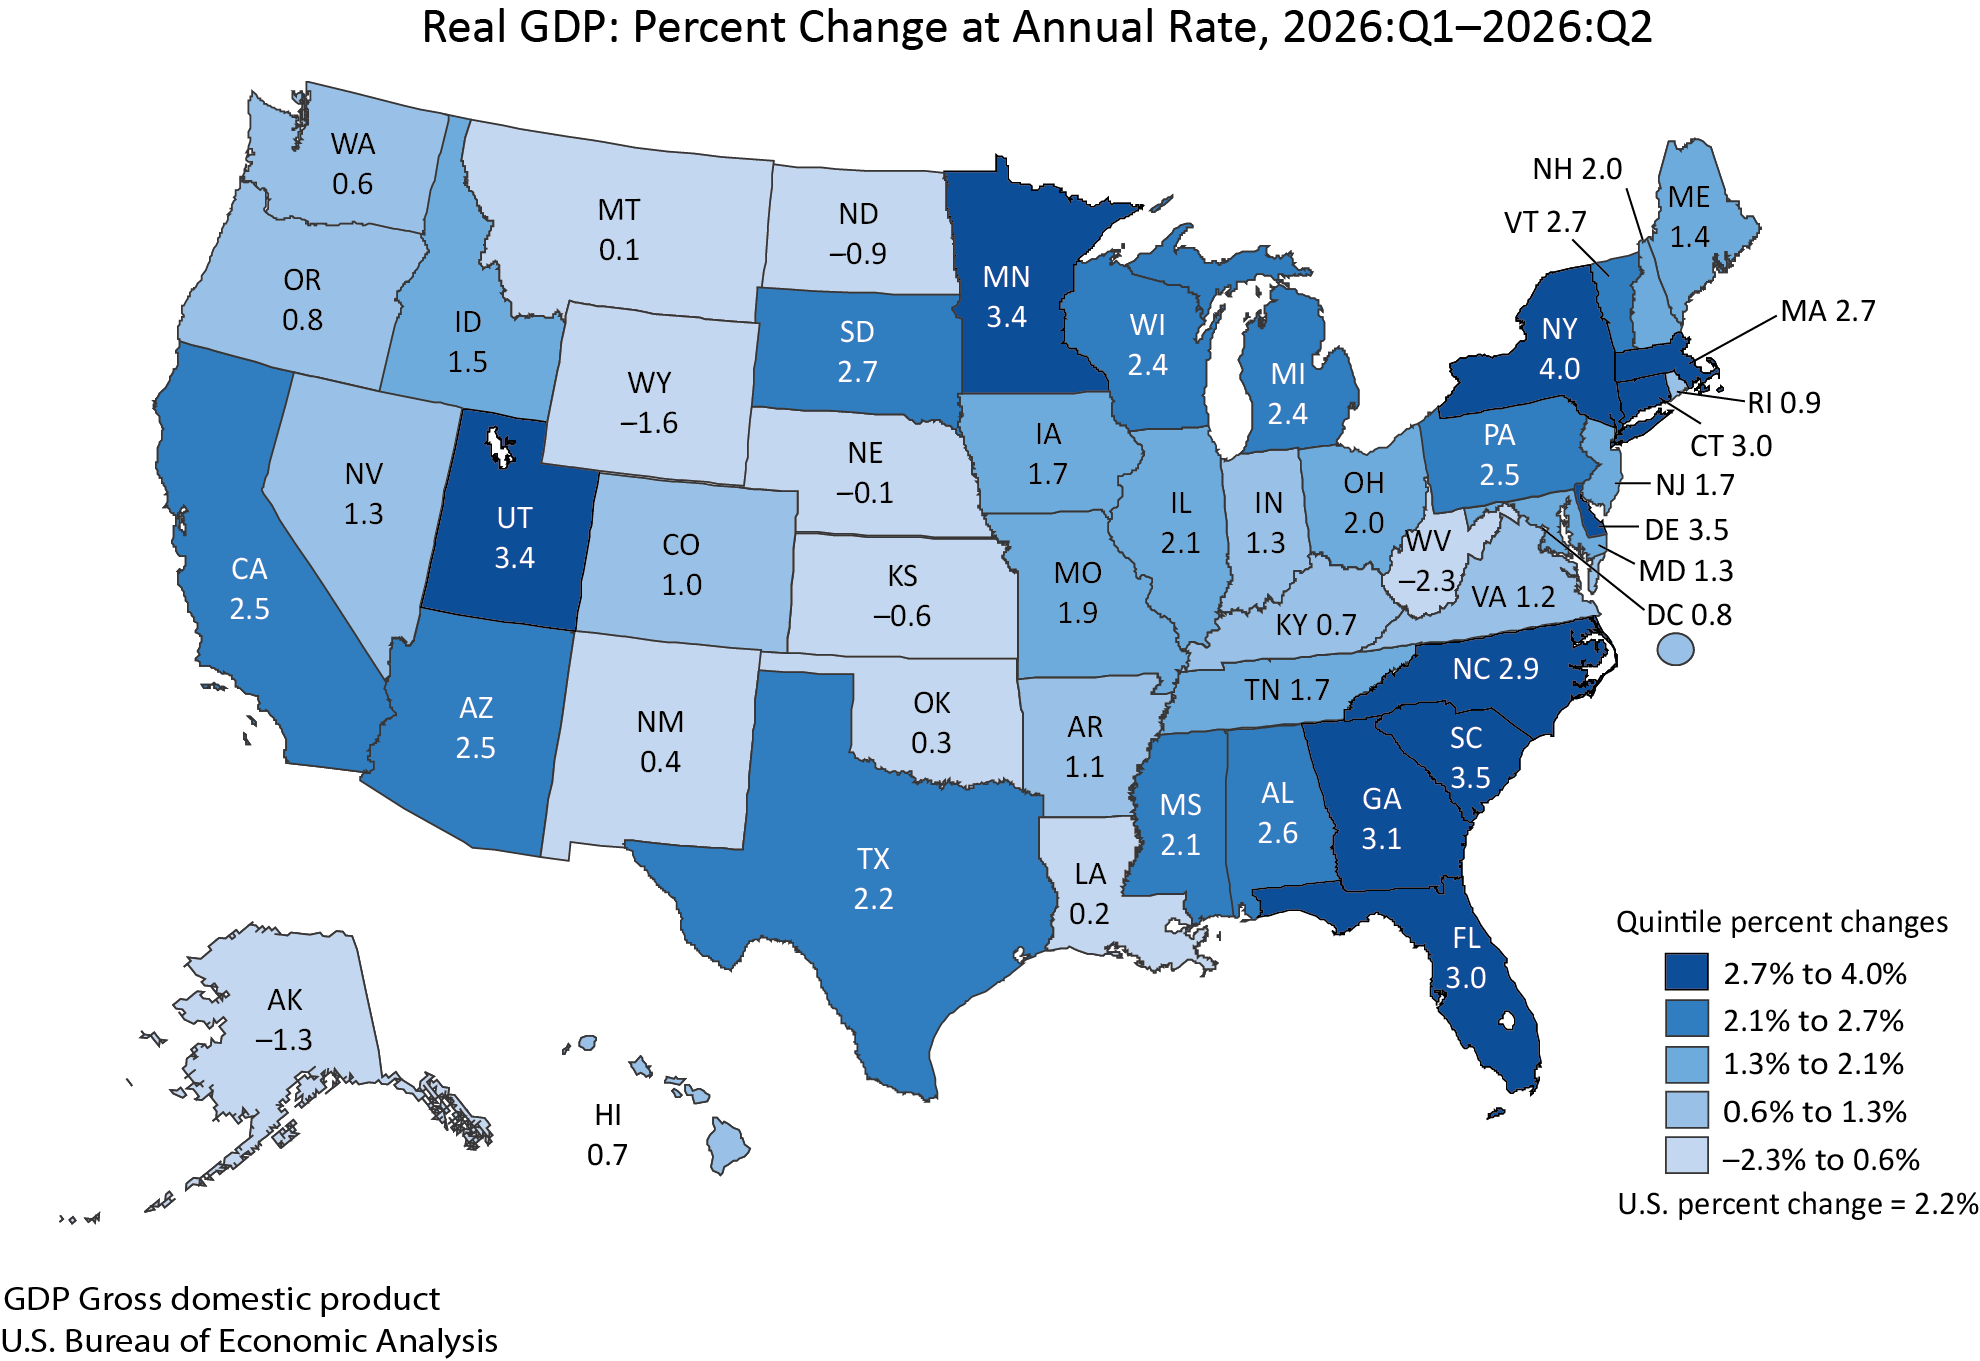
The economic expansion was broadly distributed across the nation, with real GDP increasing in 44 states and the District of Columbia. The percent change at an annual rate varied significantly by state, ranging from a high of 4.0 percent in New York to a contraction of 2.3 percent in West Virginia.
In New York and Delaware, the finance and insurance sector emerged as the leading contributor to GDP growth, reflecting the continued importance of these financial hubs. Conversely, mining was the primary driver of economic contraction in West Virginia and Wyoming, indicating the cyclical nature of commodity-dependent economies.
Personal Income Trends Across States
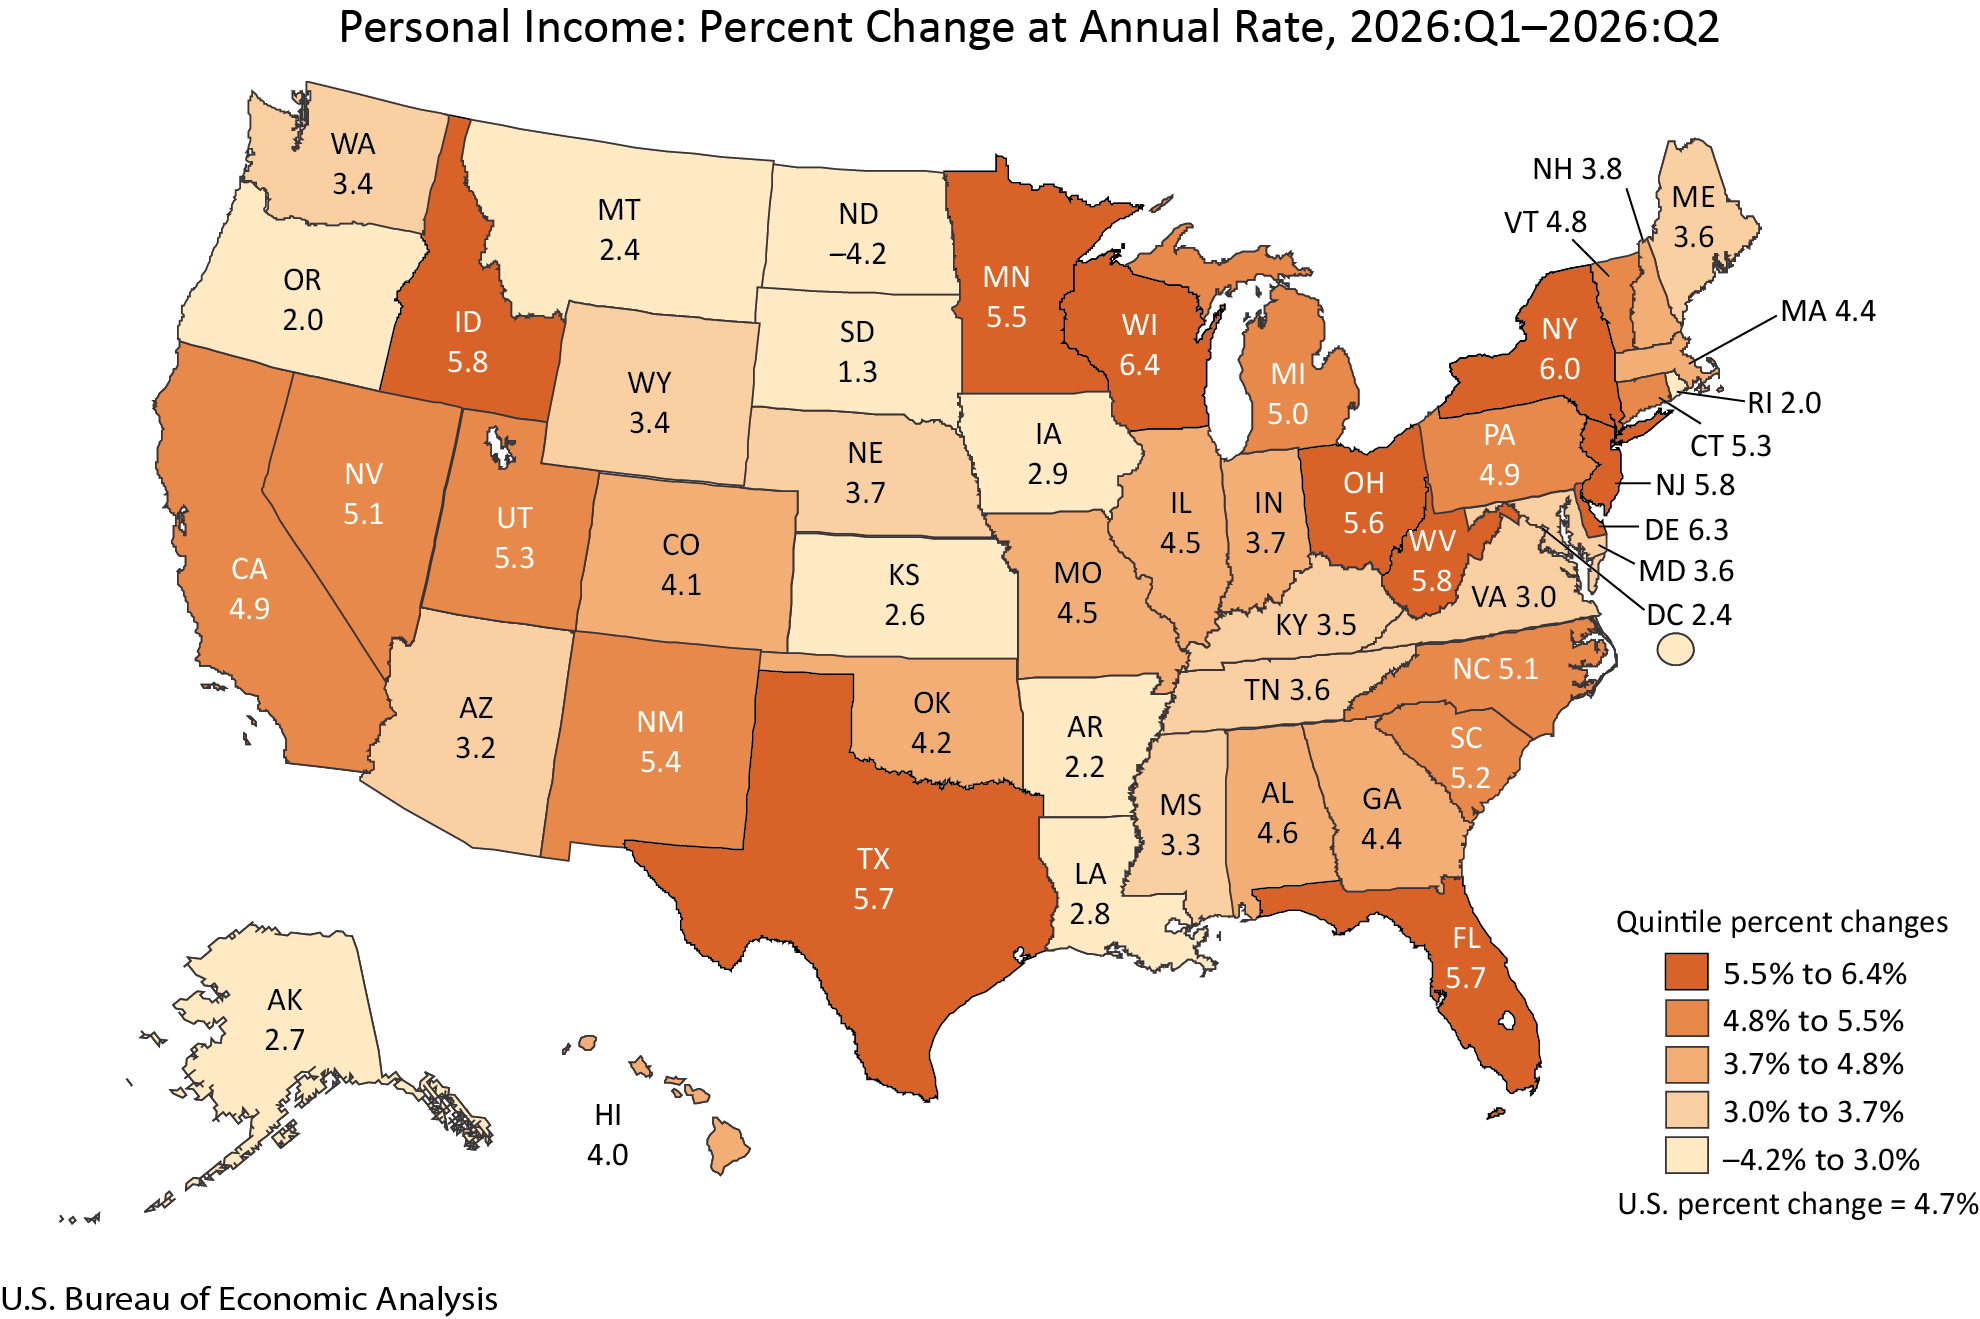
On the personal income front, current-dollar personal income across the nation increased by $314.3 billion, or 4.7 percent at an annual rate, in the second quarter of 2026. Personal income saw growth in 49 states and the District of Columbia, with Wisconsin leading the nation at a 6.4 percent increase. North Dakota, however, experienced a notable decline of 4.2 percent in personal income.
Earnings, which include compensation and proprietors’ income, also showed widespread growth, increasing in 48 states and the District of Columbia. Minnesota recorded the highest earnings growth at 7.3 percent, while North Dakota again faced a significant decrease of 9.3 percent.
Personal current transfer receipts, such as government benefits, saw increases in 48 states, with Wisconsin experiencing the largest rise at 13.0 percent. Oregon, however, saw a decline of 3.9 percent in these receipts. Property income, encompassing dividends, interest, and rent, demonstrated consistent growth across all 50 states and the District of Columbia, with Tennessee showing the highest increase at 5.1 percent and Iowa at 3.3 percent.
Consumer Spending Patterns by State
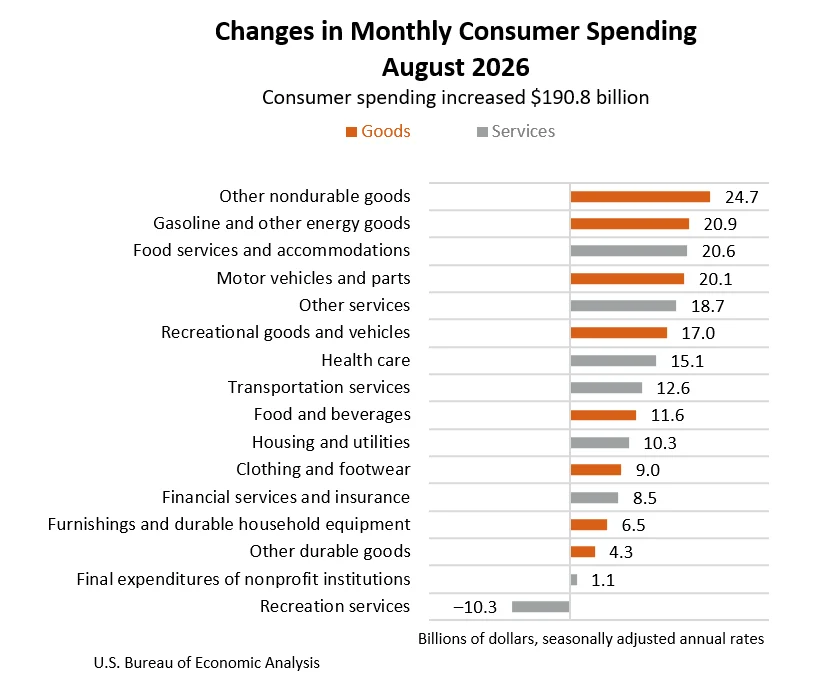
Personal consumption expenditures (PCE), a measure of household spending on goods and services, increased by 5.3 percent nationwide in 2025, with growth observed in 14 out of the 16 major categories tracked by the BEA. At the state level, PCE increased in all 50 states and the District of Columbia. Florida experienced the highest growth rate at 7.0 percent, while California saw a more modest increase of 4.2 percent. Health care and housing and utilities were identified as the primary drivers of PCE increases in most states, including Florida, reflecting fundamental household needs and expenditures.
Annual Updates to Economic Accounts
This release also incorporated the results of the 2026 annual update of the National Economic Accounts, which spans data from the first quarter of 2021 through the first quarter of 2026. These updates resulted in revisions to GDP, GDP by industry, GDI, and their major components, providing a more accurate historical record of economic activity. The reference year for these accounts remains 2017. The annual updates also encompassed GDP by state, personal income by state, and PCE by state, offering a comprehensive recalibration of regional economic data.
Revisions to First-Quarter 2026 Data
The BEA also provided updated figures for the first quarter of 2026, showing a revised real GDP growth rate of 2.5 percent, an upward revision of 0.4 percentage point from the previous estimate. This adjustment was primarily attributed to stronger-than-expected exports of services and increased consumer spending on both goods and services.
Real final sales to private domestic purchasers were revised upward to 1.8 percent, an increase of 0.1 percentage point. Industry-level data for the first quarter showed mixed revisions: private goods-producing industries’ real value added was revised down by 3.0 percentage points to a 1.5 percent increase, while private services-producing industries were revised up by 1.3 percentage points to a 2.1 percent increase. Government sector value added saw a downward revision of 1.2 percentage points to a 6.3 percent increase.
Real gross output for the first quarter was revised upward to a 2.3 percent increase, with private services-producing industries seeing a significant upward revision of 1.2 percentage points to a 2.9 percent increase. Real GDI was also substantially revised upward to a 2.5 percent increase, a 1.3 percentage point gain, largely due to updated wage and salary data from the U.S. Bureau of Labor Statistics. The average of real GDP and real GDI for the first quarter was revised upward to 2.5 percent.
Inflationary measures for the first quarter also saw downward revisions. The gross domestic purchases price index was revised down to a 3.2 percent increase, and the PCE price index was revised down to a 4.2 percent increase. The core PCE price index excluding food and energy was revised down to a 3.9 percent increase.
Corporate profits from current production in the first quarter were revised down by $11.0 billion to an estimated increase of $63.4 billion.
Looking Ahead
The next release of GDP data, the advance estimate for the third quarter of 2026, is scheduled for October 29, 2026, at 8:30 a.m. EDT. This upcoming report will provide the first glimpse into the economy’s performance in the July-to-September period, offering further insights into the ongoing trends and potential shifts in economic momentum. The consistent upward revisions in recent quarters suggest a resilient and adaptable U.S. economy, capable of navigating evolving economic landscapes and maintaining a steady pace of growth. The detailed breakdowns by industry and state, alongside personal income and consumer spending data, provide crucial granular information for businesses, policymakers, and analysts seeking to understand the multifaceted drivers of the nation’s economic health.