Pevita Pearce
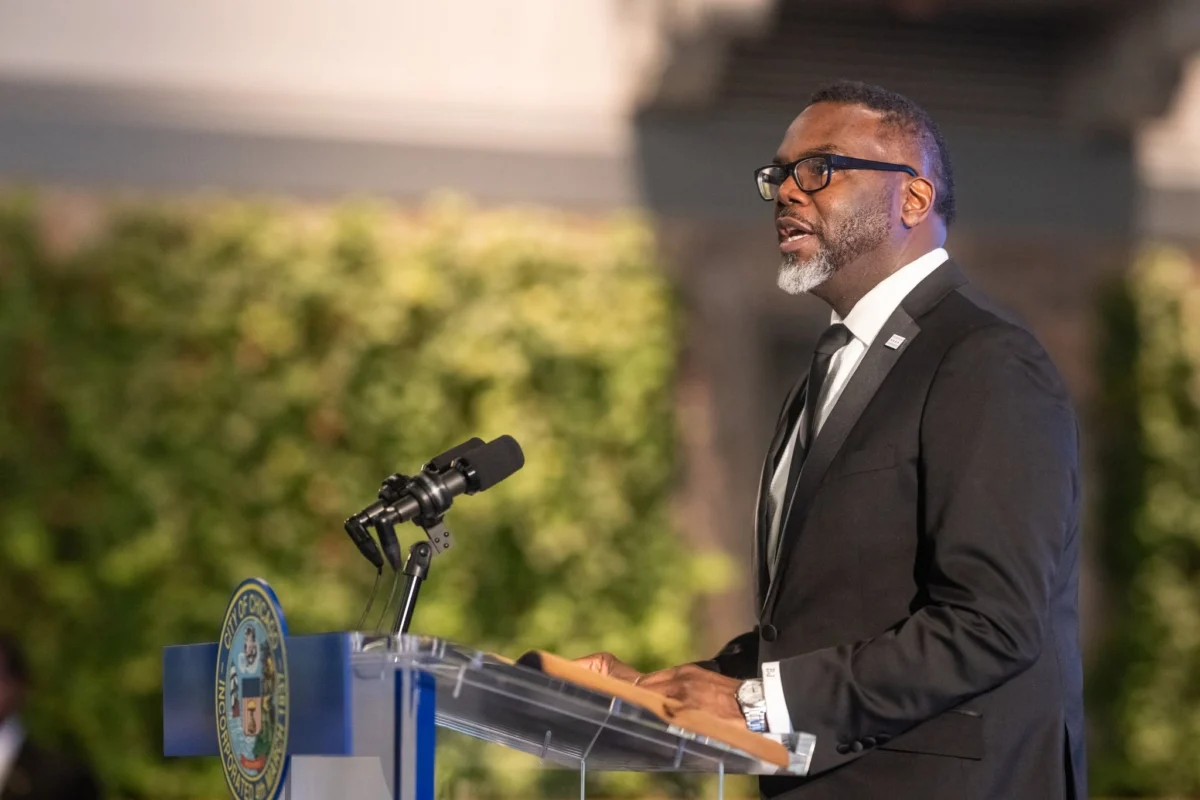
Chicago, IL – In a significant pre-budget maneuver, a substantial bloc of Chicago City Council members has publicly declared their opposition to Mayor Brandon Johnson’s potential reintroduction of a corporate employee head tax for the upcoming 2027 budget. The unified stance, articulated in a letter signed by 29 aldermen, signals an early battle line drawn ahead of Mayor Johnson’s fourth budget address, scheduled for next month. This collective declaration underscores a continuing divergence in fiscal priorities between the mayor’s office and a significant portion of the City Council, echoing the contentious debates surrounding the 2026 budget implementation.
The projected budget gap for the coming fiscal year stands at a formidable $882 million. While Mayor Johnson has yet to formally unveil his proposals to address this deficit, progressive allies within his administration and supportive advocacy groups have persistently championed the head tax as a revenue-generating mechanism. This push comes despite a previous failed attempt by the mayor to pass a similar tax as part of the current year’s budget. The 29 aldermen are now issuing a clear early warning, urging the mayor to abandon this particular fiscal strategy.
"A great city should court employers, not punish them for the act of putting people to work," the aldermen stated in their joint letter. "We will not support a head tax, or any levy that makes it costlier to keep and create jobs for Chicagoans." This statement directly challenges the core premise of the head tax, framing it as a punitive measure rather than a sound fiscal policy. The signatories represent a diverse cross-section of the council, including prominent progressive figures like Ald. Desmon Yancy and Ronnie Mosley, as well as Ald. Pat Dowell, the chair of the Finance Committee. Notably, the coalition of 29 aldermen, while substantial, does not constitute a veto-proof majority, suggesting that further negotiations and potential compromises will be necessary as the budget process unfolds.
Precedent and Political Landscape
The proposed head tax has been a recurring point of contention in Chicago’s recent fiscal discussions. Mayor Johnson first introduced a version of the tax a year ago, proposing a $21-per-employee levy on companies with more than 100 employees. Subsequent negotiations saw this proposal evolve to a $33-per-employee monthly tax targeting companies with over 500 Chicago employees. However, this iteration ultimately failed to gain traction and was voted down in committee, a process that included the Finance Committee chaired by Ald. Dowell.
The current opposition from 29 aldermen is not merely a rehashing of past disagreements but an attempt to preemptively shape the budget discourse. The letter also outlines several other fiscal priorities, emphasizing a commitment to fiscal responsibility and a departure from reliance on uncertain revenue streams.
Key Fiscal Demands and Concerns
Beyond the head tax, the aldermen’s letter articulates a clear set of fiscal demands aimed at stabilizing the city’s finances and fostering economic growth. These include:
- No Property Tax Increases: In what is widely considered an election-year budget, the call for no increases to property taxes is a predictable yet significant demand, aiming to alleviate the financial burden on homeowners and businesses.
- Crackdown on City-Owned Debt: The letter advocates for a more stringent approach to managing and reducing the city’s accumulated debt, signaling a desire for greater fiscal prudence and long-term financial health.
- No Reliance on Unapproved Springfield Revenues: This point directly addresses the city’s reliance on state-level funding that has not yet been secured or approved. The aldermen are signaling a preference for internally generated or assured revenue sources, avoiding budget projections that are contingent on legislative action in Springfield. This concern is amplified by the recent approval of the Chicago school board’s 2027 budget, which reportedly factored in such uncertain state revenues to avoid layoffs.
The overarching message from the aldermen is a call for fiscal discipline and a prioritization of cost-saving measures before considering new tax burdens. "Our first demand is simple: reduce the recurring cost of City government before asking anyone to pay more," the letter emphatically states. "A one-time expense does not justify a permanent tax. A program launched on temporary federal dollars should not quietly become a standing obligation of Chicago’s taxpayers. And new discretionary spending deserves a second look before anyone is asked to pay more." This sentiment reflects a broader concern about the sustainability of city programs and the potential for temporary funding solutions to become long-term financial obligations.
Progressive Advocacy and Divergent Views
The "People’s Unity Platform," a coalition of left-leaning unions and advocacy groups, has been actively advocating for increased taxation on large corporations. Last Friday, this coalition held a rally in support of a "big corporation tax," though specifics regarding the threshold for "big" varied between their promotional materials and online presence. Initially, these discussions involved minimums of 100 or 500 employees.
Ishan Daya, co-director of the Institute for Public Good, a member of the coalition, clarified that the varying employee numbers were "out of date." He emphasized that the core of their platform is a call to raise at least $100 million through a head tax, irrespective of the specific headcount or surcharge amount. Daya also indicated that the platform is linked to a sunset clause tied to the city’s potential implementation of a corporate income tax that could generate at least $100 million, contingent on the state lifting existing constraints on the city’s taxing authority.
Mayor Johnson, when questioned last Friday about whether a 500-employee floor might be a more viable starting point for a head tax, did not provide a direct answer. Instead, he reiterated his broader endorsement of the city’s need for progressive revenue and his consistent argument that "the ultra-rich and these big corporations put more skin in the game." This response suggests that while the specific mechanics of a head tax may be subject to negotiation, the mayor remains committed to the principle of extracting greater financial contributions from large corporations.
Analysis of Implications
The strong opposition from a majority of the City Council presents a significant hurdle for Mayor Johnson’s head tax ambitions. The aldermen’s preemptive letter indicates a unified front that could effectively block any attempt to reintroduce the tax without substantial concessions. This dynamic has several potential implications:
- Budgetary Challenges: The projected $882 million budget gap will require alternative solutions. Without the potential revenue from a head tax, the city may need to explore deeper spending cuts, seek new revenue streams, or rely more heavily on existing tax bases, which could still face political resistance.
- Mayoral-Council Relations: The clear division on this issue highlights ongoing tensions between the mayor and a significant portion of the council. The effectiveness of Mayor Johnson’s administration in navigating the budget and other legislative priorities will depend on his ability to forge broader consensus or overcome council opposition.
- Economic Development Debate: The debate over the head tax is intrinsically linked to Chicago’s economic development strategy. Proponents argue it’s a fair way to ensure large corporations contribute to the city’s infrastructure and services, while opponents contend it could stifle job creation and deter investment. The council’s stance suggests a greater emphasis on business attraction and retention, potentially prioritizing policies that are perceived as more business-friendly.
- Progressive vs. Moderate Factions: The opposition, while including some progressive members, also draws significant support from more moderate or business-aligned aldermen. This coalition demonstrates the complex political landscape of the City Council, where fiscal issues can transcend traditional ideological divides.
- Future Revenue Strategies: The aldermen’s call for reducing recurring costs and avoiding reliance on unapproved revenues suggests a push towards more sustainable and predictable fiscal management. This could lead to a greater focus on internal efficiencies and long-term financial planning, rather than relying on potentially volatile or contested revenue sources.
As Mayor Johnson prepares to deliver his budget address, the vocal opposition from the City Council sets a clear expectation for the upcoming fiscal deliberations. The coming weeks are likely to be characterized by intense negotiation as the city grapples with its financial challenges and charts its course for the future. The stance taken by the 29 aldermen serves as a powerful indicator of the political realities Mayor Johnson must contend with in his efforts to balance the city’s budget and fund essential services.