Layla Zulfa
The Federal Housing Finance Agency (FHFA) is poised to mandate a significant shift in mortgage underwriting practices for loans delivered to Fannie Mae and Freddie Mac, moving from the current "tri-merge" credit report standard to a "bi-merge" model. This directive, expected to be formally announced within weeks, signifies a potentially transformative change for the mortgage industry and has been a topic of considerable discussion and debate within the sector. The announcement could be made as early as October 12th by FHFA Director Bill Pulte during the Mortgage Bankers Association (MBA) conference in Chicago, according to sources familiar with the agency’s plans who spoke to Bloomberg.
FHFA officials have not yet provided an immediate comment to HousingWire regarding this impending change. However, the prospect of this transition has been building for some time, with Director Pulte himself publicly signaling the agency’s serious consideration of the bi-merge approach.
A Shift in Credit Reporting: From Tri-Merge to Bi-Merge
For years, lenders originating mortgages intended for sale to Fannie Mae and Freddie Mac have been required to utilize tri-merge credit reports. A tri-merge report consolidates credit information from all three major credit reporting agencies: Equifax, Experian, and TransUnion. This comprehensive approach has been the industry standard, providing underwriters with the broadest possible view of a borrower’s credit history.
The proposed shift to a bi-merge report would allow lenders to select credit data from any two of the three major bureaus. This change, while seemingly minor in its description, carries substantial implications for the mechanics of loan origination and the overall cost structure of mortgage credit. The expectation is that this new policy will be implemented approximately one to three months after its official announcement, providing a transition period for lenders and credit reporting agencies.
The Rationale Behind the Bi-Merge Transition
Director Pulte has been an outspoken critic of the current credit reporting landscape, particularly concerning the perceived overcharging by credit bureaus. In early September, he took to social media platform X (formerly Twitter) to express his intent to address these concerns. "Equifax, Experian, and TransUnion have been overcharging Americans for far too long. This will end soon," Pulte stated. "We are seriously considering bi-merge, and stronger solutions (SAFER and SOUNDER). We will not allow companies to take advantage of American consumers. No more."
This sentiment suggests that a primary driver for the bi-merge adoption is to foster competition among credit bureaus and potentially reduce the cost of credit reports for lenders. By allowing lenders to choose two out of three bureaus, it is anticipated that the market will become more competitive, incentivizing bureaus to offer more attractive pricing and potentially leading to cost savings that could be passed on to consumers or absorbed by lenders.
Historical Context and Previous Delays
The conversation around bi-merge credit reports is not new. A similar initiative was considered during the Biden administration when Sandra Thompson served as FHFA Director. At that time, a bi-merge option was indeed on the table. However, the plan was ultimately delayed due to what were described as "implementation challenges." These challenges likely encompassed the technical hurdles of integrating a new reporting standard into existing underwriting systems, ensuring data consistency across different bureau combinations, and addressing potential impacts on risk assessment models.
More recently, there has been a discernible pushback from some segments of the industry regarding the move away from tri-merge reports. The Mortgage Bankers Association (MBA), in particular, has been a vocal proponent of exploring alternatives, including a "single-file option," which could represent an even more streamlined approach to credit reporting. The MBA’s stance suggests a concern that the transition to bi-merge, while potentially beneficial in some aspects, might still present complexities or not fully address all the efficiency goals desired by lenders.
Broader Implications for Credit Scoring and GSEs
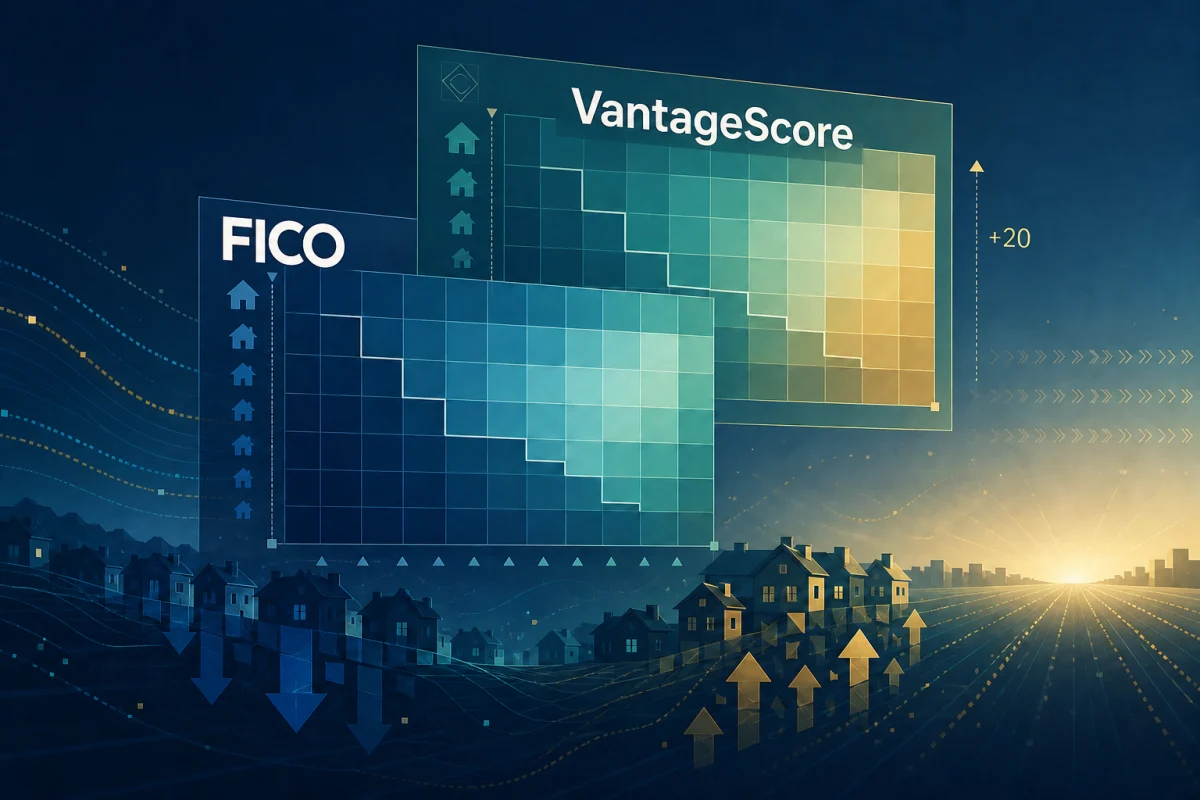
This move toward bi-merge credit reports is not an isolated policy shift but rather part of a larger strategy by Director Pulte to reform the credit scoring and reporting ecosystem for loans sold to Fannie Mae and Freddie Mac. In a significant development earlier in the week, Pulte also announced that Fannie Mae and Freddie Mac would be permitted to use credit scores from VantageScore, a joint venture formed by Equifax, Experian, and TransUnion.
This decision marked a reversal of earlier GSE grids that had suggested VantageScore 4.0 scores might overstate borrower creditworthiness by approximately 20 points compared to traditional FICO scores. Pulte’s latest directive mandates that the GSEs will now utilize a "single pricing grid" that treats VantageScore 4.0 scores as equivalent to Classic FICO scores. This integration of VantageScore into the GSE framework, alongside the impending bi-merge credit report requirement, signals a broader effort to diversify the credit data and scoring models used in the mortgage market.
Analyzing the Potential Impacts
The transition to bi-merge credit reports is likely to have several key impacts:
- Cost Savings: The primary expectation is a reduction in the cost of credit reports for lenders. If bureaus compete more aggressively, the price per report could decrease. These savings could potentially translate into lower origination fees for borrowers or improved profitability for lenders.
- Increased Competition: By allowing lenders to choose from two of three bureaus, the FHFA aims to foster a more competitive environment among Equifax, Experian, and TransUnion. This could lead to innovation in data provision and service offerings.
- Underwriting Efficiency: While the tri-merge has been the standard, a bi-merge might streamline some aspects of data acquisition and review for certain loan types or borrower profiles. However, lenders will need to ensure their systems and processes can effectively handle data from various combinations of bureaus.
- Data Discrepancies and Risk Assessment: A potential challenge with bi-merge reports is the possibility of increased data discrepancies between the chosen bureaus. Lenders and the GSEs will need robust processes to identify and reconcile any such differences to ensure accurate risk assessment. The reliance on two bureaus instead of three might also slightly alter the comprehensive view of a borrower’s creditworthiness, necessitating adjustments in underwriting models.
- Impact on Credit Bureaus: The shift could affect the revenue streams of the credit bureaus. Those bureaus that are consistently excluded by lenders may need to adjust their pricing or service offerings to remain competitive.
- Technological Adaptation: Lenders and mortgage technology providers will need to ensure their loan origination systems (LOS) and underwriting platforms are fully compatible with the bi-merge requirement. This may involve software updates and system reconfigurations.
Industry Reactions and Future Outlook
While official comments are pending, industry stakeholders are likely to be analyzing the practical implications of this directive. Mortgage lenders will be closely evaluating the cost-benefit analysis of the bi-merge approach, considering the potential for savings against any increased complexity or risk.
The MBA’s previous advocacy for a single-file option suggests that some industry participants may believe the bi-merge is a step in the right direction but not the ultimate solution for maximum efficiency. Nevertheless, the FHFA’s clear direction indicates that the bi-merge model is the immediate path forward.
The inclusion of VantageScore alongside FICO, and the move to a unified pricing grid, further underscores the FHFA’s commitment to modernizing the credit reporting and scoring infrastructure for the secondary mortgage market. These combined changes are designed to create a more dynamic, competitive, and potentially more cost-effective system for the origination of mortgages that are eligible for sale to Fannie Mae and Freddie Mac. The coming weeks will be crucial as the FHFA formalizes these directives and the industry begins to adapt to a new era of credit reporting for a significant portion of the U.S. housing market.