Lana Rhoades
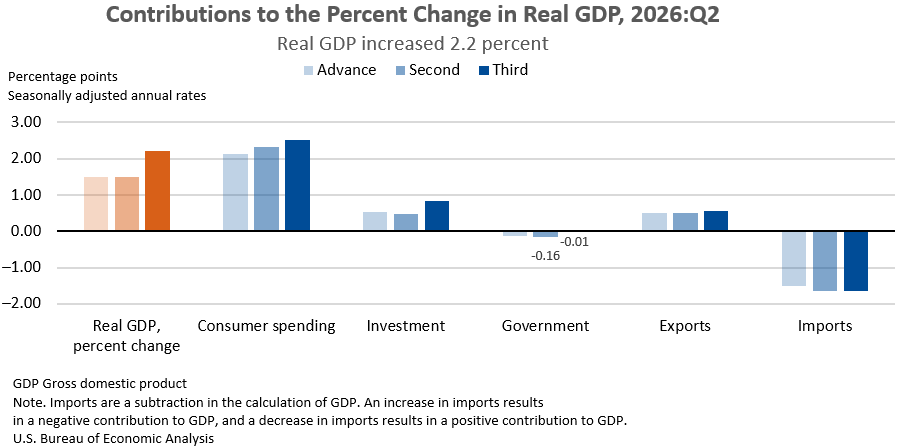
The U.S. economy demonstrated robust growth in the second quarter of 2026, with real gross domestic product (GDP) increasing at an annual rate of 2.2 percent, according to the third estimate released by the U.S. Bureau of Economic Analysis (BEA). This figure represents a significant upward revision from the second estimate, primarily driven by stronger performances in investment, consumer spending, and government expenditures. This acceleration follows a solid 2.5 percent growth rate recorded in the first quarter of the year, indicating sustained economic momentum.
The upward revision of 0.7 percentage point for the second quarter underscores the economy’s capacity to expand beyond initial assessments. This revised figure suggests that underlying economic drivers were more potent than previously captured in preliminary data. The BEA’s comprehensive analysis incorporates a wide array of economic indicators, and the adjustments made in the third estimate reflect a more complete picture of economic activity during April, May, and June 2026.
Key drivers of this growth included a notable uptick in consumer spending, which remains a cornerstone of the U.S. economy. Investment also played a crucial role, signaling increased business confidence and a willingness to allocate capital towards future expansion. Government spending, though often subject to political and budgetary considerations, also contributed positively to the overall GDP figure in the second quarter. Imports, which are subtracted in the calculation of GDP, did see an increase, a common occurrence in periods of economic expansion as domestic demand rises.
A Deeper Dive into Economic Performance
The BEA’s detailed analysis revealed that contributions to the second-quarter GDP increase were led by consumer spending, investment, and exports. The expansion in exports suggests a favorable global economic environment or increased competitiveness of American goods and services on the international stage.
GDP by Industry: A Sectoral Overview
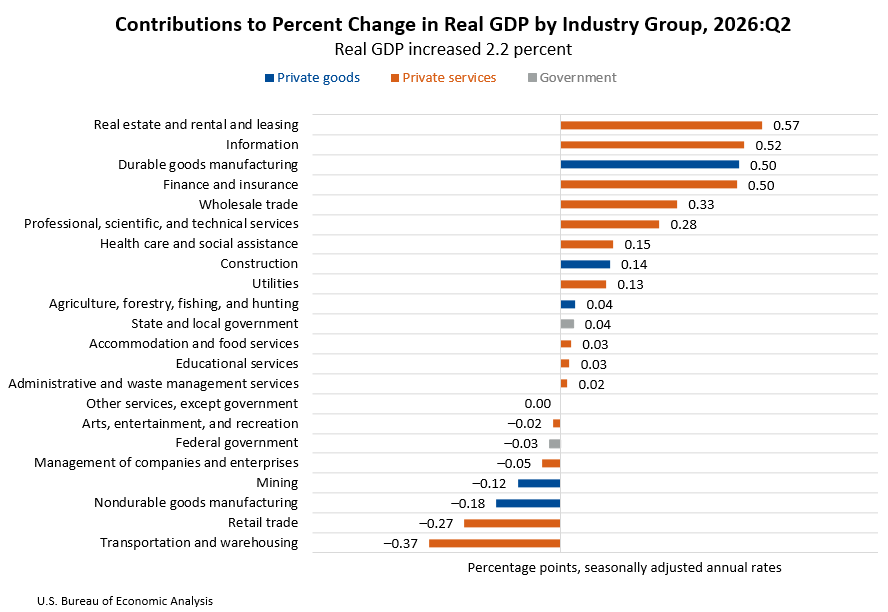
Examining the economic landscape through an industry lens provides further insight into the sources of growth. Real value added, a measure of an industry’s contribution to GDP, saw a healthy increase of 2.5 percent for private services-producing industries and 2.3 percent for private goods-producing industries. Government sectors experienced a more modest increase of less than 0.1 percent.
Several industries emerged as leading contributors to the overall GDP expansion. Real estate and rental and leasing demonstrated strong performance, likely reflecting continued demand in the housing market and commercial property sectors. The information sector also showed significant growth, indicative of the ongoing digital transformation and the increasing reliance on technology across various facets of the economy. Durable goods manufacturing and the finance and insurance sectors also bolstered the growth figures.
Conversely, certain sectors acted as offsets to the overall positive trend. Transportation and warehousing experienced a decrease, potentially signaling shifts in logistics or supply chain adjustments. Retail trade also saw a decline, which could be attributed to evolving consumer purchasing habits or inventory management strategies. Nondurable goods manufacturing also contributed to the drag on GDP growth.
Related Economic Measures: A Broader Perspective
Beyond the headline GDP figure, several other economic indicators provide a more nuanced understanding of the economy’s health. Real final sales to private domestic purchasers, which encompasses consumer spending and gross private fixed investment, saw a significant increase of 4.6 percent in the second quarter. This metric is often viewed as a more direct measure of domestic demand, and its robust growth further reinforces the picture of a strong economy. This figure was revised up by 0.4 percentage point from the previous estimate, highlighting the dynamic nature of economic data.
Real gross output, a measure that tracks the total value of goods and services produced by the economy, increased by 5.0 percent. This was driven by strong growth in private services-producing industries (6.0 percent) and private goods-producing industries (3.0 percent), with government sectors contributing 2.6 percent.
The relationship between GDP and Gross Domestic Income (GDI) offers another perspective. Real GDI, which measures the income generated by the economy, increased by 2.6 percent in the second quarter, revised up by 0.4 percentage point. The average of real GDP and real GDI, often considered a more stable measure of economic growth, increased by 2.4 percent, revised up by a notable 0.6 percentage point. This convergence suggests a consistent and broad-based economic expansion.
Corporate profits from current production also showed a substantial increase, rising by $384.0 billion in the second quarter. While this figure was revised down slightly by $16.9 billion, it still indicates a healthy environment for businesses.
Inflationary pressures, as measured by the price index for gross domestic purchases, increased by 5.6 percent. This figure was revised down by 0.2 percentage point from the previous estimate, suggesting a slight moderation in price increases. The Personal Consumption Expenditures (PCE) price index, a closely watched inflation gauge, increased by 5.0 percent, also revised down by 0.3 percentage point. The core PCE price index, which excludes volatile food and energy components, increased by 3.3 percent, revised down by 0.3 percentage point. While inflation remains elevated, these downward revisions provide some indication of a moderating trend.
GDP by State: Regional Economic Performance
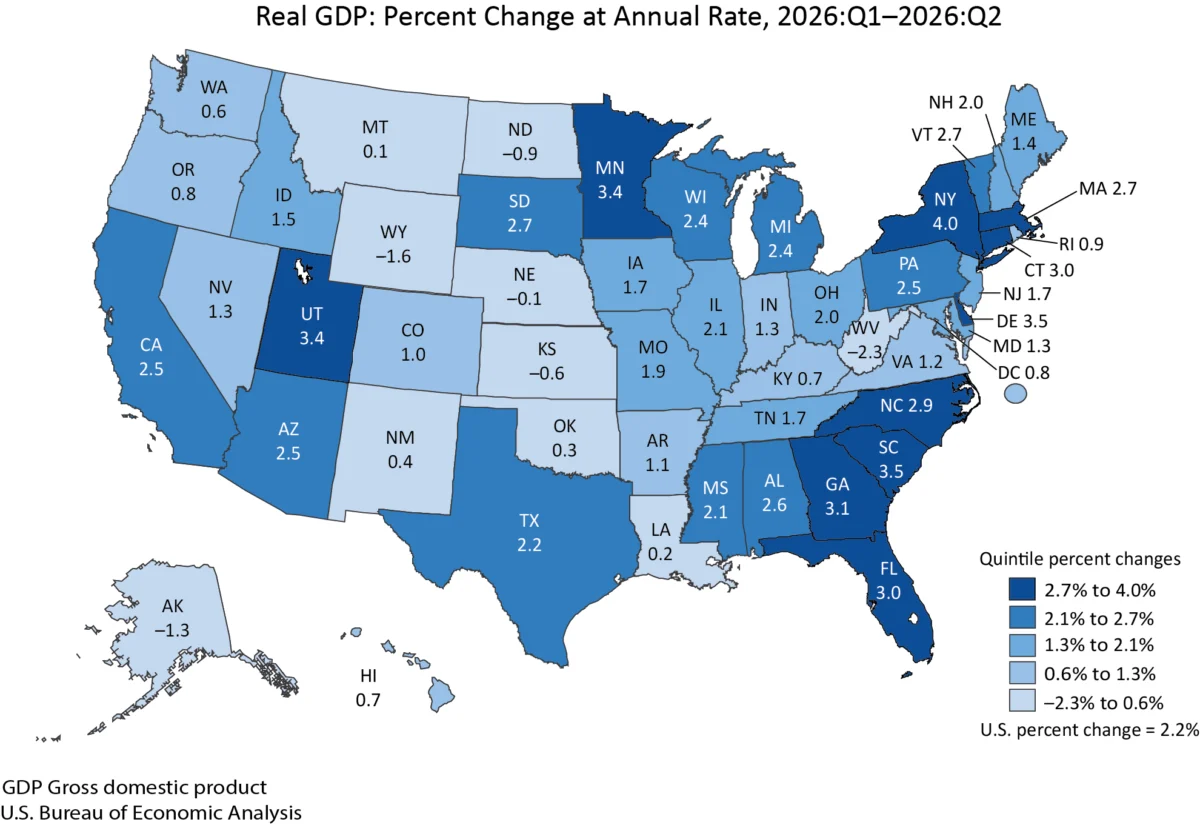
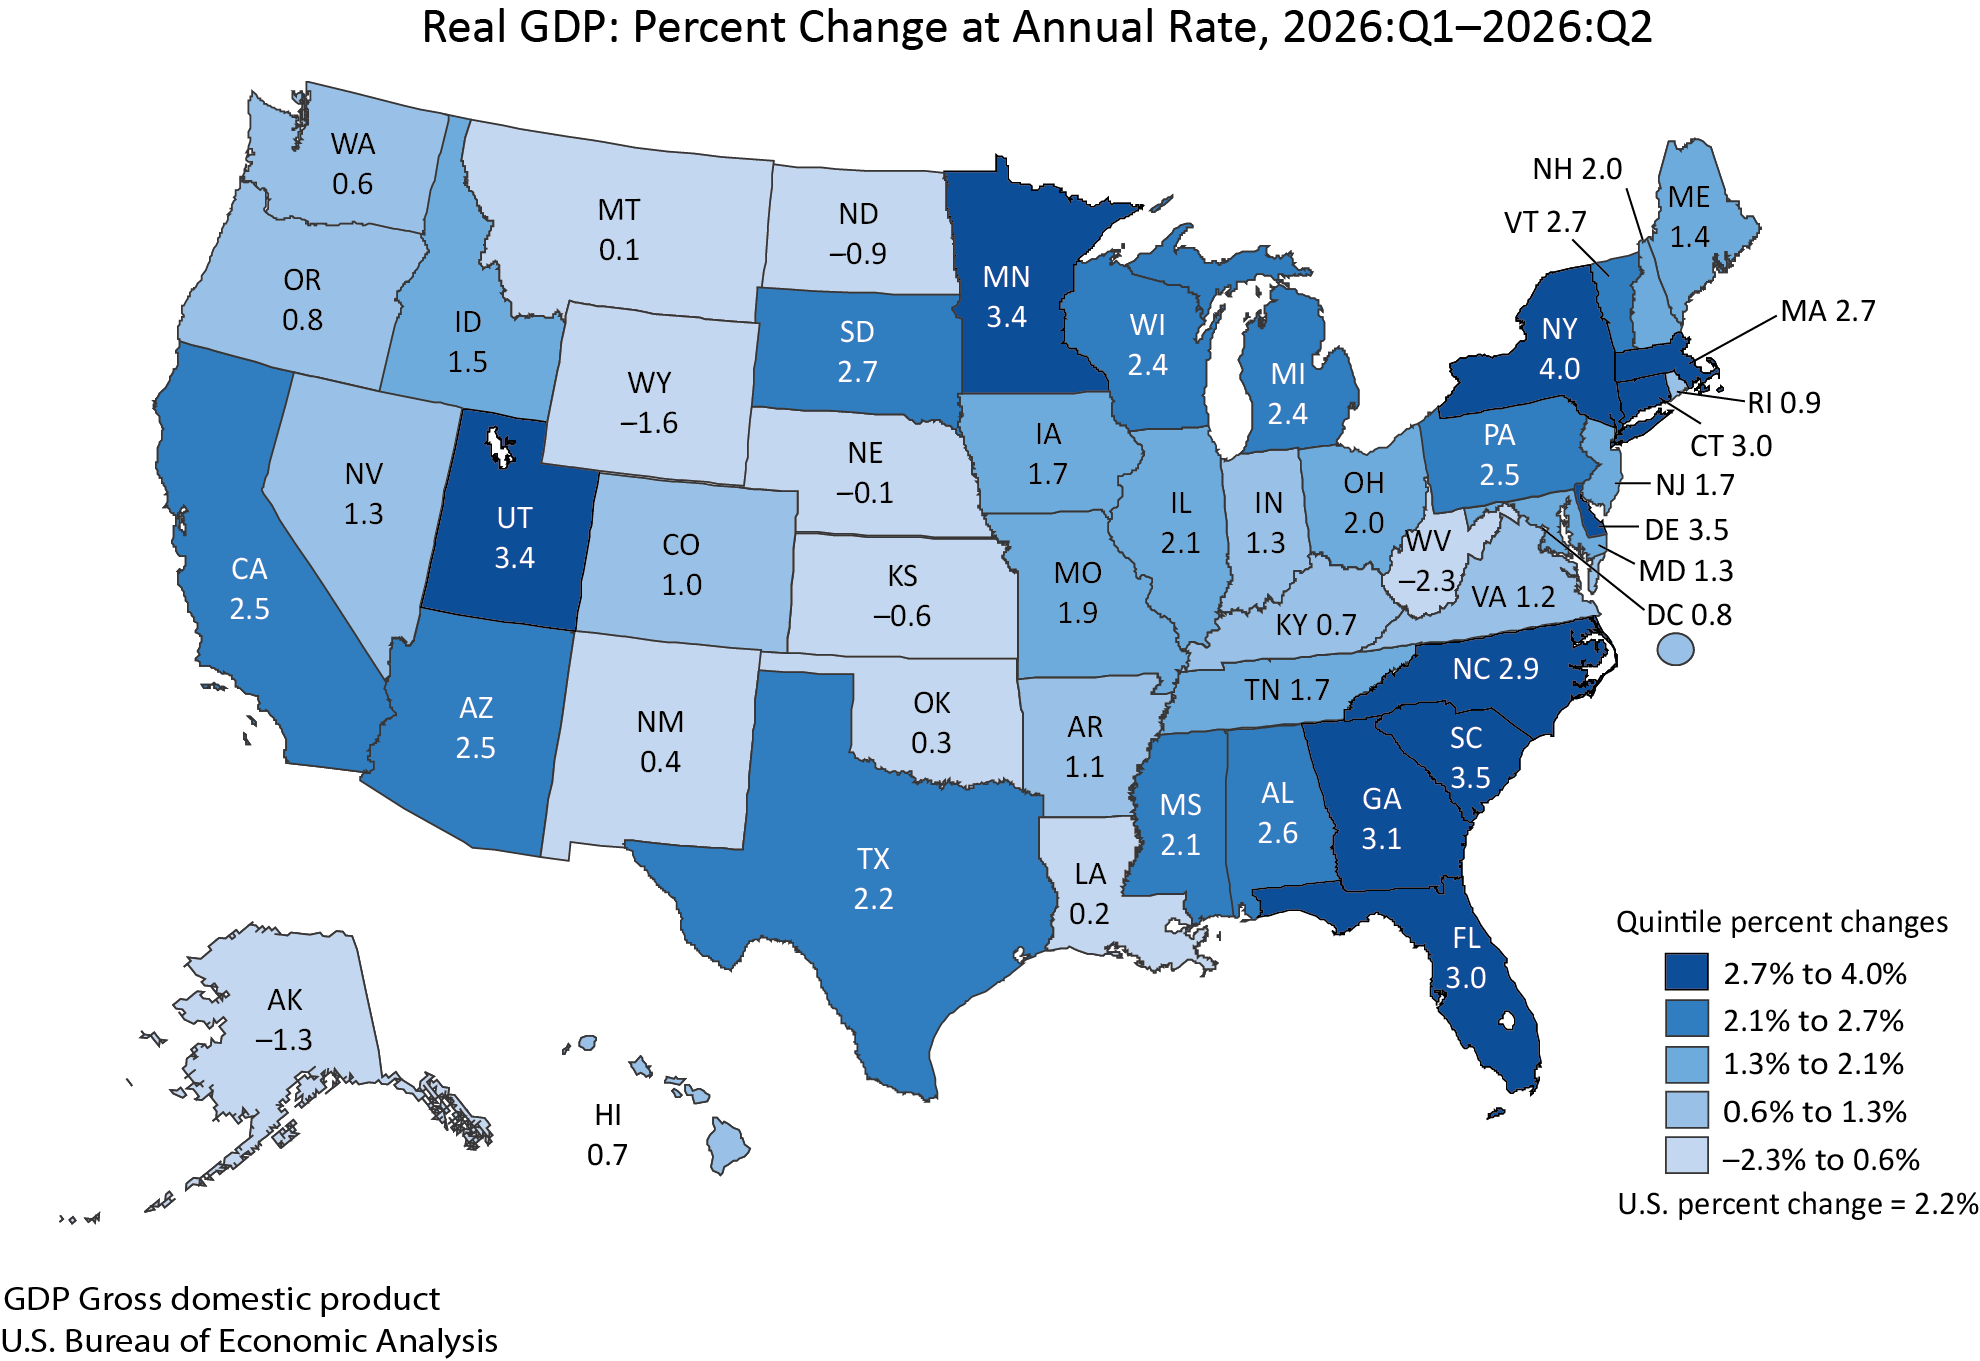
The economic expansion was not uniform across the nation, with significant regional variations observed. In the second quarter of 2026, real GDP increased in 44 states and the District of Columbia. The pace of growth varied considerably, with New York experiencing a robust 4.0 percent annual rate of increase, while West Virginia saw a contraction of 2.3 percent.
In New York and Delaware, the finance and insurance sector was the primary driver of GDP growth. Conversely, mining played a leading role in the economic downturn observed in West Virginia and Wyoming. These state-level figures highlight the diverse economic structures and industry concentrations that influence regional growth trajectories.
Personal Income by State: A Look at Household Earnings
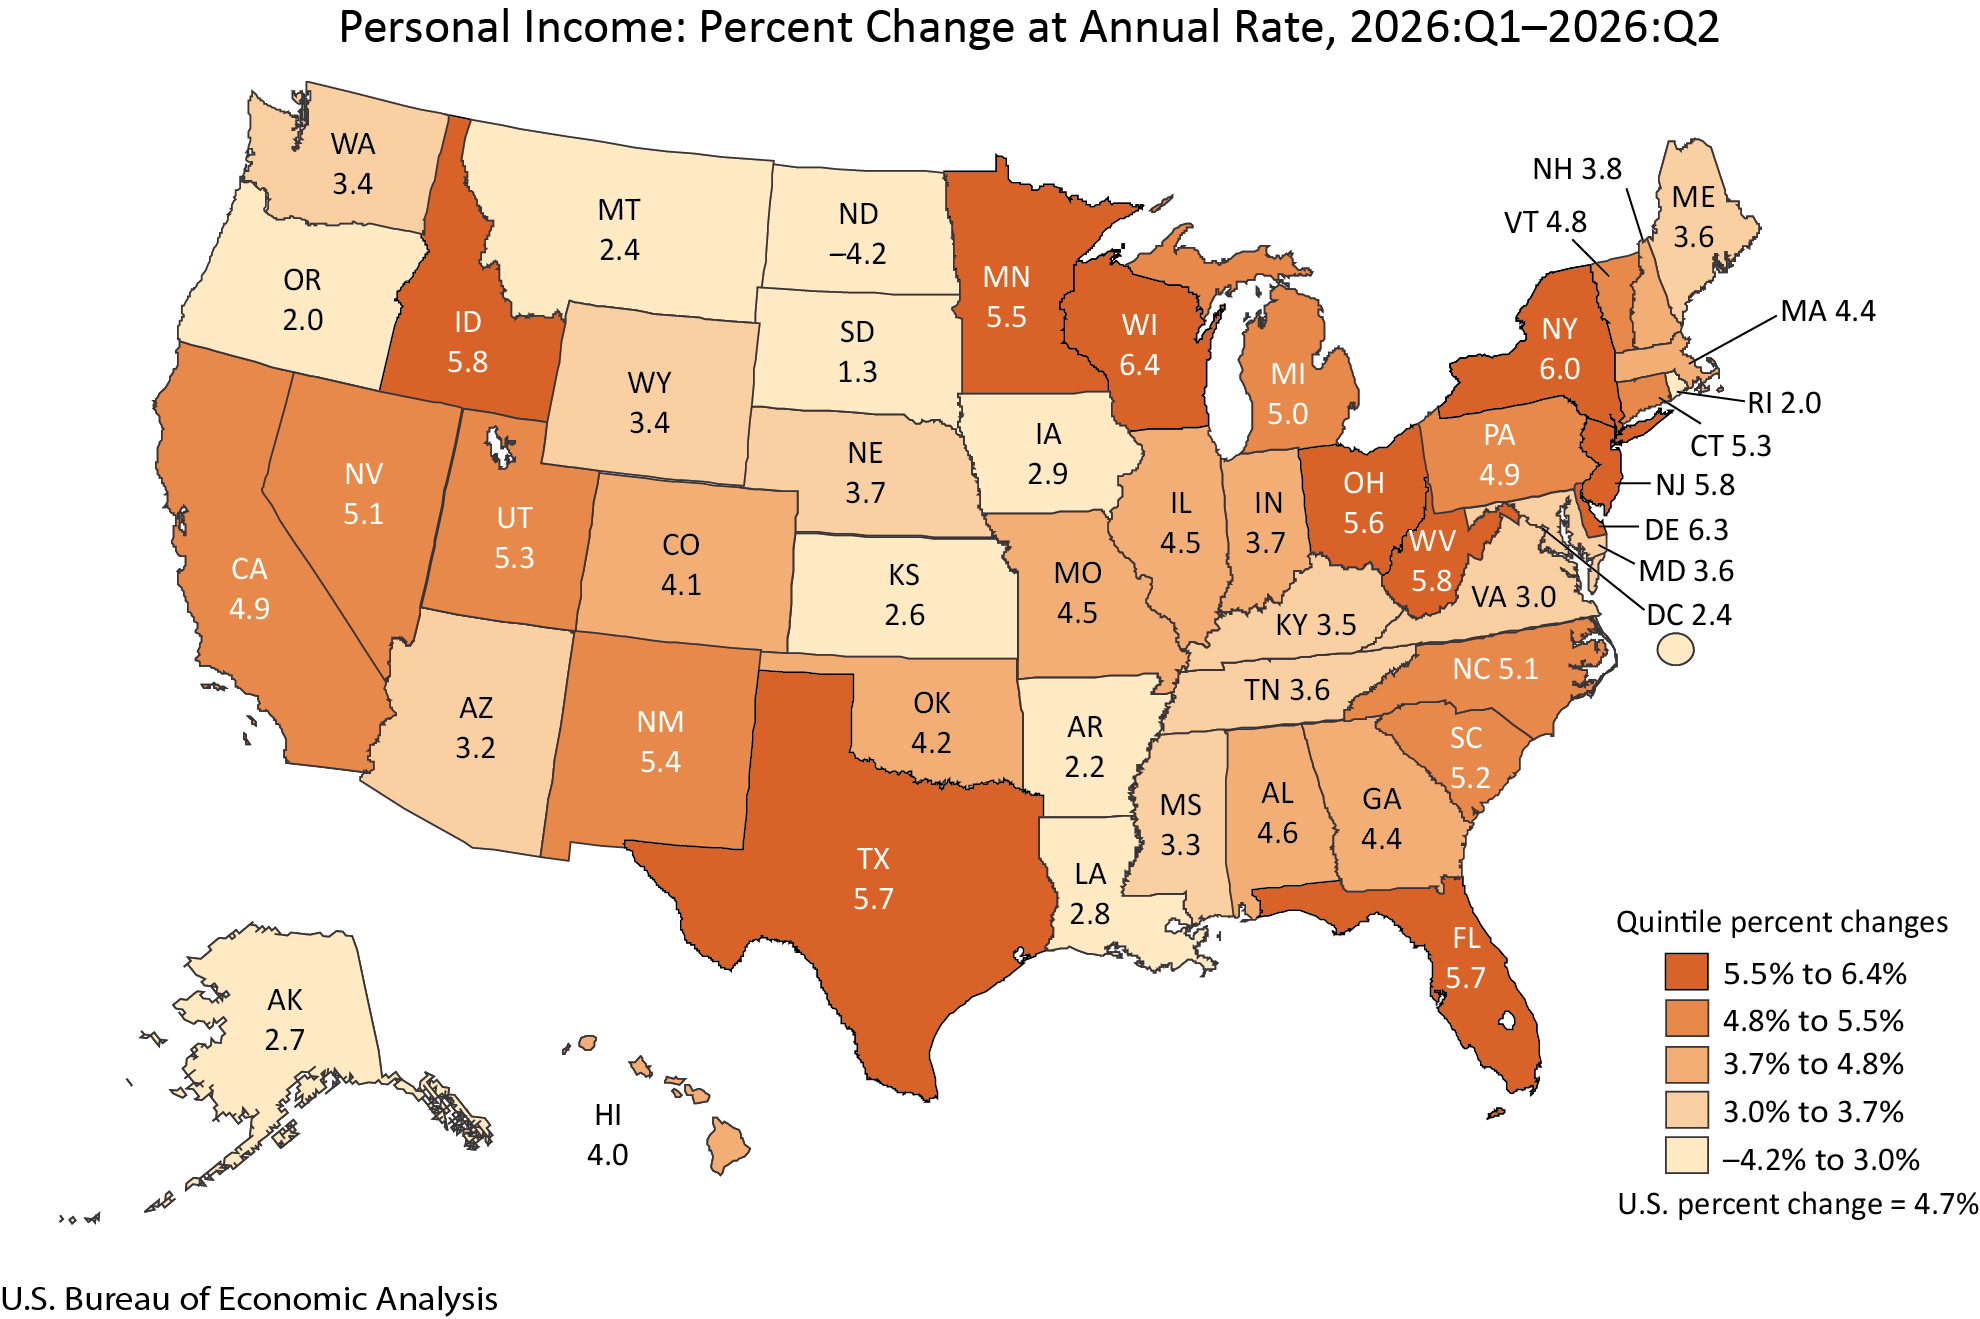
On the personal income front, current-dollar personal income across the nation increased by $314.3 billion, or 4.7 percent at an annual rate, in the second quarter of 2026. Personal income saw gains in 49 states and the District of Columbia. Wisconsin led the nation with a remarkable 6.4 percent increase in personal income at an annual rate, while North Dakota experienced a notable decline of 4.2 percent.
Earnings, which include compensation and proprietors’ income, increased in 48 states and the District of Columbia. Minnesota reported the highest earnings growth at 7.3 percent, while North Dakota again faced a significant decrease of 9.3 percent. Personal current transfer receipts, such as government benefits, increased in 48 states but declined in the District of Columbia, with Wisconsin showing the largest increase at 13.0 percent and Oregon experiencing a 3.9 percent decrease. Property income, encompassing dividends, interest, and rent, demonstrated broad-based growth, increasing in all 50 states and the District of Columbia, with Tennessee showing the highest growth rate at 5.1 percent.
Personal Consumption Expenditures by State: Consumer Spending Patterns
Personal Consumption Expenditures (PCE), a key component of GDP, showed a 5.3 percent increase in current dollars for the year 2025, with growth observed in 14 out of 16 major categories tracked by the BEA. At the state level, PCE increased in all 50 states and the District of Columbia. Florida recorded the highest percentage change in PCE at 7.0 percent, while California saw a more modest increase of 4.2 percent. Health care and housing and utilities were identified as the leading contributors to PCE increases in most states, including Florida, underscoring their importance in consumer spending.
Annual Update of National and Regional Economic Accounts
This release also incorporates the results of the 2026 annual update of the National Economic Accounts, covering data from the first quarter of 2021 through the first quarter of 2026. These updates led to revisions in GDP, GDP by industry, GDI, and their constituent components. The reference year for these accounts remains 2017. The annual updates also extend to GDP by state, personal income by state, and PCE by state, providing a comprehensive recalibration of economic data.
Revisions to First Quarter 2026 Data
The BEA also provided updated figures for the first quarter of 2026. Real GDP is now estimated to have increased at a 2.5 percent annual rate, an upward revision of 0.4 percentage point from the previous estimate. This revision was largely attributed to stronger-than-expected exports of services and increased consumer spending on both goods and services.
Real final sales to private domestic purchasers for the first quarter were revised up to an 1.8 percent increase, a 0.1 percentage point upward adjustment. Industry-level data for the first quarter revealed significant revisions. Real value added for private goods-producing industries was revised down to a 1.5 percent increase, a substantial downward adjustment of 3.0 percentage points. In contrast, private services-producing industries saw an upward revision to 2.1 percent growth, an increase of 1.3 percentage points. Government sectors experienced a downward revision to 6.3 percent growth, a decrease of 1.2 percentage points.
Real gross output for the first quarter was revised up to a 2.3 percent increase, a 0.6 percentage point upward adjustment. Private goods-producing industries saw a downward revision to a 0.9 percent decrease, while private services-producing industries were revised up to a 2.9 percent increase. Government sectors were revised up to a 5.3 percent increase.
Inflationary measures for the first quarter also saw revisions. The price index for gross domestic purchases was revised down to a 3.2 percent increase, a 0.4 percentage point downward adjustment. The PCE price index was also revised down to a 4.2 percent increase, and the core PCE price index excluding food and energy was revised down to a 3.9 percent increase.
Real GDI for the first quarter was significantly revised upward to a 2.5 percent increase, a 1.3 percentage point improvement. This revision was primarily driven by updated wage and salary data from the U.S. Bureau of Labor Statistics. The average of real GDP and real GDI for the first quarter was also revised upward to a 2.5 percent increase, an 0.8 percentage point gain. Corporate profits from current production for the first quarter were revised down by $11.0 billion to an estimated increase of $63.4 billion.
The next release of GDP data, the advance estimate for the third quarter of 2026, is scheduled for October 29, 2026, at 8:30 a.m. EDT, providing the next snapshot of the nation’s economic performance.