Layla Zulfa
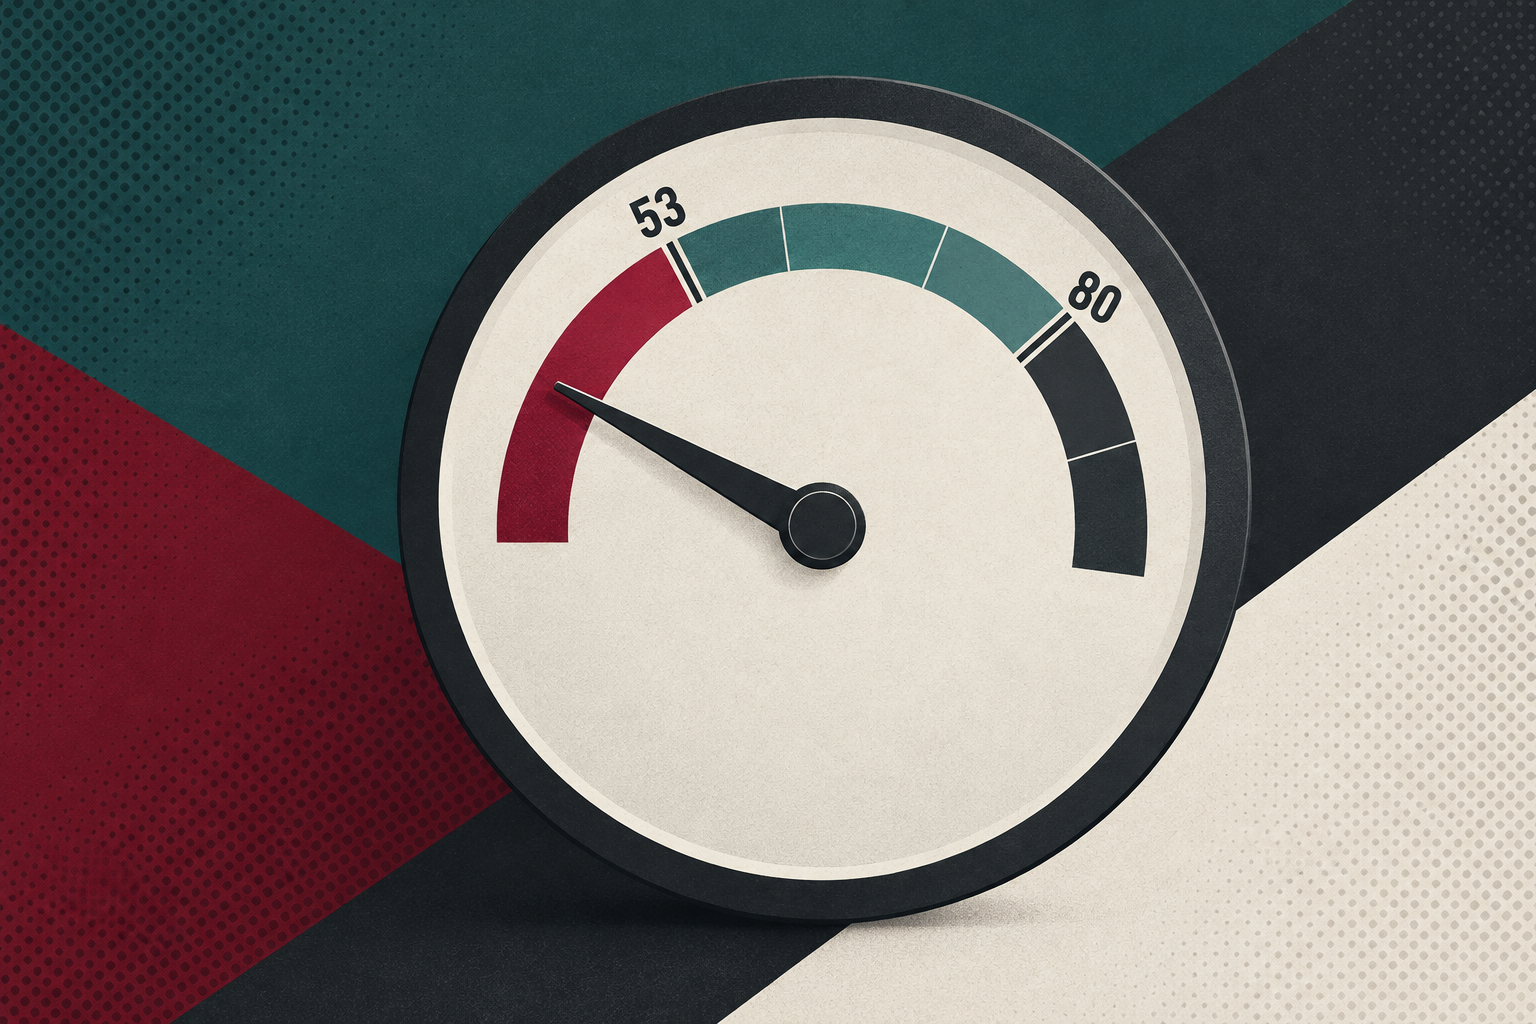
Garrett, McAuley & Co., a prominent consulting firm specializing in the banking and mortgage banking sectors, has officially launched the PULSE Subservicer Benchmark, a comprehensive new tool designed to objectively measure and compare the performance of mortgage subservicers. This initiative, born from extensive feedback and direct input from 53 mortgage banking firms across the nation, aims to address a critical gap in the industry by providing lenders with data-driven insights into their subservicing relationships. The initial findings highlight a substantial performance disparity among providers, with a notable 27-point difference observed between the highest and lowest-rated entities on a 100-point scale.
The PULSE (Performance, Usability & Lifecycle Servicer Evaluation) Subservicer Benchmark represents a significant advancement in how lenders evaluate the critical function of subservicing. Traditionally, the selection of a subservicer has often been based on less rigorous criteria, such as sales pitches and limited reference checks, with ongoing performance monitoring being a rarity. This new benchmark directly confronts this issue by systematically gathering data from lenders who actively utilize these services.
Genesis and Methodology of the PULSE Benchmark
The development of the PULSE Subservicer Benchmark was a response to a perceived need within the mortgage industry for a more transparent and standardized method of assessing subservicer capabilities. Garrett, McAuley & Co. recognized that while lenders rely heavily on subservicers for crucial operational tasks, the mechanisms for holding these providers accountable for their performance were often insufficient. The firm engaged with 53 mortgage banking firms, representing a diverse cross-section of the market, to gather their candid feedback and experiences.
The survey methodology was designed to capture a holistic view of the subservicing relationship, encompassing five key categories:
- Service Quality: This category likely assesses the overall responsiveness, accuracy, and efficiency of the subservicer’s operations, including areas like loan boarding, payment processing, and customer support for both the lender and the borrower.
- Borrower Experience: Focusing on the end-user, this metric evaluates how effectively the subservicer manages borrower interactions, inquiries, payment portals, and overall satisfaction from the homeowner’s perspective.
- Escrow and Default Handling: This critical area examines the subservicer’s proficiency in managing borrower escrow accounts, including timely tax and insurance payments, as well as their effectiveness in navigating and mitigating mortgage defaults and loss mitigation processes.
- Recapture and Marketing Support: This category specifically targets the subservicer’s role in helping lenders retain their existing customer base by facilitating recapture strategies and providing marketing support for retention efforts.
- Operational Friction: This metric aims to quantify the ease or difficulty lenders experience in working with their subservicer, identifying any inefficiencies, communication breakdowns, or integration challenges that create administrative burdens.
Each of these categories was weighted and scored, culminating in a composite score for each subservicer evaluated. The benchmark’s 100-point scale allows for clear differentiation and provides a tangible measure of performance.
Key Findings: Performance Disparities and Underperforming Areas
The inaugural PULSE Subservicer Benchmark revealed a wide spectrum of performance among the evaluated subservicers. Composite scores varied significantly, ranging from a low of 53 to a high of 80, indicating a substantial gap in the quality of service and operational effectiveness provided by different entities in the market. This broad range suggests that lenders have vastly different experiences depending on their chosen subservicer.
The most striking finding, however, was the consistently low performance in the recapture and marketing support category. This area received the lowest average scores across the surveyed firms, highlighting a significant unmet need. The benchmark report indicates that among the 53 respondents, 45 had already completed their 2025 Home Mortgage Disclosure Act (HMDA) filings. These firms collectively estimated that they left approximately $12.7 billion in potential production volume untapped due to inadequate subservicer support in recapture initiatives. This figure represents a considerable financial opportunity cost for lenders, underscoring the critical importance of effective recapture strategies.
Furthermore, the survey uncovered a concerning lack of proactive performance evaluation by many lenders. A significant 25% of respondents admitted to never having conducted a formal, independent evaluation of their subservicing relationship. This suggests a passive approach to managing one of the most crucial outsourced functions in the mortgage lifecycle.
The reluctance to switch subservicers, even among those with below-median satisfaction scores, was also a notable finding. A substantial 56% of respondents cited transfer risk and disruption as the primary reasons for remaining with their current subservicer. This fear of the unknown and the potential operational upheaval associated with migrating loan portfolios appears to be a significant barrier to lenders seeking better service.
Context and Implications for the Mortgage Industry
The launch of the PULSE Subservicer Benchmark arrives at a pivotal moment for the mortgage industry. Following a period of intense volume and subsequent market normalization, lenders are increasingly focused on operational efficiency, cost containment, and maximizing revenue from their existing customer base. Subservicing plays an integral role in all these areas.
Historically, the subservicing market has evolved to support lenders in managing the complexities of loan administration, regulatory compliance, and borrower communication. As the mortgage landscape has become more competitive, the value proposition of a subservicer has expanded beyond basic loan accounting to include strategic partnerships that can drive profitability.
The significant performance gaps identified by the PULSE benchmark suggest that not all subservicers are keeping pace with these evolving expectations. Lenders who are unaware of these disparities may be unknowingly accepting suboptimal service levels, leading to higher operational costs, reduced borrower satisfaction, and missed revenue opportunities, particularly in the crucial area of loan recapture.
The finding regarding the $12.7 billion in missed production volume due to weak recapture support is particularly alarming. In a market where originations can fluctuate, retaining existing borrowers is a stable and often more profitable source of new business. A subservicer’s ability to provide data analytics, targeted marketing campaigns, and seamless refinancing options is paramount to helping lenders achieve this. The benchmark’s data implies that many subservicers are failing to deliver on this critical aspect of their service offering.
The prevalent fear of transfer risk also points to a need for greater transparency and confidence in the subservicing transition process. Lenders are understandably cautious about disrupting established systems and processes, but the benchmark suggests that the perceived risks may be outweighing the potential benefits of switching to a higher-performing provider. This could lead to a self-perpetuating cycle where underperforming subservicers retain clients due to inertia, rather than merit.
The PULSE Benchmark Platform and Future Outlook
The PULSE Subservicer Benchmark is not merely a static report; it includes a secure, proprietary portal for each participating lender. This platform provides a dynamic and personalized view of their subservicer’s performance. Lenders can compare their subservicer’s metrics against an anonymized peer group, offering valuable context and identifying specific areas of strength or weakness.
The portal delivers:
- Composite Satisfaction Scores: An aggregated measure of overall satisfaction with the subservicer.
- Category-Specific Comparisons: Detailed breakdowns of performance across the five surveyed categories, allowing lenders to pinpoint where their subservicer excels or falters.
- Question-Level Data: Granular insights into specific survey responses, providing a deeper understanding of the underlying feedback.
- Operational Pain-Point Rates: Data highlighting common challenges and inefficiencies reported by lenders.
- Peer Satisfaction Distributions: Visualizations showing how a subservicer’s performance compares to the broader market.
- Custodial Oversight Benchmarks: Insights into best practices and performance standards for custodial services, a critical component of subservicing.
The benchmark also includes an illustrative estimation of recapture opportunities, leveraging public HMDA origination data to provide a tangible financial perspective on potential gains. While peer subservicers are identified anonymously within the platform to maintain confidentiality, each participating firm receives a confidential report detailing their specific findings.
Garrett, McAuley & Co. intends for the PULSE Subservicer Benchmark to become an annual or semi-annual event, providing a consistent and evolving measure of the subservicing landscape. The firm’s managing director, Steve Stone, emphasized the benchmark’s mission: “Most lenders pick a subservicer based on a pitch deck and a reference call, then never measure the relationship again.” The PULSE Benchmark aims to fundamentally alter this practice, encouraging continuous evaluation and accountability.
Expert Reactions and Industry Perspectives (Inferred)
While direct quotes from other industry participants were not included in the initial summary, the launch of such a benchmark is likely to elicit a range of reactions.
From Lenders: Many lenders who participated in the survey are likely to find the benchmark invaluable. It provides objective data that can be used to validate existing relationships, negotiate better terms, or justify a change in subservicer. Those who have felt “in the dark” about their subservicer’s performance will now have concrete evidence to guide their decisions. The fear of transfer risk may be mitigated as more lenders gain confidence in identifying reliable, high-performing providers.
From Subservicers: Reputable subservicers who consistently deliver high-quality service are likely to welcome the benchmark as an opportunity to differentiate themselves in the market. Those with lower scores will face pressure to improve their offerings and address the identified shortcomings, particularly in recapture and marketing support. This could spur innovation and a greater focus on lender partnership.
From Regulators and Industry Watchdogs: Tools like the PULSE Benchmark contribute to greater transparency and accountability within the financial services sector. By highlighting areas of underperformance, it can indirectly influence best practices and encourage more robust oversight of critical outsourced functions.
Broader Impact and Future of Subservicing
The PULSE Subservicer Benchmark has the potential to significantly reshape the dynamics of the mortgage subservicing market. By introducing a standardized, data-driven evaluation framework, Garrett, McAuley & Co. is empowering lenders with the information they need to make more informed strategic decisions.
The focus on recapture and marketing support is particularly prescient. As the mortgage market matures and interest rates stabilize, the ability to retain and grow an existing loan portfolio will become an increasingly critical differentiator for lenders. Subservicers that can demonstrably contribute to these efforts will likely command a premium and gain a competitive edge.
The benchmark’s success could also pave the way for similar initiatives in other areas of mortgage outsourcing, fostering a culture of greater transparency and performance measurement across the industry. Ultimately, the PULSE Subservicer Benchmark serves as a crucial step towards elevating the subservicing function from a back-office necessity to a strategic partnership that drives lender success. The ongoing data collection and analysis from this initiative will undoubtedly provide a valuable longitudinal view of the subservicing market’s evolution in the years to come.