Layla Zulfa
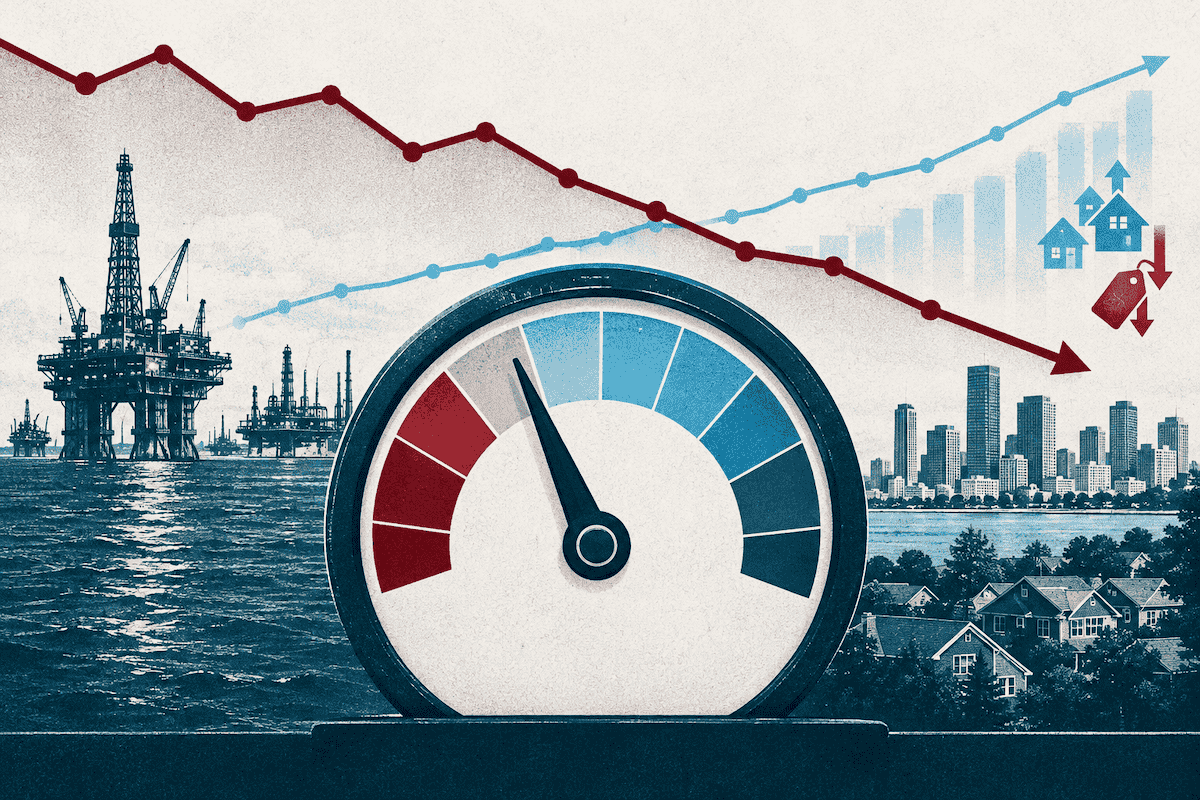
The relentless slide in housing demand experienced in recent weeks has found a temporary reprieve, driven by a modest easing of mortgage rates. Following a peak around 7.60%, mortgage rates have receded towards the 7.30% mark, providing a much-needed breather for the market. This shift occurred during one of the bond market’s more volatile periods in 2026, signaling a potential turning point as the year draws to a close. As the final week of October unfolds, a comprehensive review of the 10-year Treasury yield, mortgage rates, and housing demand offers crucial insights into the trajectory of the real estate market for the remainder of the year.
The Interplay of 10-Year Yield and Mortgage Rates
The bond market has been a significant driver of recent financial news, exhibiting considerable fluctuations. The 10-year Treasury yield, a key benchmark for long-term interest rates including mortgages, has been under intense scrutiny. For much of the recent past, the critical level of 5.35% has acted as a significant psychological and technical support. Despite persistent upward pressure from elevated oil prices and robust economic data, this crucial threshold held firm last week. A contributing factor to this resilience was a perceived cooling in the narrative surrounding artificial intelligence (AI) investments, which had previously fueled demand for Treasury bonds. Consequently, the 10-year yield retreated below the 5% mark, translating into a slight decrease in mortgage rates from their recent highs. This development has largely allayed immediate fears of mortgage rates soaring to 8% or even 9%, a scenario that had been a significant concern for market participants. The stability of the 10-year yield below 5.35% is now seen as a pivotal factor in de-escalating these anxieties and potentially stabilizing oil prices.
Examining Mortgage Spreads: A Measure of Risk
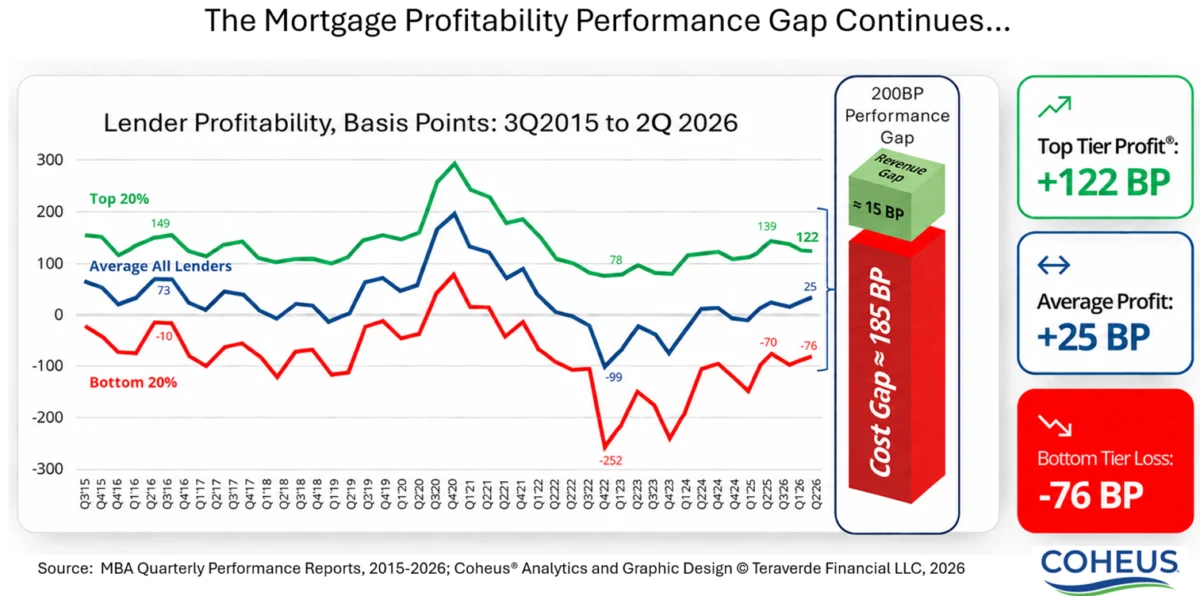
Beyond the headline mortgage rate, the "mortgage spread" provides critical insight into the profitability and risk premium demanded by mortgage lenders. This spread represents the difference between the yield on mortgage-backed securities and the yield on a benchmark Treasury security of similar maturity. While mortgage spreads have widened from their earlier lows in 2026, they remain within historical proximity to cycle lows observed since the Federal Reserve’s rate-hiking cycle commenced in 2022.
The optimal range for mortgage spreads, according to market analysts, is typically closer to 2% than 3%. A widening spread suggests increased perceived risk or reduced profitability for lenders, which can translate into higher borrowing costs for consumers, even if the underlying Treasury yields remain stable. Conversely, tighter spreads indicate a more favorable lending environment.
Last week, mortgage spreads experienced a slight increase, rising to 2.23% from 2.21% the previous week. While this represents a marginal widening, it is important to note that sharp movements in the 10-year Treasury yield can often lead to temporary widening of mortgage spreads. This phenomenon is attributed to the inherent design of mortgage-backed securities, which are structured to mitigate volatility. Therefore, the recent uptick in spreads can be seen as a predictable, albeit concerning, reaction to the downward movement in the 10-year yield.
Historically, mortgage spreads have often fluctuated between 1.60% and 1.80%. The current levels, while elevated compared to this historical norm, are still not indicative of extreme distress within the mortgage market. However, any sustained widening beyond the 2% threshold warrants close observation as it could signal a more significant impediment to housing affordability.
Weekly Pending Home Sales: A Pulse on Demand
The weekly pending home sales data offers a granular, week-to-week perspective on housing market activity. While susceptible to short-term fluctuations due to holidays or unforeseen events, this data typically provides a leading indicator for future sales, reflecting trends that materialize in broader sales figures within 30 to 60 days.
Last week’s data provided a welcome signal of stabilization, marking the end of a sustained decline in housing demand. As mortgage rates softened slightly, the week-to-week print for pending sales registered a modest positive uptick. However, market observers caution against overemphasizing this single-week improvement. The underlying trend had been one of accelerating deceleration, and it requires a relatively small positive shift to halt a downward trajectory.
Historically, housing demand exhibits robust growth when mortgage rates remain below the 6.64% threshold. The first half of 2026, characterized by rates below this level, saw consistent demand expansion, with only seasonal factors like holidays and adverse weather conditions posing temporary headwinds. Conversely, mortgage rates consistently above 7% have historically correlated with softer pending sales data over the past three years and ten months, underscoring the sensitivity of buyer activity to borrowing costs.
Purchase Applications: A Forward-Looking Indicator
Purchase application data, which offers a more forward-looking view of the market by assessing buyer intent over a 30-90 day horizon, has shown signs of weakening. This softening is directly linked to the recent surge in mortgage rates above the 6.64% mark, and more recently, above 7%. The latest weekly print, however, does not yet fully incorporate the impact of the most recent rate movements, leaving the market to anticipate whether next week’s data will reflect a return to week-to-week growth.
The damage inflicted by mortgage rates exceeding 7% is evident in the current purchase application figures, which show a decline both week-over-week and year-over-year. This indicates a tangible reduction in buyer confidence and a hesitation to enter the market due to affordability concerns. The consistent decline suggests that a significant portion of potential buyers are either priced out or are opting to postpone their homeownership plans until borrowing costs become more manageable.
Housing Inventory: A Slowing Growth Trajectory
Housing inventory has experienced a comparatively subdued growth trend throughout 2026, with some weeks even registering year-over-year declines. However, a consistent pattern observed in the market is that rising mortgage rates, particularly when they breach the 7% threshold, tend to stimulate faster inventory growth. This occurs as some homeowners, previously disinclined to sell due to the prospect of taking on a higher mortgage rate for their next home, may become more motivated to list their properties.
The slower inventory growth observed this year, relative to historical norms, can be partly attributed to the market being closer to more normalized inventory levels compared to previous years. Nevertheless, inventory has shown an uptick since mid-August. The year-over-year comparisons are becoming more favorable for reporting growth, largely because mortgage rates were approximately 1% lower during the same period in the previous year, and demand was approaching a nine-month high in December 2025. Despite these easier comparative bases, inventory growth is currently reported at a modest 5.68%. This figure, while positive, suggests that the supply side of the market is not yet experiencing a significant surplus, a factor that could further influence price dynamics.
New Listings: A Seasonal Shift and a Potential Concern
New listings of homes for sale are currently following their typical seasonal decline, a pattern observed annually as the year draws to a close. However, 2026 has been a relatively healthy year for new listings, with weekly figures occasionally surpassing 80,000. A potential concern emerging at current interest rate levels is the possibility that some sellers, who are also potential homebuyers, may hold back from listing their properties. This is due to the prospect of needing to secure a new mortgage at a higher rate.
This past week, new listings experienced a year-over-year decline, a development that warrants close monitoring. While it is too early to definitively label this as a sustained trend, it is a factor that market analysts will be observing closely for the remainder of the year. If this decline persists, it could contribute to tighter inventory conditions in the coming months, especially if demand were to rebound. Despite this recent dip, 2026 has generally been a strong year for new listings compared to recent years.
In a typical market environment, weekly new listings during peak periods often range from 80,000 to 100,000. For historical context, during the height of the previous housing bubble, new listings regularly exceeded 250,000 to 400,000 per week for several years. The current levels, therefore, indicate a market that is far from being oversaturated with new supply.
Price Cut Percentage: Reflecting Shifting Market Dynamics
The percentage of homes experiencing price reductions before selling is a key indicator of market heat and seller willingness to adjust expectations. Typically, around one-third of homes see price reductions, reflecting the dynamic nature of the housing market. Throughout much of 2026, the overall price-cut percentage has been lower than in the preceding year.
However, this trend began to shift as mortgage rates climbed above 6.64% and subsequently surpassed the 7% mark. With demand showing signs of softening at these higher rate levels, the price-cut percentage has seen a marginal increase, now standing at 1% higher year-over-year. This suggests that sellers are beginning to acknowledge the impact of higher borrowing costs on buyer purchasing power and are consequently becoming more amenable to price adjustments.
Looking ahead to the full year, the forecast for national home price appreciation predicted a modest decline of -0.62%. However, based on current home-price index data, which shows growth between 1% and 2%, achieving this projected decline may prove challenging. The resilience of home prices, despite rising rates and softening demand, points to underlying factors such as limited inventory and persistent buyer demand at certain price points.
The Week Ahead: Geopolitical Tensions, Economic Indicators, and Federal Reserve Policy
The upcoming week is poised to be a significant one for financial markets, with several key factors likely to influence mortgage rates and the broader economy. Geopolitical developments, particularly concerning oil prices and the conflict in Iran, remain a primary concern. Oil prices are currently at yearly highs, and any escalation of tensions in the Middle East could lead to further price increases, thereby putting upward pressure on inflation and interest rates. Iran’s potential actions to further elevate oil prices, potentially in coordination with other nations like China seeking to influence domestic political outcomes, could create additional volatility.
The narrative surrounding artificial intelligence (AI) continues to be a closely watched economic story. Investors and analysts will be observing whether high-yield credit spreads widen, which would signal increased difficulty in funding new AI projects and potentially a broader reassessment of technology sector valuations.
Of paramount importance is the Federal Reserve’s upcoming policy meeting. While the market has largely priced in the likelihood of no immediate rate changes, the accompanying statement and press conference will be scrutinized for any signals regarding the future path of monetary policy. For market participants, the primary objective for October has been to prevent the 10-year Treasury yield from closing above the critical 5.35% level, which could have triggered a more significant escalation of interest rates. The ability to maintain the 10-year yield below this threshold through the end of the month will be considered a significant victory for market stability. The interplay of these factors will undoubtedly shape the outlook for mortgage rates and the housing market as the year concludes.