Candice Horbacz
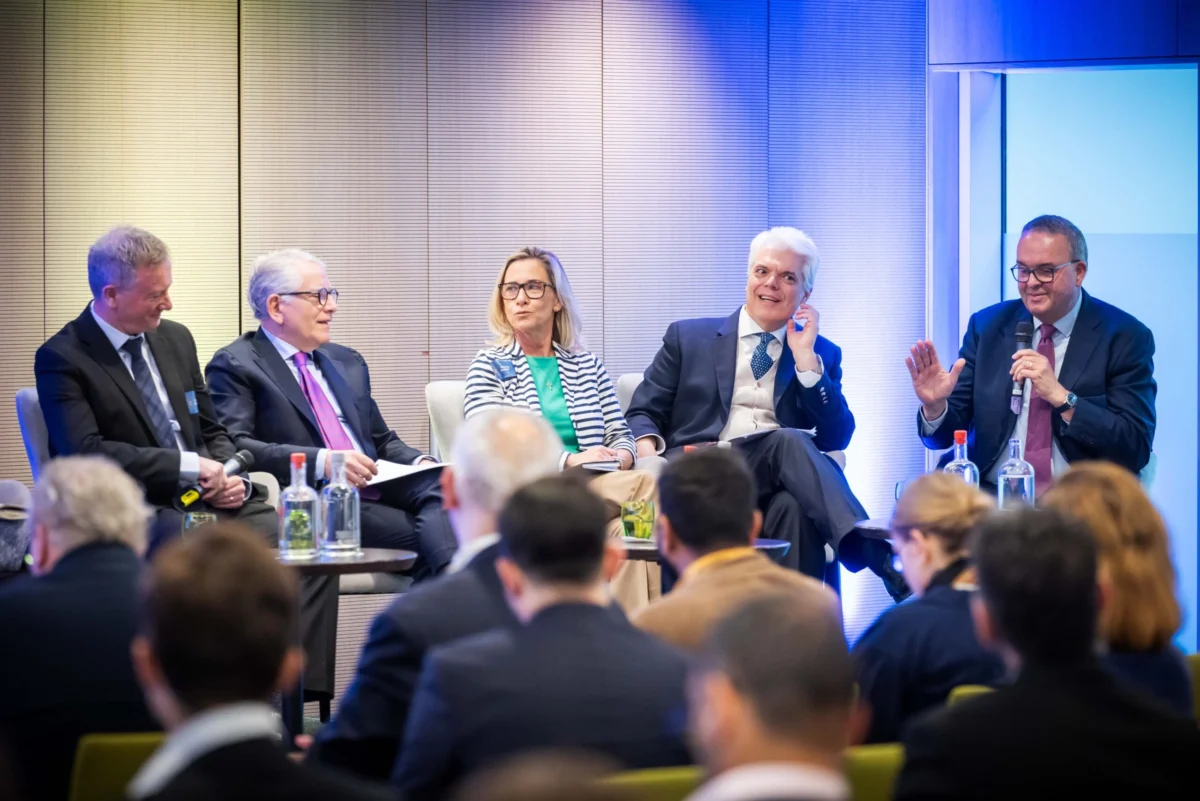
The convergence of technological advancement, shifting geopolitical landscapes, and evolving economic models is profoundly reshaping the international tax environment, prompting an urgent re-evaluation of national and multilateral fiscal strategies. A recent high-level forum brought together leading experts to dissect these intricate challenges, focusing on the transformative impact of artificial intelligence, the electoral dynamics shaping French tax policy, the latest developments in European Union tax legislation, and the complex interplay of investment and competition amidst global trade tensions. This comprehensive discussion underscored the imperative for adaptable, equitable, and innovation-friendly tax frameworks in an era of unprecedented disruption.
The Main Facts: A Multidimensional Challenge
The core discussions revolved around four critical pillars: the foundational disruption brought by Artificial Intelligence (AI) to labor markets and tax revenues; the immediate implications of French electoral outcomes on national and EU fiscal priorities; the ongoing legislative evolution within the EU, particularly regarding administrative cooperation and global minimum tax efforts; and the intricate dance between foreign direct investment (FDI) and tax competition in a protectionist global trade climate. Each session highlighted a distinct facet of the modern tax landscape, yet collectively painted a picture of a system under immense pressure to adapt to rapid change.
Chronology of Emerging Fiscal Challenges
The current discourse around tax policy is not a sudden phenomenon but the culmination of several overlapping trends that have accelerated in recent years. The rise of digital economies in the early 2000s first challenged traditional notions of physical presence for taxation, leading to fragmented national digital services taxes and, eventually, the OECD’s ambitious Two-Pillar Solution. Simultaneously, growing awareness of climate change spurred the development of green taxation and carbon pricing mechanisms. More recently, the COVID-19 pandemic exposed vulnerabilities in global supply chains and amplified calls for robust public financing, while also accelerating digital transformation across industries. The past five years have seen an unprecedented pace of legislative activity, particularly within the EU, aimed at enhancing tax transparency, combating aggressive tax planning, and ensuring fairer contributions from multinational enterprises (MNEs). The advent of advanced AI now introduces another layer of complexity, promising to further disrupt labor markets and traditional revenue streams, making the present moment a critical juncture for policymakers worldwide.
The AI Revolution: Redefining Labor, Competition, and Innovation in Tax
The keynote address, "AI, disruption, and the future of tax: labor revenue, competition, and innovation," served as a stark reminder of the impending paradigm shift. AI is no longer a futuristic concept but an integral part of industrial transformation, poised to redefine work, productivity, and wealth creation. Experts underscored that while AI promises immense economic gains—with some projections indicating a boost to global GDP by trillions of dollars over the next decade—it also presents profound challenges to existing tax structures.
The primary concern centers on labor revenue. As AI and automation become more sophisticated, they are expected to displace certain categories of human labor, while simultaneously creating new jobs that often require different skill sets. This shift will inevitably impact income tax bases, social security contributions, and overall government revenue. Policymakers must grapple with how to tax automated production and capital income effectively, ensuring that the benefits of AI are broadly shared and that public services remain adequately funded. Discussions explored potential solutions, such as "robot taxes" or adjustments to capital gains taxes, alongside the need for robust retraining programs funded through adaptive fiscal mechanisms.
Competition among nations is another critical dimension. Countries will increasingly vie to attract AI talent, research, and development hubs. This could lead to new forms of tax competition, where jurisdictions offer tailored incentives—such as enhanced R&D tax credits, accelerated depreciation for AI-related investments, or favorable intellectual property regimes—to foster innovation within their borders. The challenge lies in ensuring that this competition remains "healthy," promoting genuine innovation rather than a destructive race to the bottom that erodes global tax bases.
Finally, innovation itself is inextricably linked to tax policy. Well-designed tax systems can incentivize investment in AI research, facilitate the commercialization of new technologies, and support the growth of AI-driven industries. Conversely, outdated or burdensome tax regulations could stifle innovation, pushing cutting-edge companies to more favorable jurisdictions. The keynote emphasized the need for agile tax policy that can evolve alongside technological advancements, creating an environment where AI can flourish while contributing equitably to public finances. The discussion highlighted the urgency of developing new metrics to measure economic activity and value creation in an AI-driven economy, moving beyond traditional indicators that may soon become obsolete.
French Elections and the European Fiscal Tapestry
The session "How Elections Will Shape French Tax Policy" offered a crucial deep dive into the domestic and European implications of French political shifts. France, a founding member of the European Union and a significant economic power, often sets precedents or significantly influences EU-wide policies. The outcome of presidential and parliamentary elections invariably dictates the country’s fiscal trajectory, impacting not only its national budget but also its stance on broader EU priorities.
Analysts highlighted that recent French electoral cycles have consistently featured robust debates over tax policy, reflecting differing philosophies on economic growth, social welfare, and fiscal responsibility. Presidential candidates typically propose diverse tax agendas, ranging from corporate tax cuts aimed at boosting competitiveness and attracting foreign investment, to adjustments in wealth taxation, income tax brackets, and social contributions designed to address inequality or fund public services. For instance, proposals for further reductions in corporate income tax—which has seen a gradual decrease from over 33% to 25% in recent years—are often weighed against maintaining a robust social safety net.
The French budget is directly shaped by these policy choices. A new president’s agenda could significantly alter revenue forecasts, expenditure patterns, and ultimately, the national deficit and public debt levels, which are closely scrutinized under the EU’s Stability and Growth Pact. France’s commitment to reducing its public debt, which currently stands at over 110% of GDP, is a recurring theme. Moreover, French tax decisions have a direct bearing on EU priorities. France plays a pivotal role in shaping the EU’s common agenda, particularly concerning fiscal harmonization, digital taxation, and green policies. A more nationally focused tax agenda could potentially create friction with EU-level efforts towards greater integration, while a pro-European stance might accelerate initiatives like common EU tax bases or new "own resources" for the EU budget.
The session also explored strategies for making France more competitive. Policymakers face the dual challenge of attracting investment and talent while maintaining a strong social model. Proposed measures often include simplifying the complex French tax code, enhancing research and development tax credits, and improving the overall business environment. For example, France’s "Crédit Impôt Recherche" (CIR) is one of the most generous R&D tax credits in Europe, designed to incentivize innovation. However, discussions often revolve around whether such measures are sufficient to compete with lower-tax jurisdictions or those with more streamlined administrative processes. The interplay between national sovereignty in tax matters and the increasing pressure for EU-level coordination remains a delicate balancing act, with French leadership often instrumental in brokering compromises.
The Latest on EU Tax Policy: Towards Greater Integration and Transparency
The European Union continues to be a hotbed of tax policy innovation and coordination, driven by the imperatives of a single market, combating tax evasion, and funding common priorities. The session on "The Latest on EU Tax Policy" provided a comprehensive update on several critical initiatives.
The Multiannual Financial Framework (MFF) and own resources formed a central part of the discussion. The MFF is the EU’s long-term budget, typically spanning seven years, which outlines expenditure ceilings for various policy areas. To fund this ambitious framework, the EU has been actively exploring new "own resources" to reduce its reliance on national contributions. These include potential revenues from the Carbon Border Adjustment Mechanism (CBAM), a revised Emissions Trading System (ETS), a digital levy, and a financial transaction tax. The implementation of such resources is crucial for the EU’s financial autonomy and its ability to fund its green and digital transitions.
The Omnibus package refers to broad legislative proposals that often consolidate various amendments or introduce new measures across different tax directives. While the specifics can vary, such packages typically aim to streamline existing rules, enhance administrative cooperation, or adapt tax law to new economic realities. These packages are essential for maintaining the coherence and effectiveness of the EU’s extensive body of tax legislation.
A significant focus was placed on the DAC recast, referring to the Directive on Administrative Cooperation (DAC). The DAC framework has progressively expanded since its inception (DAC1 to DAC7), enhancing information exchange between member states to combat tax evasion and avoidance. The "recast" signifies a comprehensive overhaul or significant amendment, likely aiming to further broaden the scope of information exchange, incorporate new types of income or assets (e.g., crypto-assets as per DAC8), and improve the efficiency of data sharing. The EU’s commitment to greater tax transparency is unwavering, and the DAC framework is its primary tool in this endeavor.
Progress on Pillar One of the OECD/G20 Inclusive Framework’s Two-Pillar Solution was also a key topic. Pillar One aims to reallocate a portion of the profits of the largest and most profitable multinational enterprises (MNEs) to market jurisdictions where their users and customers are located, regardless of physical presence. While a political agreement was reached in 2021, its implementation has faced significant hurdles, including legislative delays in various countries and the need for a multilateral convention. The session highlighted the complexities of translating this agreement into effective domestic law and the ongoing efforts to overcome remaining obstacles to ensure a fairer distribution of taxing rights in the digital age.
Finally, the Mobility Map refers to the intricate tax challenges associated with cross-border labor mobility within the EU. With increasing numbers of employees working remotely across borders, or commuting between member states, issues such as social security coordination, avoiding double taxation, determining tax residency, and the allocation of taxing rights for remote workers have become paramount. The EU is actively working on guidelines and potential legislative solutions to ensure legal certainty and prevent both double taxation and non-taxation for mobile workers, reflecting the realities of a more flexible and integrated European labor market.
Investment and Competition in an Era of Trade Wars
The global economic landscape is increasingly characterized by rising protectionism and trade tensions, often termed "trade wars," which significantly impact foreign direct investment (FDI) patterns and redefine tax competition. The session "Investment and Competition in an Era of Trade Wars" explored this complex interplay.
The resurgence of tariffs and non-tariff barriers, particularly evident in recent US-China trade disputes and other geopolitical tensions, has prompted MNEs to reconsider their global supply chain strategies. Companies are increasingly looking at reshoring, nearshoring, or diversifying their production bases to mitigate risks associated with trade barriers. This shift directly influences foreign direct investment decisions, as companies evaluate potential locations not only for labor costs or market access but also for their exposure to geopolitical risks and trade tariffs.
In this context, Pillar Two of the OECD/G20 Inclusive Framework takes on added significance. Pillar Two introduces a global minimum corporate tax rate of 15% for large MNEs, aiming to curb base erosion and profit shifting (BEPS). Its implementation means that jurisdictions can no longer solely rely on extremely low corporate tax rates to attract FDI. If an MNE pays less than 15% effective tax in one jurisdiction, its home country or other jurisdictions where it operates can levy a top-up tax. This fundamentally alters the landscape of tax competition. Companies will need to factor the 15% minimum tax into their location decisions, shifting the focus from headline tax rates to other determinants like skilled labor, infrastructure, regulatory stability, and market access. The session discussed how countries are adapting their tax incentive regimes to remain attractive within this new minimum tax framework.
The concept of healthy tax competition was a central theme. Experts distinguished this from a "race to the bottom," where countries aggressively lower tax rates to unsustainable levels, eroding public finances. Healthy competition, in contrast, involves jurisdictions competing on genuine economic fundamentals: providing a skilled workforce, robust infrastructure, a stable legal and regulatory environment, and efficient public services. Tax policy still plays a role, but it shifts towards offering well-targeted incentives for specific activities like R&D, innovation, or green investments, rather than broad-based tax holidays. The challenge for policymakers is to design tax systems that attract high-quality investment and foster economic growth without undermining global tax fairness or contributing to a cycle of revenue erosion. The discussion also touched upon the growing importance of non-tax incentives, such as streamlined permitting processes, access to capital, and strong intellectual property protections, in an environment where basic tax rates are increasingly standardized.
Official Responses and Broader Implications
While no direct quotes were provided from specific officials, the themes implicitly reflect the ongoing dialogues and policy directions emanating from major international bodies and national treasuries. Tax experts and policymakers, both at national and supranational levels, consistently emphasize the need for coordination and adaptability. The European Commission, for instance, has been a strong advocate for deeper tax harmonization and the implementation of global agreements like Pillar Two, viewing them as essential for the integrity of the single market and ensuring fair competition.
Industry leaders, represented by various business federations, often express concerns about complexity and compliance burdens. While acknowledging the need for fair taxation, they advocate for clear, consistent, and administratively simple tax rules that do not impede investment or innovation. The global business community is closely monitoring the implementation of Pillar Two and the evolving landscape of digital taxation, seeking certainty in an otherwise turbulent environment.
The broader implications of these interconnected trends are profound. The global tax system is undergoing its most significant transformation in decades, driven by technological change, geopolitical shifts, and a renewed emphasis on fairness and sustainability. For businesses, this means navigating an increasingly complex and fragmented regulatory environment, requiring greater foresight in tax planning and supply chain management. For governments, the challenge lies in designing tax policies that are robust enough to fund essential public services, flexible enough to adapt to rapid economic shifts, and competitive enough to attract and retain vital economic activity. The discussions highlighted a collective recognition that the future of taxation will require continuous dialogue, multilateral cooperation, and a willingness to rethink long-held assumptions about how economies create value and how that value should be taxed for the common good. The era of unilateral tax measures appears to be receding, replaced by an urgent, if sometimes contentious, push towards a more coordinated and transparent global fiscal architecture.