Lana Rhoades
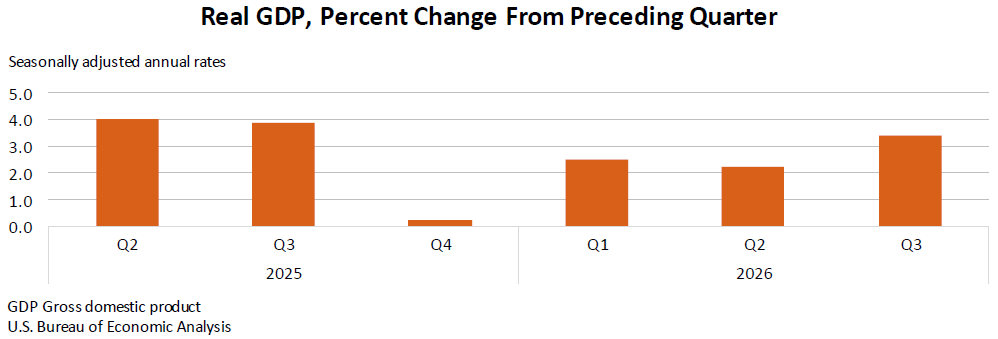
The United States economy demonstrated significant resilience and expansion in the third quarter of 2026, as real gross domestic product (GDP) surged at an annual rate of 3.4 percent. This accelerated growth, encompassing the months of July, August, and September, marks a notable uptick from the 2.2 percent increase observed in the second quarter. The advance estimate, released today by the U.S. Bureau of Economic Analysis (BEA), paints a picture of an economy propelled by robust investment, sustained consumer spending, and increased government expenditure.
This latest economic performance provides a crucial snapshot of the nation’s economic health as policymakers, businesses, and consumers navigate a dynamic global landscape. The BEA’s data serves as a vital indicator, offering insights into the underlying strengths and potential headwinds shaping the economic trajectory.
Drivers of Third-Quarter Expansion
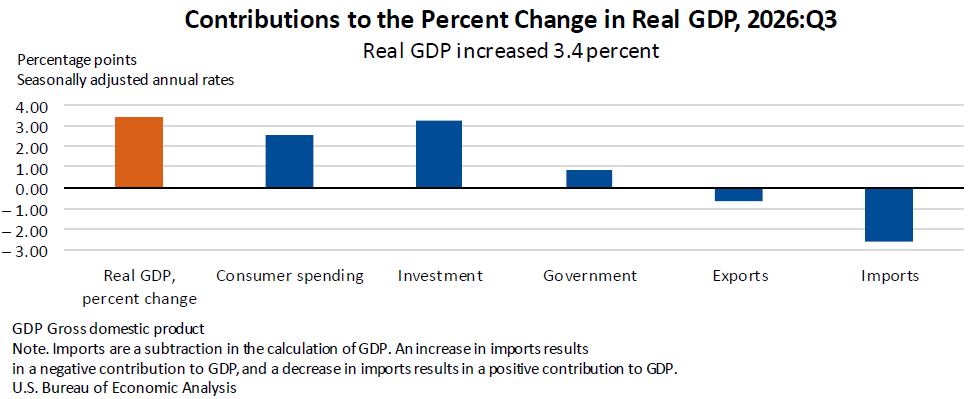
The impressive 3.4 percent annualized growth in real GDP during the third quarter was driven by a confluence of positive economic forces. Key among these were substantial increases in investment, a cornerstone of future economic productivity and innovation. Consumer spending, representing a significant portion of U.S. economic activity, also contributed positively, reflecting continued confidence and purchasing power among households. Furthermore, government spending played a supportive role, indicating fiscal policy initiatives aimed at bolstering economic activity.
However, this upward momentum was partially tempered by a decrease in exports, suggesting a more challenging environment for American goods and services in international markets. Additionally, imports, which are subtracted in the calculation of GDP, saw an increase. While higher imports can signify strong domestic demand, they also represent a drag on the net trade balance.
A deeper dive into the components reveals that the acceleration in real GDP from the second to the third quarter was primarily fueled by a notable acceleration in investment. This suggests that businesses were actively deploying capital into fixed assets, research and development, and inventory, signaling optimism about future demand and profitability. Alongside this, a positive shift in government spending, moving from a potential drag or stagnation in the previous quarter to a contributing factor, provided an additional boost. These positive contributions were partially offset by a downturn in exports, which experienced a greater contraction in the third quarter compared to the second. The increase in imports also outpaced that of the previous quarter, further influencing the net GDP calculation.
Private Sector Strength Underscored
Highlighting the underlying strength of domestic economic activity, real final sales to private domestic purchasers—a measure that excludes inventories and government purchases—showed a healthy increase of 4.9 percent in the third quarter. This figure represents a slight acceleration from the 4.6 percent growth recorded in the second quarter. This metric is particularly important as it reflects the demand for goods and services by consumers and businesses, independent of inventory fluctuations or government interventions. The continued robust growth in this area suggests that the private sector remains a powerful engine of economic expansion.
Inflationary Landscape Shows Moderation
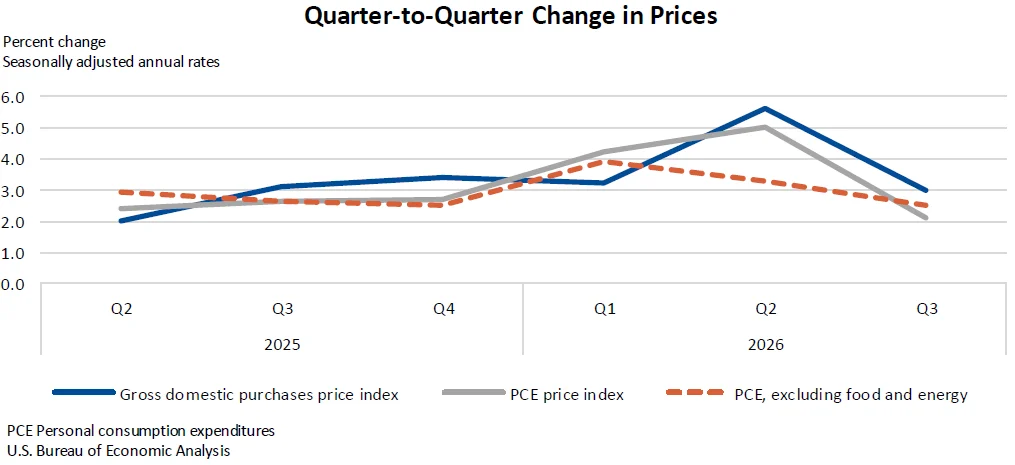
On the inflation front, the price index for gross domestic purchases, a broad measure of price changes for goods and services purchased by consumers, businesses, and governments, registered a 3.0 percent increase in the third quarter. This marks a significant deceleration from the 5.6 percent increase observed in the second quarter, signaling a potential cooling of inflationary pressures.
Further examination of inflation trends reveals a moderation in key price indices. The personal consumption expenditures (PCE) price index, a closely watched inflation gauge by the Federal Reserve, increased by 2.1 percent in the third quarter, down from 5.0 percent in the prior quarter. Even more reassuring, the PCE price index excluding food and energy, often referred to as core PCE inflation, rose by 2.5 percent, a noticeable decrease from the 3.3 percent increase in the second quarter. This moderation in core inflation is particularly significant as it suggests that underlying price pressures, beyond volatile food and energy sectors, are easing.
Background and Context
The third quarter of 2026 unfolds against a backdrop of evolving global economic conditions. Following a period of significant disruption and adaptation, economies worldwide have been striving for stable growth. Factors such as geopolitical developments, shifts in global supply chains, and evolving monetary policy stances by central banks have all played a role in shaping the economic environment.
The BEA’s GDP reports are a critical component of economic policymaking. They provide timely data that informs decisions by the Federal Reserve regarding interest rates, by the U.S. government regarding fiscal stimulus or austerity measures, and by businesses in their strategic planning and investment decisions. The BEA, as the primary source of national economic statistics, plays a pivotal role in providing the data necessary for informed analysis and action.
The BEA’s methodology for calculating GDP involves a complex aggregation of data from various sources, including surveys of businesses, government agencies, and household data. The "advance estimate" is the first snapshot of GDP for a given quarter, derived from the most up-to-date information available. It is subject to revision in subsequent "second" and "third" estimates as more comprehensive data becomes available. The consistency and reliability of these estimates are crucial for maintaining confidence in the economic data.
Timeline and Previous Performance
To understand the significance of the 3.4 percent growth in Q3 2026, it’s useful to look at the preceding quarters. The 2.2 percent growth in Q2 2026 indicated a steady, albeit less robust, expansion. The acceleration to 3.4 percent in Q3 suggests a renewed surge in economic activity, potentially driven by a combination of factors including the unwinding of prior supply chain bottlenecks, increased consumer confidence, and targeted government spending initiatives.
Looking further back, the economic landscape of 2025 likely presented its own set of challenges and opportunities. Understanding the trends from that period provides essential context for the current performance. For instance, if 2025 was characterized by slower growth or inflationary pressures, the Q3 2026 acceleration would represent a more significant positive development. Conversely, if 2025 saw strong growth, the Q3 2026 figures would indicate sustained economic momentum. (Note: Specific data from 2025 is not provided in the original source, but would be crucial for a comprehensive historical analysis.)
Potential Official Responses and Analysis
While the provided text does not include direct quotes from officials, the BEA’s release of this data typically prompts commentary from various stakeholders. Economists at institutions like the Federal Reserve would analyze these figures to assess the need for adjustments in monetary policy. A strong GDP report, especially one with moderating inflation, could reinforce the Fed’s current policy stance or provide a basis for gradual policy adjustments.
The U.S. Department of Commerce, which oversees the BEA, would likely highlight the positive aspects of the report, emphasizing the resilience and strength of the American economy. Congressional committees overseeing economic affairs might use the data to inform legislative debates on fiscal policy and economic growth strategies.
Analysis of the BEA’s data typically focuses on several key aspects:
- Sustainability of Growth: Is the 3.4 percent growth rate sustainable, or is it a temporary surge? The composition of the growth—whether it’s driven by consumption, investment, or government spending—provides clues.
- Inflationary Outlook: The moderation in inflation, particularly core PCE, is a critical positive. Analysts will closely watch if this trend continues, as it impacts purchasing power and the Federal Reserve’s policy decisions.
- Global Economic Interplay: The decrease in exports suggests potential challenges in the global market, which could have implications for U.S. export-oriented industries.
Broader Impact and Implications
The robust GDP growth in the third quarter of 2026 has several significant implications:
- Consumer Confidence and Spending: Sustained economic growth typically correlates with higher consumer confidence, leading to continued robust spending. This can create a virtuous cycle, where increased demand encourages business investment and job creation.
- Business Investment and Job Market: The acceleration in investment suggests that businesses are optimistic about future economic conditions, which can translate into increased hiring and expansion. A strong GDP report often signals a healthy labor market.
- Monetary Policy Considerations: The moderation in inflation provides policymakers at the Federal Reserve with more flexibility. It could support the continuation of current interest rate policies or allow for a more gradual approach to any necessary tightening or easing.
- Fiscal Policy Effectiveness: The contribution of government spending to GDP growth suggests that fiscal policies implemented during this period may be having their intended stimulative effect. This could influence future fiscal policy decisions.
- International Trade Dynamics: The decline in exports warrants attention. A persistent trend of declining exports could indicate a need for policies aimed at improving U.S. competitiveness in global markets or addressing trade imbalances.
Technical Notes and Data Sources
The BEA provides detailed technical notes for its GDP releases, offering transparency into the methodologies and data sources used. These notes are crucial for understanding the nuances of the estimates and for performing in-depth economic analysis. The "key source data and assumptions" table, referenced in the original release, would offer specific details on the data points that drove the Q3 estimate, such as survey results on retail sales, industrial production, housing starts, and government outlays.
The BEA’s Interactive Data Application provides access to historical time series data, allowing users to track trends and perform comparative analyses. The specific tables mentioned in the original release (1.1.1, 1.5.2, 1.4.1, and 1.6.7) offer granular detail on various aspects of GDP, including its components, contributions to change, and price deflators.
The next release, scheduled for November 25, 2026, will provide the "Second Estimate" of GDP for the third quarter of 2026, along with data on Corporate Profits. This second estimate will incorporate more comprehensive data and may lead to revisions of the advance figures. The BEA’s commitment to providing timely and accurate economic data is fundamental to the functioning of modern economies.
In conclusion, the third quarter of 2026 has witnessed a strong acceleration in U.S. economic growth, driven by investment and consumer spending, with a welcome moderation in inflationary pressures. This performance provides a positive outlook, though continued monitoring of international trade dynamics and the sustainability of domestic demand will be crucial in the quarters ahead.