Lana Rhoades
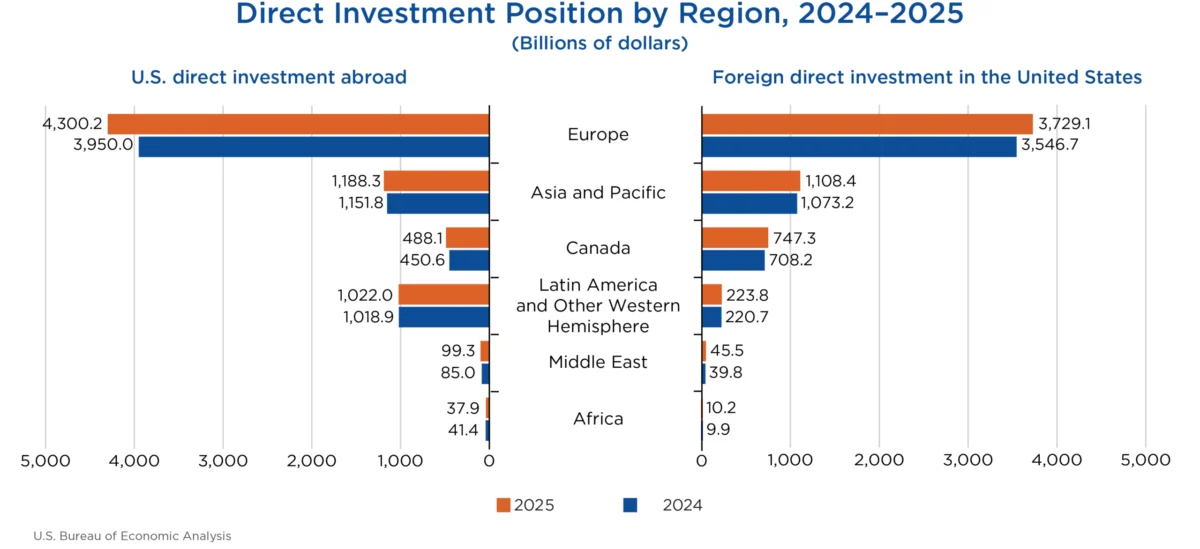
The cumulative level of U.S. direct investment abroad reached $7.14 trillion at the close of 2025, marking a significant increase of $438.1 billion from the previous year. This expansion, detailed in statistics released by the U.S. Bureau of Economic Analysis (BEA), was primarily fueled by a substantial $350.2 billion surge in investments within Europe, with the United Kingdom and Luxembourg emerging as key destinations. Manufacturing, particularly the chemical sector, was the leading industry for this outward investment. Concurrently, foreign direct investment in the United States also experienced a considerable uplift, rising by $266.0 billion to a total of $5.86 trillion. Europe was also the primary driver of this inward investment, contributing an additional $182.4 billion. German and Canadian multinational enterprises were at the forefront of this growth, with substantial increases in their U.S. positions.
Key Highlights of Direct Investment Trends in 2025
The BEA’s comprehensive data for 2025 paints a picture of dynamic international capital flows, reflecting ongoing global economic integration and strategic investment decisions by multinational enterprises. The increase in U.S. direct investment abroad underscores a continued appetite for overseas expansion, driven by a desire for market access, operational efficiencies, and diversification. Conversely, the growth in foreign direct investment into the U.S. signals sustained confidence in the American economy and its robust market opportunities, despite global economic uncertainties.
U.S. Direct Investment Abroad: A Deeper Dive
In 2025, U.S. multinational enterprises (MNEs) demonstrated a widespread global investment strategy, with significant concentrations in key economic hubs. The top five countries receiving U.S. direct investment accounted for over half of the total outflow. The United Kingdom led this list with an impressive $1,114.7 billion in cumulative investment, followed by the Netherlands at $1,044.0 billion, Luxembourg with $645.3 billion, Ireland at $511.9 billion, and Canada with $488.1 billion. This distribution highlights a strategic focus on established markets in Europe and North America, offering access to sophisticated financial systems, skilled labor, and large consumer bases.
By industry, holding companies represented the largest share of U.S. direct investment abroad, comprising 45.8% of the total position in 2025. This indicates a trend towards centralized financial management and strategic asset holding by U.S. corporations in their international operations. Manufacturing affiliates followed, accounting for 15.9% of the investment, with chemical manufacturing being a significant contributor to the overall growth in this sector. Finance and insurance affiliates secured the third position, representing 13.5% of U.S. outward direct investment.
When examining the investment from the perspective of the U.S. parent companies, manufacturing MNEs were the most active, contributing 50.2% of the total outward investment. This was closely followed by MNEs in the finance and insurance sectors, which accounted for 15.8% of the investment. This dual perspective—by industry of the foreign affiliate and by industry of the U.S. parent—provides a more nuanced understanding of the intricate web of global business operations and financial flows.
Income Generated from Overseas Investments
U.S. MNEs generated substantial income from their cumulative investments abroad in 2025, earning $660.1 billion. This represented an 11.1% increase compared to 2024, signaling a healthy return on foreign assets. The growth in income was particularly pronounced in holding companies, which saw an increase of $40.0 billion. However, income from finance and insurance affiliates experienced a slight decline of $6.3 billion compared to the previous year, a trend that warrants further monitoring for potential shifts in global financial market dynamics.
Foreign Direct Investment in the United States: Key Drivers
The influx of foreign capital into the U.S. economy in 2025 was robust, with investments from four countries alone accounting for more than half of the total foreign direct investment position. Japan emerged as the leading investor, with a cumulative position of $776.3 billion. The Netherlands followed closely with $751.8 billion, then Canada at $747.3 billion, and the United Kingdom at $738.3 billion. These figures underscore the continued attractiveness of the U.S. market for major global economies.
A deeper analysis of investment flows based on the ultimate beneficial owner (UBO)—the entity at the highest level of the global ownership chain—reveals a more intricate picture. On a UBO basis, Japan remained the top investing country with $827.1 billion, followed by Canada ($819.8 billion) and Germany ($706.2 billion). The discrepancy between investment reported by the country of the foreign parent and the country of the UBO for nations like the Netherlands and Luxembourg suggests that a significant portion of investment channeled through these financial centers ultimately originates from investors in other countries. This highlights the importance of understanding the true source of capital for a comprehensive view of global investment patterns.
By industry, manufacturing sector in the U.S. attracted the largest share of foreign direct investment, representing 42.8% of the total position. This amounted to $2.51 trillion, with chemical manufacturing alone accounting for a substantial one-third of this amount, or $835.9 billion. This strong showing in manufacturing underscores the sector’s continued importance to the U.S. economy and its appeal to foreign investors seeking to capitalize on production capabilities and market access. Sizable investments were also recorded in finance and insurance ($629.7 billion) and wholesale trade ($534.0 billion), reflecting the diverse opportunities within the U.S. economy.
Income Earned by Foreign Investors in the U.S.
Foreign multinational enterprises earned $310.1 billion in income from their cumulative investments in the United States in 2025. This figure, however, represents a 1.9% decrease from 2024, indicating a slight moderation in returns for foreign investors compared to the previous year. This dip could be attributed to various factors, including evolving market conditions, currency fluctuations, or shifts in the profitability of specific sectors.
Revisions to Historical Data
The BEA also released revised statistics for prior years, incorporating newly available and updated source data. These revisions provide a more accurate historical context for understanding current investment trends. For instance, the U.S. direct investment abroad position for 2023 and 2024, as well as foreign direct investment in the United States for 2022 through 2024, have been updated. These adjustments are crucial for maintaining the integrity and reliability of economic data, enabling policymakers and businesses to make informed decisions based on the most current and accurate information.
Broader Economic Implications and Context
The data released by the BEA provides critical insights into the health and interconnectedness of the global economy. The robust growth in both outward and inward direct investment suggests a generally positive economic outlook, with businesses continuing to expand their operations and seek new markets and investment opportunities.
The substantial investment in Europe by U.S. firms, particularly in the United Kingdom and Luxembourg, can be seen as a strategic move to maintain access to key European markets and leverage established financial infrastructure. The strong performance of chemical manufacturing as a leading sector for U.S. outward investment points to the continued global demand for chemical products and the strategic importance of this industry in supply chains.
On the other side of the ledger, the significant inflow of foreign direct investment into the United States reinforces its position as a premier destination for global capital. The concentration of this investment in the manufacturing sector, especially chemicals, indicates a continued confidence in the U.S. as a manufacturing powerhouse and a reliable base for production. The strong showing of Japan, Canada, and Germany as major investing countries underscores the deep economic ties between these nations and the United States.
The UBO data, revealing the ultimate beneficial ownership of investments, offers a more sophisticated understanding of global capital flows, highlighting the role of intermediary countries and the complex ownership structures of multinational corporations. This information is invaluable for understanding the true beneficiaries of economic activity and the potential influence of different national economies on global markets.
The slight decrease in income earned by foreign investors in the U.S. may warrant attention. While not a drastic decline, it could signal a period of recalibration in the U.S. market or broader global economic adjustments affecting profitability. However, the overall picture remains one of strong engagement and investment.
The BEA’s commitment to refining its disclosure avoidance methods, including the use of coarsening techniques, is a positive development. This approach allows for the publication of more granular data while safeguarding the confidentiality of survey respondents, thereby enhancing the transparency and utility of economic statistics for a wider audience, including researchers, businesses, and the general public.
Looking Ahead
The BEA’s next release on Direct Investment by Country and Industry, scheduled for July 2027, will provide further insights into the evolving landscape of global investment as data for 2026 becomes available. These ongoing statistical releases are essential for tracking economic trends, informing policy decisions, and understanding the dynamic interplay of national economies in an increasingly interconnected world. The patterns observed in 2025 suggest a resilient and dynamic global investment environment, with the United States continuing to play a pivotal role as both a source and a destination for international capital. The ongoing analysis of these trends will be crucial for navigating the complexities of the global economy in the years to come.