Lina Irawan
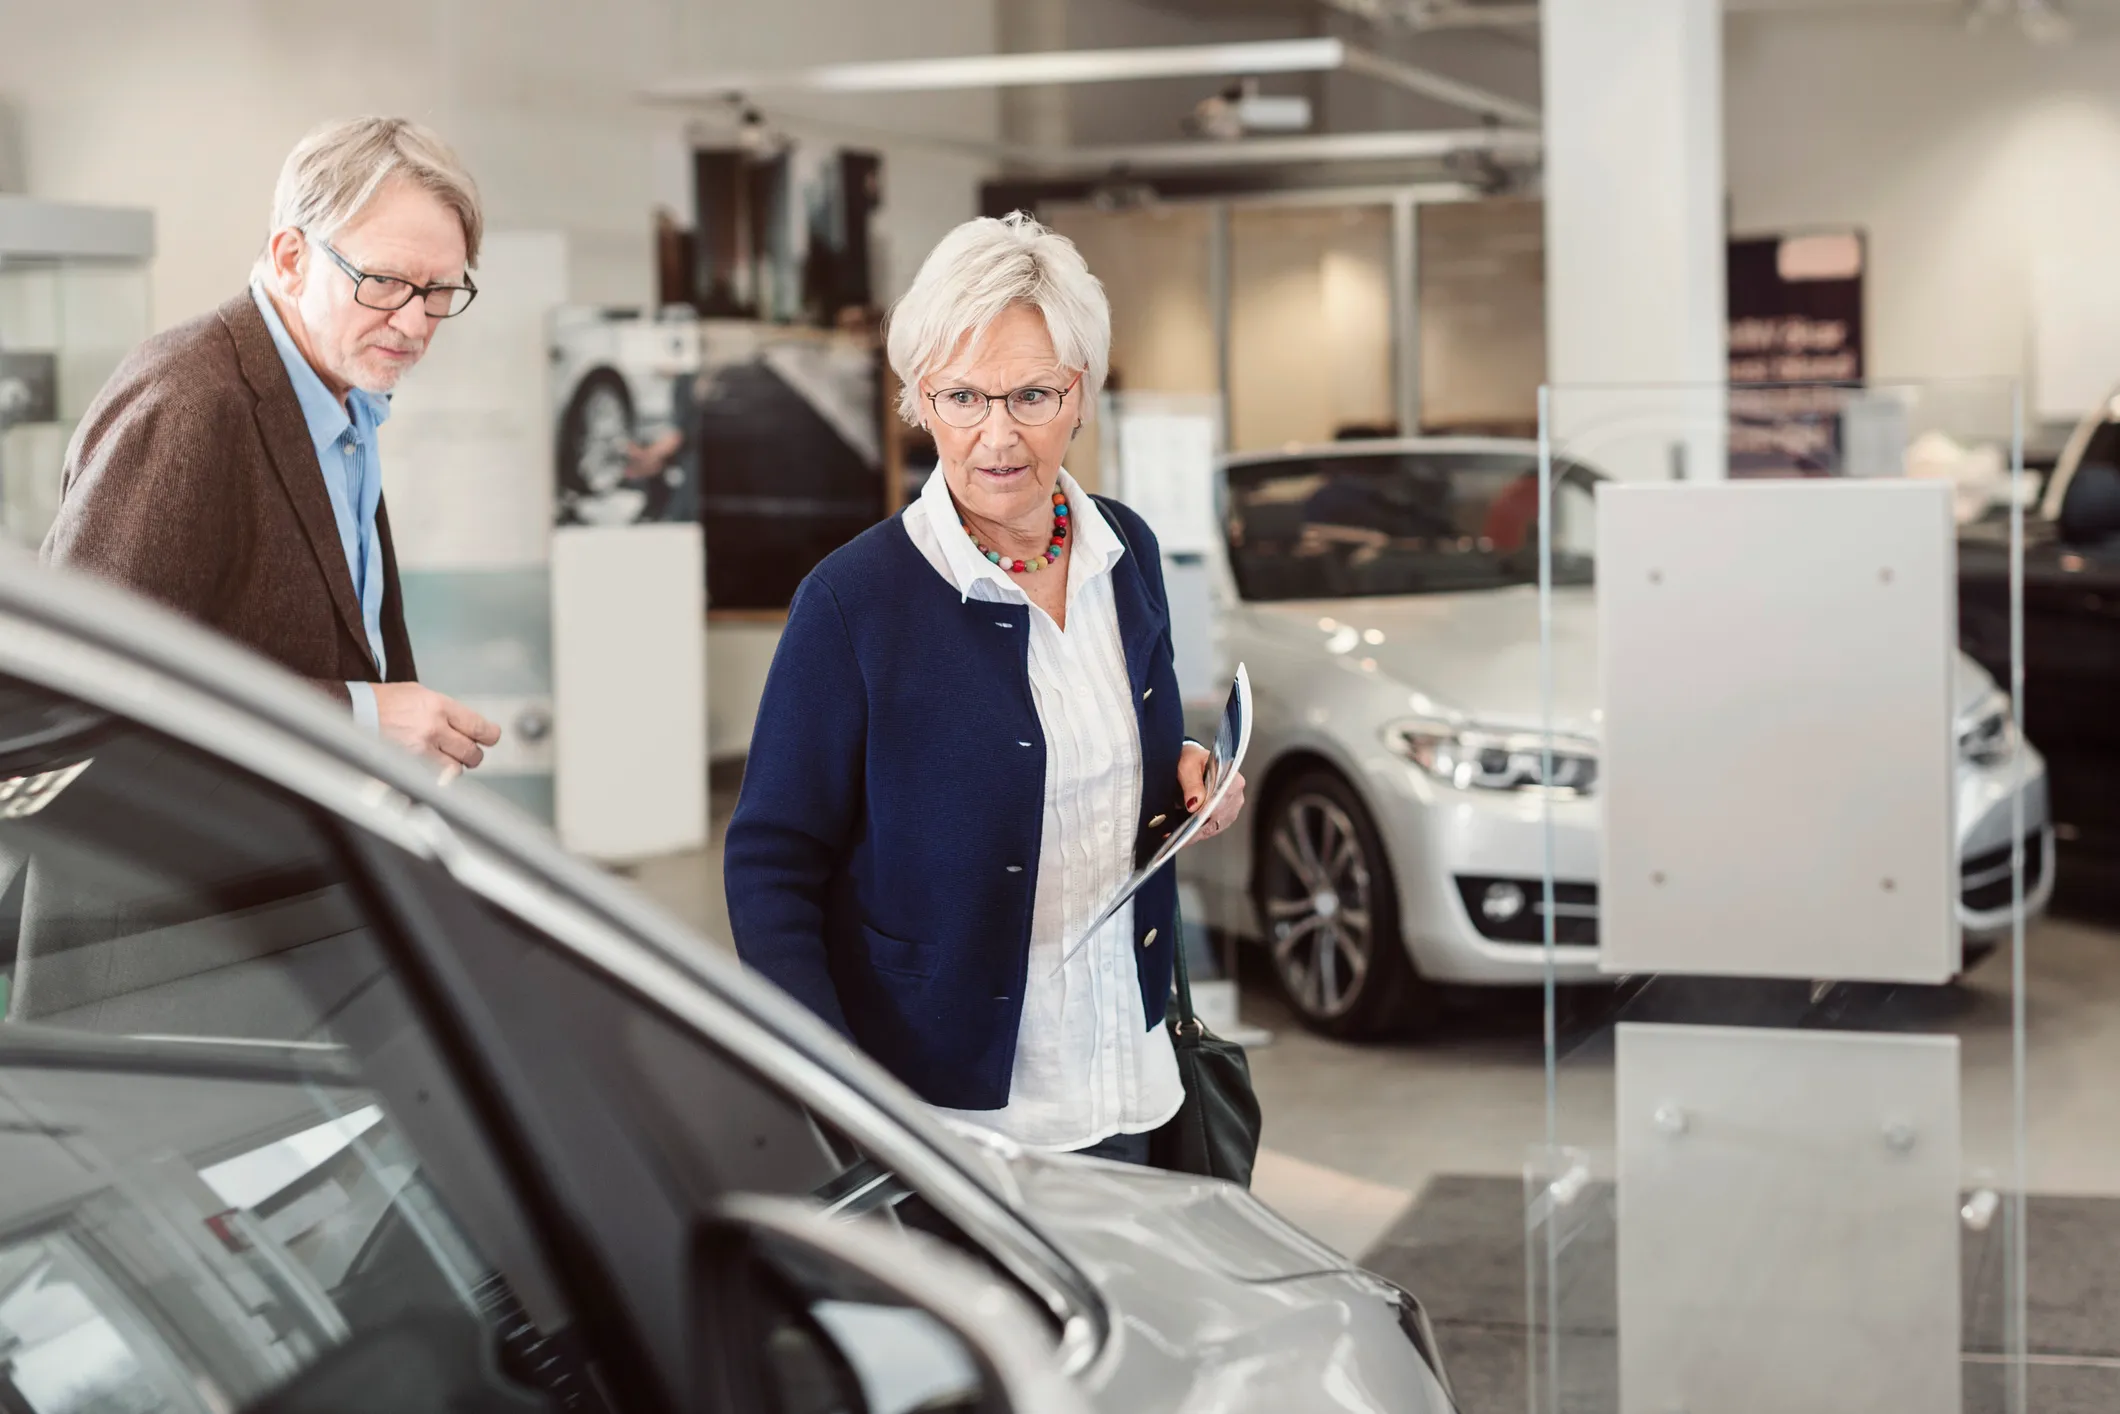
Retiring from full-time employment marks a profound shift in daily life, impacting everything from leisure pursuits to financial planning, and critically, how individuals interact with transportation. For many, the daily commute, once a defining rhythm, evaporates, prompting a fundamental re-evaluation of driving habits and the necessity of previous vehicle ownership patterns. Federal Highway Administration (FHWA) data consistently demonstrates that drivers aged 65 and older typically accrue significantly fewer annual miles compared to their younger counterparts, suggesting that pre-retirement car-buying strategies may no longer align with the realities of life in retirement. This detailed analysis explores the multifaceted considerations for retirees contemplating a new vehicle purchase or reassessing their current automotive footprint, emphasizing financial prudence, evolving lifestyle needs, and safety considerations.
The Shifting Landscape of Retirement Mobility
Human behavior is deeply rooted in habit, and this often extends to major purchasing decisions, including automobiles. A new sport utility vehicle (SUV) serving as a second household car might have been a logical acquisition when both partners were commuting to full-time jobs, requiring independent transportation. However, retirement frequently ushers in a new era of shared experiences and synchronized schedules. Spouses may find themselves undertaking more trips together, drastically reducing the instances where two vehicles are simultaneously needed for separate destinations. This fundamental shift necessitates a departure from long-held assumptions about personal mobility. The once indispensable second car might now sit idle for extended periods, accruing costs without providing proportional utility.
Beyond the reduced need for simultaneous vehicle use, the nature of trips also tends to change. Long-distance work commutes are replaced by local errands, doctor appointments, visits to grandchildren, and perhaps occasional leisure travel. While these activities still require transportation, their frequency, distance, and timing often differ considerably from working life. Understanding this transition is the first crucial step in making informed decisions about car ownership in retirement.
The Escalating Cost of Vehicle Ownership in Detail
Owning a vehicle, particularly a second one, represents a substantial and often underestimated financial commitment that can significantly strain a fixed retirement income. The American Automobile Association (AAA) provides compelling annual data on the total cost of owning and operating a new vehicle. In 2024, the average annual expense was reported to be $12,297, translating to approximately $1,025 per month. This figure encompasses far more than just the initial purchase price or monthly loan payment; it’s a comprehensive calculation factoring in six key components:
- Depreciation: This is often the largest and most overlooked cost. Vehicles begin depreciating the moment they are driven off the lot. Over five years, a new car can lose 40-60% of its value. For a retiree on a fixed income, this loss of capital is particularly impactful as it’s money that cannot be recouped or invested.
- Fuel: While retirees generally drive fewer miles, fuel costs remain a significant variable. Fluctuations in gasoline prices directly impact the monthly budget, and larger, less fuel-efficient vehicles exacerbate this expense.
- Maintenance, Repairs, and Tires: As vehicles age, maintenance costs tend to rise. Even newer vehicles require regular servicing, tire rotations, and eventual replacements. Unexpected repairs can create substantial financial shocks.
- Insurance: Car insurance premiums are influenced by factors such as age, driving record, location, vehicle type, and coverage levels. While older drivers often benefit from years of safe driving, premiums can still be considerable, especially for newer or more expensive models. Moreover, having two separate policies for two vehicles doubles this core expense.
- License, Registration, and Taxes: These annual fees vary by state and jurisdiction but are unavoidable costs associated with vehicle ownership.
- Financing: If a vehicle is purchased with a loan, interest payments add significantly to the total cost over the loan term. Carrying car debt into retirement can be particularly detrimental to financial stability.
When juxtaposed against a typical retirement income, often derived from Social Security, pensions, and investment withdrawals, an average monthly car expense of over $1,000 can consume a disproportionately large share of the budget. These are funds that become unavailable for other critical retirement goals, such as travel, hobbies, healthcare, or bolstering emergency savings. Unlike investments in stocks, bonds, or real estate, which can appreciate over time, a car is a rapidly depreciating asset, making it a poor vehicle for wealth accumulation. This financial burden also competes directly with other non-negotiable expenses like housing, utilities, groceries, and increasingly, healthcare costs, which tend to rise significantly in later life.
Rethinking the Multi-Car Household and Alternative Transportation
The notion of a two-car household, deeply ingrained in American culture for decades, often stems from the demands of dual-income families and complex logistical needs. However, in retirement, this paradigm often loses its rationale. If one or both partners are no longer commuting, the need for independent transportation at separate times diminishes significantly.
This reduced necessity opens the door to exploring alternative transportation solutions that were perhaps impractical or overlooked during working years. Depending on geographic location and urban infrastructure, ride-sharing applications such as Uber or Lyft can serve as convenient, on-demand alternatives for occasional separate trips. The cost savings can be substantial, as users only pay for the service when needed, eliminating the ongoing expenses of insurance, registration, loan interest, and maintenance associated with a second vehicle.
Similarly, public transportation, including buses, subways, and commuter rail systems, offers another cost-effective and often environmentally friendly option. Many municipalities offer discounted fares or free passes for senior citizens, further enhancing their appeal. Beyond the financial benefits, utilizing public transit or ride-sharing can reduce the stress of driving, parking, and vehicle maintenance, allowing retirees to focus on the purpose of their outing rather than the logistics of getting there. For those living in walkable communities or near robust transit networks, these options can provide ample mobility without the burden of private car ownership.
Strategic Car Shopping for the Golden Years
Before embarking on the search for a new vehicle, a comprehensive and honest assessment of current and projected driving habits is paramount. This introspection should involve a detailed review of several key metrics:
- Annual Mileage: How many miles were driven in the past year? Is this number likely to decrease, increase, or remain stable in retirement? Lower mileage drastically reduces the need for frequent upgrades and can justify keeping an older, reliable vehicle longer.
- Night Driving Frequency: As individuals age, night vision can diminish, and glare from oncoming headlights can become more problematic. If night driving becomes less frequent, certain advanced lighting features might be less critical.
- Primary Trip Types: Are most journeys short, local errands, or are long road trips still a frequent occurrence? Short trips are often well-suited for smaller, more fuel-efficient cars, while long trips might prioritize comfort and certain safety features.
- Vehicle Size and Capacity: Is a large SUV or minivan still necessary for hauling equipment, multiple passengers, or extensive cargo? Many retirees find that their need for significant passenger or cargo space diminishes, making a smaller, more maneuverable vehicle more practical and economical.
One of the most impactful decisions is whether to downsize to a single vehicle or to simply keep a current, well-maintained car for longer. Extending the life of an existing vehicle avoids the immediate depreciation hit of a new purchase and eliminates new loan payments. If a new purchase is unavoidable or desired, prioritizing reliability and lower ownership costs over luxury or excessive features becomes crucial.
A reliable, well-maintained used car often presents an excellent value proposition for retirees. Used vehicles have already absorbed the steepest depreciation curve, making them significantly more affordable upfront. Furthermore, insurance premiums and registration fees are typically lower for older models. The market for certified pre-owned vehicles offers an added layer of assurance, often including extended warranties and thorough inspections, bridging the gap between a brand-new car and a higher-risk private sale. Trimming costs in the transportation category, without sacrificing essential mobility or quality of life, can unlock substantial savings that can be redirected towards other fulfilling retirement experiences or crucial financial security.
Safety and Independence: A Balanced Perspective
Maintaining mobility and independence is a cornerstone of a fulfilling retirement, and for many, driving remains a vital component of that autonomy. The Centers for Disease Control and Prevention (CDC) acknowledges the importance of driving for older adults, recognizing its role in social engagement, accessing healthcare, and maintaining daily routines. However, the CDC also highlights that the risk of injury and fatality in vehicle crashes increases with age, particularly after 70. This increased risk is due to a combination of factors, including age-related physical changes (e.g., vision, hearing, reaction time), certain medical conditions, and medication side effects.
Therefore, while driving is important, it’s also crucial to consider how driving habits and vehicle choices can enhance safety. Modern vehicles offer a suite of advanced safety features that can be particularly beneficial for older drivers, such as:
- Automatic Emergency Braking (AEB): Helps prevent or mitigate collisions by automatically applying the brakes if a frontal crash is imminent.
- Blind Spot Monitoring (BSM): Alerts drivers to vehicles in their blind spots, aiding in safer lane changes.
- Lane Departure Warning (LDW) and Lane Keeping Assist (LKA): Help drivers stay in their lane, reducing the risk of unintentional lane drift.
- Rearview Cameras and Cross-Traffic Alert: Greatly assist with parking and backing up, reducing the risk of low-speed collisions.
- Adaptive Cruise Control: Maintains a set distance from the car ahead, reducing driver fatigue on longer journeys.
When selecting a vehicle, prioritizing models with strong safety ratings and these types of driver-assistance technologies can significantly enhance safety and confidence on the road. However, it’s also important to acknowledge that as individuals age, there may come a point where driving less or ceasing to drive altogether becomes the safest option. Proactive planning for this eventuality, by exploring community transport services, family support networks, and accessible ride-sharing options, is a responsible aspect of long-term retirement planning.
Financial Planning and Long-Term Implications
The decision-making process around car ownership in retirement is inextricably linked to broader financial planning. A major purchase or ongoing expense like a car directly impacts the sustainability of retirement savings and the ability to achieve other life goals. For many retirees, the shift from accumulating wealth to drawing down assets requires meticulous budgeting and a keen eye on discretionary spending. Reducing or optimizing transportation costs can free up substantial capital. For instance, saving $500 a month by reducing car expenses translates to $6,000 annually, which over 10-15 years, if invested, could grow into a significant sum.
This liberated capital could be reallocated to cover rising healthcare costs, fund travel experiences, contribute to a legacy, or simply provide a larger financial cushion against unexpected expenses. Financial advisors frequently emphasize the importance of minimizing fixed costs in retirement to provide greater flexibility and reduce stress. A car payment, insurance premium, and ongoing maintenance represent fixed costs that, unlike entertainment or dining out, are difficult to cut on short notice.
Industry and Advocacy Perspectives
The automotive industry has recognized the growing demographic of older drivers, leading to an increased focus on vehicle design that caters to their specific needs. Features such as easier ingress/egress, larger displays, simpler controls, and enhanced visibility are becoming more common. Manufacturers are also heavily investing in advanced driver-assistance systems (ADAS) that benefit drivers of all ages, but particularly those whose reflexes or sensory perceptions may be slightly diminished.
Organizations like AARP, dedicated to empowering older Americans, consistently advocate for policies and resources that promote safe mobility and independence. Their recommendations often include regular vision and hearing checks, driver refresher courses tailored for seniors, and community initiatives that support alternative transportation. They also encourage open discussions within families about driving capabilities as individuals age, promoting proactive planning over reactive crises.
Urban planners, meanwhile, are increasingly considering the needs of an aging population in city design. Investments in public transportation infrastructure, walkable communities, and senior-friendly transit services are gaining traction as populations age globally. This integrated approach acknowledges that individual car ownership, while important, is not the sole solution for senior mobility.
Future Outlook on Senior Mobility
Looking ahead, the landscape of senior mobility is poised for further evolution. Autonomous vehicle technology, though still in its nascent stages for widespread public use, holds the potential to revolutionize transportation for older adults, offering a future where mobility is no longer dependent on personal driving ability. Simultaneously, the growth of micro-mobility options (e-bikes, scooters) in urban areas, and more sophisticated on-demand transit services, will likely expand choices for retirees.
The core message, however, remains timeless: retirement is a period of significant change, demanding a thoughtful re-evaluation of long-standing habits and financial commitments. By proactively assessing driving needs, understanding the true costs of vehicle ownership, and exploring available alternatives, retirees can make informed decisions that enhance both their financial security and their quality of life, ensuring continued independence and peace of mind in their golden years.