Layla Zulfa
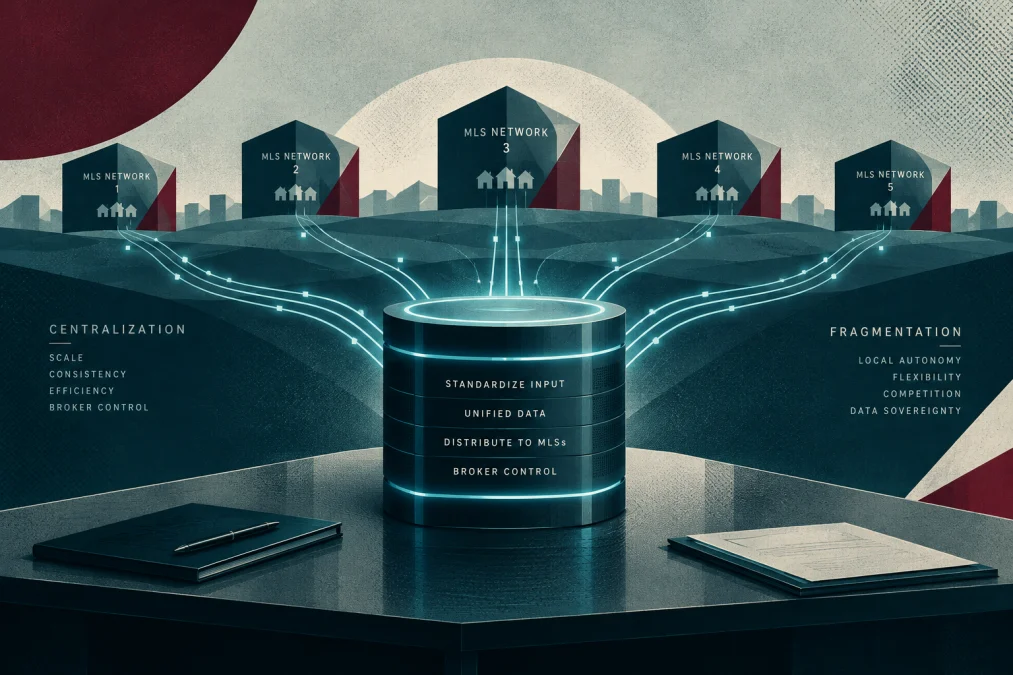
In a move poised to reshape the landscape of real estate data sharing, four of the nation’s largest brokerage firms—Keller Williams, HomeServices of America, eXp Realty’s parent company AGNT, and Real RE/MAX Group—collectively representing approximately 300,000 agents, have jointly unveiled Open Real Estate (ORE). This ambitious initiative introduces a shared listing database designed to operate independently of the Multiple Listing Services (MLS). While initial discussions have rightly focused on the practicalities of execution, a more profound question emerges for those managing MLS systems: why did these dominant brokers feel compelled to forge this new path?
The core proposition of Open Real Estate is straightforward: agents will input a listing only once, within one business day of securing a listing agreement. Crucially, sellers will retain the power to designate who can view their property information. This includes a "participant view" accessible exclusively to agents within ORE’s member brokerages, and a broader "market view" that can be disseminated to MLSs, national real estate portals, appraisers, and other industry stakeholders. While ORE’s proposed marketing options may initially appear limited, the underlying principle of brokers maintaining ownership of their listings and sharing in the value generated by their data is a foundational element that resonates deeply within the industry.
However, Open Real Estate is not without its hurdles. To date, no MLS has officially committed to integrating ORE’s listings into their existing platforms. While MARIS in St. Louis has indicated support for the concept, acknowledging "room for improvement" within the current MLS framework, widespread adoption by these critical data aggregators remains uncertain. The selection of a technology vendor for ORE is not anticipated until early 2027, and history offers cautionary tales of broker-led, single-point-of-entry initiatives that have faltered. Nevertheless, the ultimate success or failure of ORE as a standalone platform may be secondary to the potent message it sends: brokers are actively seeking superior alternatives to the status quo.
This sentiment was echoed by an MLS executive in a recent article published by RIS Media, who observed, "I don’t think that these companies would be doing what they’re doing if they were happy MLS customers. They want a better way than what they are presented with right now." This candid admission suggests a fundamental disconnect between the evolving needs of brokers and the current offerings of many MLS organizations. When the technological layers are peeled back, ORE’s public statements often read less like a product announcement and more like a comprehensive wish list of functionalities that brokers believe their existing MLSs should already be providing.
The MLS Conundrum: Why Hasn’t This Been Built Already?
The reluctance of MLSs to proactively address these broker demands is not necessarily a reflection of a lack of ambition. In recent years, MLSs have indeed embarked on significant investments and strategic initiatives to leverage broker data more effectively. Stellar MLS, for instance, launched its own consumer-facing search site in September, aiming to provide a direct and trusted connection to potential buyers. NorthstarMLS and MARIS have jointly invested in REcore Solutions, an MLS-owned data company designed to enhance data management and distribution. Furthermore, a significant number of MLSs, exceeding 40, now license their data through REdistribute, while more than 20 have integrated with SourceRE’s new connector, a platform built to incorporate MLS data into artificial intelligence tools.
Despite these advancements, the rights afforded to brokers regarding the use and display of their own listing data have not kept pace with these technological developments. The rules governing how brokers can utilize and present MLS listing information are typically dictated by IDX (Internet Data Exchange) policies and individual licensing agreements. These agreements are negotiated separately with each MLS, resulting in a complex web of approximately 400 distinct arrangements across the country. Consequently, when an MLS strikes deals to place broker listings in front of cutting-edge AI companies, while the brokers’ own rights to leverage that same data remain stagnant, it naturally prompts them to seek alternative venues for their listings. Open Real Estate represents one such alternative.
This issue extends to the critical area of seller marketing. ORE’s offering of two distinct distribution choices for sellers is a step forward, but the industry arguably requires a more nuanced and expansive array of options. MLS rules should evolve to acknowledge that a property can be marketed publicly without necessitating distribution to every conceivable platform. Sellers should be empowered with meaningful control over the timing and channels through which their listings are presented to the market.
The overarching concern is that brokers should not be forced to construct an entirely new data network simply to achieve these fundamental improvements. MLS executives possess the authority to draft, and their respective boards have the power to approve, more progressive rules. These rules could facilitate a streamlined, single point of entry for listing data, a service that some MLSs already offer through collaborations with technology partners. Such revised regulations could provide sellers with genuine marketing choices while simultaneously safeguarding the interests of buyers. Crucially, they would enable the entities that supply the industry’s most valuable asset – listing data – to utilize it more effectively in serving their clients, irrespective of where those clients choose to search for properties.
Navigating the Future of Real Estate Data
The imperative for these rule changes lies in striking a delicate balance. While it is essential to uphold the principles of cooperation, accuracy, and fair access that have long been the bedrock of the MLS system, the continued value of the MLS should not come at the expense of innovation and broker empowerment. The current landscape suggests that brokers are not advocating for the abandonment of the MLS’s core functions. Instead, they are urging MLSs to adapt and evolve in tandem with the businesses that are the primary source of their listing inventory.
The emergence of Open Real Estate serves as a clear and potent signal that a significant segment of the brokerage community is no longer willing to wait for this evolution to occur organically. Their proactive creation of ORE underscores a deep-seated desire for greater control, flexibility, and a more equitable distribution of value derived from the data they generate. The implications of this move are far-reaching, potentially influencing future data-sharing agreements, the competitive dynamics between MLSs and independent broker initiatives, and the very definition of how real estate information is managed and disseminated in the digital age.
The genesis of ORE can be traced back to a growing frustration among large brokerages regarding the limitations imposed by existing MLS rules and data-sharing agreements. For years, brokers have operated under a system where their listing data, generated through significant investment in marketing and agent time, is pooled into MLS databases. While MLSs provide essential services, the ability of brokers to leverage this data for their own distinct marketing strategies and to retain a greater share of the economic benefits has been increasingly constrained.
A Timeline of Discontent and Innovation
The roots of this tension can be observed in a series of industry trends and developments over the past decade. The rise of national real estate portals like Zillow and Realtor.com, while beneficial for broad listing exposure, also highlighted the brokers’ diminishing direct connection with consumers and the data generated by those interactions. Simultaneously, technological advancements in artificial intelligence and data analytics began to present new opportunities for leveraging real estate data, opportunities that brokers felt were not being fully realized or equitably shared through the traditional MLS structure.
The announcement of Open Real Estate on Monday represents a culmination of these concerns. By banding together, Keller Williams, HomeServices of America, AGNT (parent company of eXp Realty), and Real RE/MAX Group are demonstrating a unified front, signaling that their collective leverage is substantial. This collaboration is not merely about creating a new database; it is about asserting a new paradigm for data ownership and control within the residential real estate sector.
Analyzing the Broader Impact
The establishment of Open Real Estate carries significant implications for multiple stakeholders:
- Brokers: ORE promises greater autonomy over their listing data, allowing for more tailored marketing strategies and potentially new revenue streams from data monetization. It addresses the long-standing desire for a "one-to-many" data entry system that reduces redundant work and ensures data consistency.
- MLS Organizations: The launch of ORE serves as a direct challenge to the traditional gatekeeping role of MLSs. It compels MLSs to re-evaluate their value proposition, enhance their services, and potentially revise their rules to be more accommodating of broker needs and data ownership aspirations. Failure to adapt could lead to further fragmentation of the data ecosystem.
- Consumers: The ultimate impact on consumers remains to be seen. If ORE leads to more efficient data distribution and better marketing tools for sellers, it could indirectly benefit buyers through increased listing availability and enhanced property information. However, a fragmented data landscape could also present challenges in accessing comprehensive market information.
- Technology Providers: The move by major brokerages to create their own data infrastructure may shift the focus of innovation. While some technology companies have partnered with MLSs, ORE’s existence could spur the development of solutions tailored to this new, broker-centric data environment.
The success of ORE will hinge on its ability to attract widespread adoption, not only from agents within its member brokerages but also from other industry participants. The critical juncture will be its integration with or acceptance by the broader MLS network. If ORE can demonstrate a clear benefit in terms of data quality, efficiency, and seller control, it could indeed force a significant recalibration of the real estate data ecosystem, pushing MLSs towards greater collaboration and a more broker-centric approach to data management. The question is no longer if brokers want change, but rather how the existing structures will respond to this powerful collective demand.