Lina Irawan
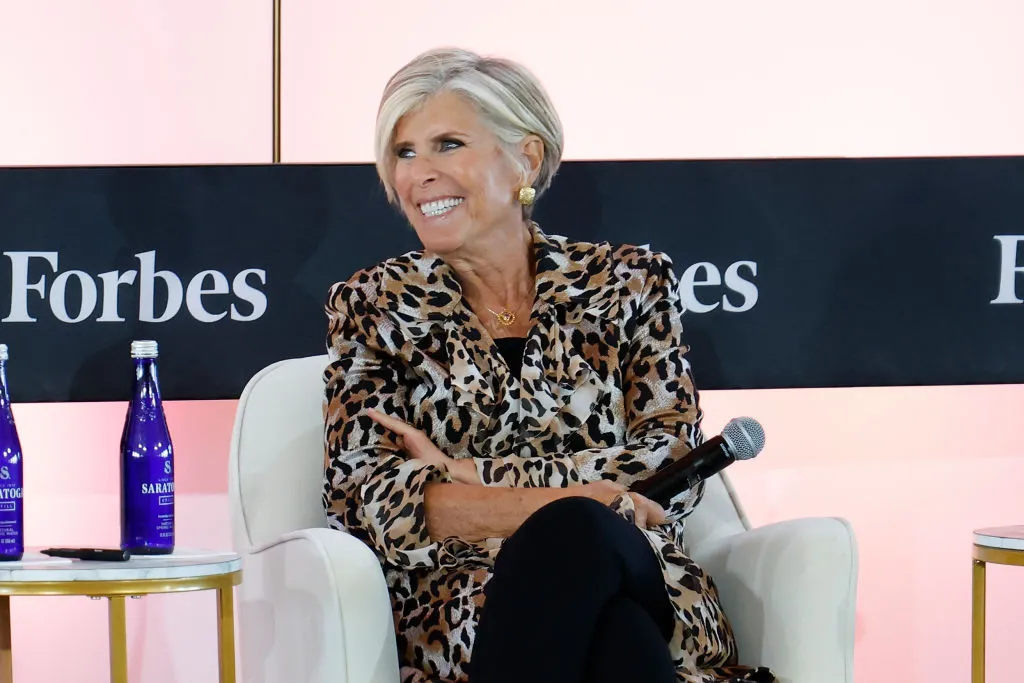
For decades, personal finance luminary Suze Orman has served as a prominent voice in guiding individuals toward greater financial security. Her counsel, often delivered with characteristic conviction, emphasizes debt reduction, judicious spending, and an acute awareness of the psychological dimensions of money management. Orman’s extensive body of work, encompassing television shows, books, and public appearances, has influenced millions, offering a foundational framework for improving financial well-being. While her principles often resonate broadly, like any comprehensive financial philosophy, certain tenets invite deeper consideration and adaptation to individual circumstances. This analysis delves into four of Orman’s key financial directives, distinguishing between those that represent universally accepted wisdom and those that warrant a more personalized assessment in today’s dynamic economic landscape.
The Bedrock Principles: Universally Endorsed Financial Wisdom
Two of Orman’s most steadfast recommendations align squarely with the consensus among certified financial planners and economic experts. These principles are foundational to financial resilience and long-term prosperity, offering safeguards against unforeseen challenges and pathways to achieving significant financial goals.
1. Establishing a Robust Emergency Fund
Suze Orman is an ardent advocate for the establishment and maintenance of a well-funded emergency savings account. This principle is not merely a suggestion but a critical component of financial stability, designed to shield individuals from the disruptive impact of unexpected financial shocks. An emergency fund acts as a crucial buffer, providing liquidity during periods of job loss, significant medical expenses, unforeseen home repairs, or other unanticipated life events that could otherwise derail financial progress.
The rationale behind this advice is rooted in economic realities. Data from the Federal Reserve consistently indicates that a significant portion of American households would struggle to cover an unexpected expense of $400 without borrowing or selling assets. This vulnerability underscores the imperative of dedicated emergency savings. Financial advisors typically recommend accumulating enough liquid assets to cover three to six months of essential living expenses. However, this benchmark is not rigid; individual circumstances necessitate tailoring. Those with unpredictable income streams, such as freelancers or commission-based workers, or individuals with higher potential for unexpected outlays, such as families with young children or pet owners, may benefit from saving six to twelve months’ worth of expenses.
The liquidity of these funds is paramount. Orman, like most experts, suggests housing emergency savings in a readily accessible, yet interest-bearing account, such as a high-yield savings account. These accounts offer better returns than traditional checking accounts while ensuring funds can be accessed swiftly when needed, without penalties or market volatility associated with investment vehicles. The psychological benefit of an emergency fund is equally significant, providing peace of mind and reducing financial stress, allowing individuals to navigate crises from a position of strength rather than desperation. The consistent message from financial institutions, non-profits like the National Foundation for Credit Counseling (NFCC), and academic research highlights the emergency fund as the cornerstone of personal financial planning, mitigating the risk of debt accumulation during periods of adversity.
2. Cultivating and Maintaining a Strong Credit Profile
Another cornerstone of Orman’s advice centers on the paramount importance of a robust credit score. A high credit score is far more than just a number; it is a powerful financial asset that influences an individual’s access to credit, the terms of borrowing, and even non-lending aspects of life, such as insurance premiums and rental applications. Orman consistently highlights that prioritizing credit health translates directly into tangible financial benefits, such as lower interest rates on mortgages, auto loans, and personal loans, thereby reducing the total cost of borrowing over time.
The FICO score, the most widely used credit scoring model, ranges from 300 to 850. Scores between 670 and 739 are generally considered "good," while 740 to 799 are "very good," and 800 to 850 are "excellent." The difference between a good and an excellent score can translate into tens of thousands of dollars saved over the life of a major loan, such as a 30-year mortgage. For instance, a borrower with an excellent credit score might secure an interest rate significantly lower than one with a good score, resulting in lower monthly payments and substantial savings over the loan term.
Strategies for enhancing and preserving credit health are well-documented and universally recommended:
- Payment History (35% of FICO score): Consistently paying bills on time is the single most important factor. Late payments can severely damage scores.
- Credit Utilization (30% of FICO score): Keeping credit card balances low relative to credit limits is crucial. Experts advise maintaining utilization below 30%, ideally even lower.
- Length of Credit History (15% of FICO score): A longer history of responsible credit use is beneficial.
- Types of Credit (10% of FICO score): A mix of credit types, such as installment loans (mortgages, auto loans) and revolving credit (credit cards), can positively impact scores.
- New Credit (10% of FICO score): Opening too many new accounts in a short period can be seen as risky.
Regularly checking credit reports for errors, which can unfairly depress scores, is also a vital practice. Services like AnnualCreditReport.com provide free access to reports from the three major bureaus (Equifax, Experian, TransUnion). Orman’s emphasis on credit scores aligns with the guidance from consumer protection agencies like the Consumer Financial Protection Bureau (CFPB), which stress the foundational role of credit in achieving financial milestones and participating fully in the modern economy.
The Nuanced Debates: Re-evaluating Conventional Wisdom in Modern Finance
While Orman’s advice on emergency funds and credit scores is widely embraced, two other prominent rules she champions often spark more debate among financial professionals and consumers. These principles, while rooted in sound intentions, may not offer the optimal path for every individual, highlighting the truly "personal" nature of personal finance.
1. The Stance Against Leasing an Automobile
Suze Orman has famously and unequivocally stated her opposition to leasing automobiles, often characterizing it as a "waste of money" because the lessee never gains ownership of the vehicle. This perspective is understandable from a traditional wealth-building standpoint, where asset accumulation and avoiding "renting" something that depreciates are core tenets. A house is typically the largest purchase for most individuals, and a car often follows as the second most significant expenditure. Orman’s argument hinges on the idea that monthly payments without an equity stake prevent wealth accumulation.
Historically, the arguments against leasing are compelling:
- No Ownership: Lease payments build no equity; at the end of the term, the car is returned.
- Long-Term Cost: Over an extended period, continuously leasing new vehicles can often be more expensive than purchasing and holding a car for many years.
- Mileage and Wear Limits: Leases come with strict mileage caps and wear-and-tear clauses, potentially leading to expensive penalties if exceeded.
- Early Termination Fees: Exiting a lease before its term can incur substantial costs.
However, the financial landscape and consumer preferences are not black and white, and for certain individuals, leasing can present a viable, even advantageous, option. The advantages of leasing include:
- Lower Monthly Payments: Lease payments are typically lower than loan payments for the same vehicle, as they only cover the depreciation during the lease term, plus interest and fees. This can allow access to a higher-priced or newer model.
- New Car Every Few Years: For those who prioritize driving a new vehicle with the latest technology, safety features, and under warranty, leasing offers a convenient cycle of vehicle upgrades every two to four years.
- Predictable Expenses: Most maintenance is covered under warranty during a lease term, reducing unexpected repair costs.
- Tax Benefits for Businesses: Business owners can often deduct lease payments as a business expense.
- Avoidance of Resale Hassle: At the end of a lease, the car is simply returned, avoiding the complexities and potential financial loss associated with selling a used vehicle.
Recent data from sources like Experian indicate that auto loan payments have been steadily rising, making the lower monthly outlay of a lease appealing to a segment of the market. Furthermore, the rapid technological advancements in automotive manufacturing, particularly with electric vehicles (EVs), mean that new models often offer significant improvements in efficiency, range, and features. For consumers who value these upgrades and wish to avoid the depreciation risk associated with owning rapidly evolving technology, leasing offers flexibility. The decision to lease or buy ultimately depends on an individual’s financial goals, driving habits, budget, and preference for new technology versus long-term asset ownership. A comprehensive cost analysis, considering total cost of ownership over a typical period (e.g., 6-8 years, which might involve two leases or one purchase), is crucial for an informed decision.
2. The Emphasis on Debit Over Credit Card Usage
Orman’s strong preference for debit card usage over credit cards stems from a deep concern about the pervasive and destructive nature of credit card debt. She frequently advises individuals to keep credit card usage to an absolute minimum, perhaps only for one or two recurring bills set to autopay, to avoid falling into the trap of high-interest debt. This advice is grounded in a valid apprehension: unchecked credit card spending can quickly lead to accumulating balances that carry exorbitant interest rates, often exceeding 20% APR, making repayment a formidable challenge and diverting significant funds away from savings or investment.
According to the Federal Reserve, outstanding credit card debt in the U.S. has frequently surpassed $1 trillion, highlighting the scale of the problem Orman seeks to address. For individuals who struggle with impulse control, lack a consistent income, or are prone to overspending, adhering strictly to debit card use can indeed be a protective measure against financial distress.
However, for financially disciplined individuals who can consistently pay their credit card balances in full each month, exclusively relying on debit cards means foregoing several significant advantages:
- Credit Building: Responsible credit card use is one of the most effective ways to build and maintain a strong credit score. As discussed, a good credit score is essential for accessing favorable terms on mortgages, auto loans, and other forms of credit. Debit card transactions do not contribute to credit history.
- Rewards Programs: Many credit cards offer lucrative rewards programs, including cashback, travel points, and discounts on specific categories like groceries or gas. By strategically using these cards for everyday expenses and paying the balance in full, consumers can effectively receive a discount on their spending, potentially saving hundreds or even thousands of dollars annually.
- Enhanced Fraud Protection: Credit cards generally offer superior fraud protection compared to debit cards. Under the Fair Credit Billing Act, liability for unauthorized credit card charges is limited to $50, and many card issuers offer zero-liability policies. With debit cards, fraudulent activity can directly drain funds from a checking account, potentially causing immediate financial hardship and requiring more effort to recover funds, although banks do offer some protections.
- Dispute Resolution: Credit card companies often provide robust dispute resolution services, acting as an intermediary between the consumer and a merchant in case of faulty goods or services.
- Convenience and Emergency Access: Credit cards offer a convenient payment method globally and can serve as an emergency fund backup (though not a primary one) in dire situations, particularly when traveling.
For those with the discipline to manage their spending and pay balances in full monthly, credit cards are powerful tools for maximizing financial efficiency, building credit, and enjoying enhanced security. The key distinction lies in how credit cards are used: as a convenient payment tool to be paid off, rather than a means to extend one’s budget beyond their income. Financial literacy organizations like the National Endowment for Financial Education (NEFE) often advocate for a balanced approach, educating consumers on responsible credit card use rather than outright avoidance.
The Broader Landscape of Personal Finance Advice
Suze Orman’s enduring presence in the personal finance arena underscores the public’s continuous quest for guidance in managing their money. Her advice, much like that of other financial gurus, serves as a powerful starting point for many individuals embarking on their financial journeys. However, the very term "personal finance" emphasizes that optimal strategies are inherently individualized. An individual’s income level, debt load, career stability, family structure, risk tolerance, and long-term aspirations all significantly influence the applicability of any given financial rule.
The economic environment also plays a crucial role. Advice tailored to periods of high inflation, low interest rates, or economic recession may require different nuances. For instance, while saving is always prudent, the optimal allocation of those savings between liquid emergency funds, debt reduction, and investments might shift depending on prevailing interest rates and market conditions. The rise of digital banking, fintech innovations, and evolving investment opportunities also means that financial advice must continually adapt to remain relevant and effective.
Ultimately, the most effective approach to personal finance involves a blend of foundational principles, critical thinking, and a willingness to tailor widely accepted advice to one’s unique circumstances. While Suze Orman’s unwavering commitment to financial prudence has undoubtedly empowered countless individuals, a discerning approach allows one to leverage the strengths of her guidance while intelligently navigating the areas where personalization yields greater benefits. Engaging with diverse financial perspectives, seeking professional advice when needed, and committing to continuous financial education are paramount for achieving lasting financial well-being in an ever-changing world.