Lana Rhoades
The California Department of Tax and Fee Administration (CDTFA) is currently overseeing a significant transition in the state’s fiscal policy, marking a pivotal moment for businesses operating within the world’s fifth-largest economy. As of late 2024, the state has finalized plans to expand its sales tax base to include a variety of digital products and Software as a Service (SaaS) subscriptions, with a hard implementation date set for January 1, 2027. This move aligns California with a growing number of U.S. states that have already modernized their tax codes to reflect the digital economy, and it necessitates a rigorous approach to compliance for quarterly filers who must navigate the state’s notoriously complex district-based tax system.
The Shift Toward Digital Product Taxation
Historically, California has been one of the few major tech hubs to exempt most "intangible" digital goods from sales and use tax, provided no tangible personal property was transferred. However, legislative shifts and updated regulatory interpretations by the CDTFA have paved the way for the 2027 mandate. Under the new guidelines, qualifying digital products—including streamed media, cloud-based software subscriptions, and remotely accessed data—will be subject to the same state and district tax rates as physical goods.
This change is expected to generate significant revenue for the state, which relies on sales and use tax as its second-largest source of general fund income, trailing only personal income tax. Economists estimate that the inclusion of SaaS and digital products could add hundreds of millions of dollars to the state’s annual tax receipts, helping to buffer against volatility in other revenue streams. For businesses, however, the change introduces a new layer of administrative burden, particularly for remote sellers who may have economic nexus in California without a physical presence.
Chronology of California’s Tax Modernization
The path to the 2027 digital tax implementation has been defined by several key milestones:
- June 2018: The U.S. Supreme Court’s decision in South Dakota v. Wayfair, Inc. fundamentally altered the landscape, allowing states to require remote sellers to collect sales tax based on economic activity rather than physical presence.
- April 2019: California implemented its economic nexus threshold, requiring any retailer with more than $500,000 in annual sales into the state to register and collect tax.
- October 2019: The Marketplace Facilitator Act went into effect, shifting the burden of tax collection from individual small sellers to large platforms like Amazon and eBay.
- 2024–2025: Public comment periods and CDTFA workshops focused on the definition of "qualifying digital products" to ensure the 2027 rollout addresses the complexities of modern software delivery models.
- January 1, 2027: The scheduled commencement of taxation on SaaS and digital products.
Fundamental Mechanics of California Filing
For businesses currently preparing quarterly returns, the process remains rooted in the CDTFA Online Services portal. The state operates on a destination-based tax system, meaning the tax rate is determined by the location where the customer receives the product or service. With over 200 local jurisdictions and hundreds of district-level add-on taxes, the margin for error is substantial.
Filers are required to report total gross sales and then apply a series of deductions to arrive at the taxable amount. Common deductions include nontaxable labor, sales for resale (supported by valid resale certificates), and sales made through marketplace facilitators who have already collected and remitted the tax. A critical component of the quarterly return is the reporting of "purchases subject to use tax." This applies to items a business purchased for its own use from out-of-state vendors who did not collect California tax.
Technical Breakdown: Schedules A, B, and C
The complexity of a California return is often found in its supplemental schedules, which allocate tax revenue to specific local governments.
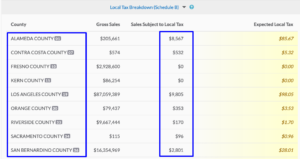
- Schedule A (District Tax Breakdown): This is the most frequently used schedule. It requires sellers to report taxable transactions by specific district. Because district rates can change quarterly, filers must ensure they are using the correct rate for the specific date of the transaction.
- Schedule B (County Tax Breakdown): This schedule is used for allocating county-wide pools. It is typically required for businesses that do not have a physical location in a specific county but are making sales into it, or for those whose sales are not subject to a specific district tax but still contribute to the county’s 1.25% local tax portion.
- Schedule C (Detailed Allocation by Location): Required for businesses with multiple registered brick-and-mortar locations within California. This ensures that the 1% local tax portion is distributed to the specific municipality where the business operates.
Data-Driven Compliance and Common Pitfalls
Recent audit data from the CDTFA suggests that the most common errors in sales tax filing involve improper documentation of exempt sales and mathematical discrepancies caused by rounding. California requires tax to be calculated on each transaction, but the return is filed based on aggregate totals. If a business rounds at the transaction level but the CDTFA system expects rounding at the aggregate level, "rounding variances" occur. While small variances (usually under $10) are generally ignored, larger discrepancies can trigger a manual review.
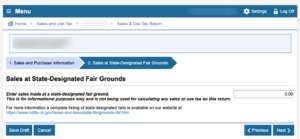
Another significant area of risk involves "Fairground Sales." California law requires specific reporting for sales made on state-designated fairgrounds. While many online-only businesses report $0 for this line, failing to properly account for it if a business participates in trade shows or pop-up events can lead to penalties.
Industry Reactions and Economic Implications
The business community has expressed a mix of resignation and concern regarding the 2027 digital tax shift. Industry groups representing SaaS providers have argued that the administrative cost of tracking district-level taxes for millions of micro-transactions could outweigh the tax revenue for smaller startups. Conversely, state officials maintain that the current exemption for digital goods creates an unfair advantage for software companies over traditional retailers of physical media, such as booksellers or hardware stores.
Tax experts suggest that the "Sales of Fixtures and Equipment" line on the return is often overlooked during business acquisitions or closures. When a business sells its assets, those sales are generally taxable unless an exemption applies, and the failure to report these one-time large transactions is a frequent target for CDTFA auditors.
The Role of Automation in Modern Tax Strategy
Given the impending 2027 changes and the existing complexity of district taxes, many enterprises are moving away from manual filing. Automation platforms like TaxJar have become essential for managing the sheer volume of data. These systems integrate with e-commerce platforms to categorize products, validate addresses, and apply the correct district rates in real-time.
For businesses required to make "Quarterly Prepayments"—a requirement for those with higher tax liabilities—automation is particularly beneficial. California requires certain filers to pay their estimated tax in two installments during the first two months of the quarter, with the final balance due with the quarterly return. Missing these prepayment deadlines results in a 10% penalty, a significant cost that automation helps avoid by tracking deadlines and liabilities automatically.
Strategic Outlook for 2025-2027
As California prepares for the January 1, 2027, deadline, businesses are advised to conduct a nexus study and a product taxability review. The transition of SaaS from nontaxable to taxable will require updates to billing systems and customer contracts. Furthermore, companies must ensure their record-keeping is robust; California’s statute of limitations for audits is typically three years, but it can extend to eight years for unregistered businesses.
The evolution of California’s tax code reflects a broader global trend toward taxing the consumption of digital services. While the 2027 mandate represents a significant change, it also offers a degree of certainty for businesses that have long navigated a "gray area" regarding digital product taxability. By focusing on accurate district allocation, maintaining rigorous documentation for deductions, and leveraging modern compliance technology, businesses can mitigate the risks associated with this major regulatory shift.
In summary, the CDTFA’s move toward digital taxation is a clear signal that the state is committed to a tax base that mirrors the modern economy. For the quarterly filer, the focus must remain on precision and preparation. The complexity of California’s tax system is not expected to decrease; rather, the scope of what is taxable is simply expanding to meet the digital age.