Julia Chirkova
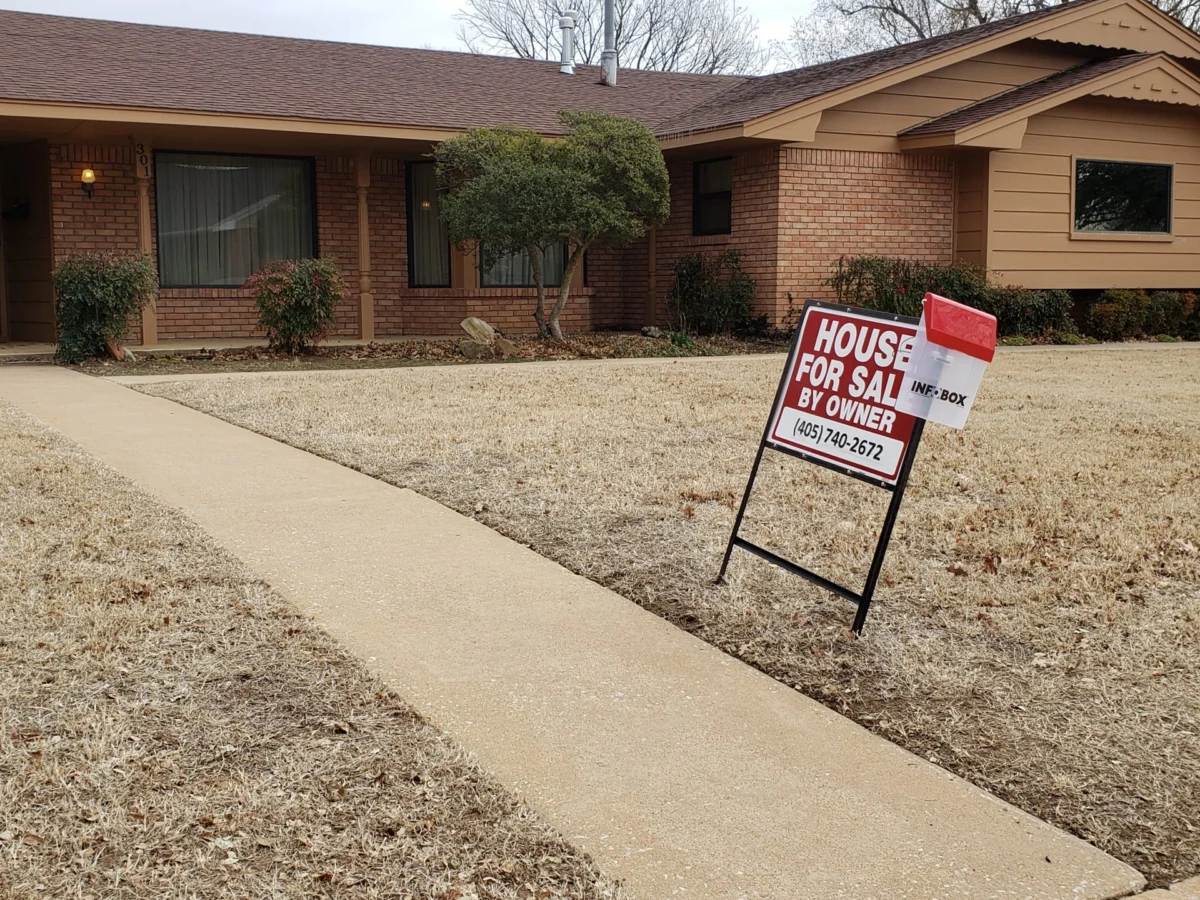
The American housing market experienced a significant downturn in October, with sales of previously owned homes falling to their lowest point in 16 years. This sharp decline, marked by a 5.5% decrease to an annualized rate of 3.75 million contract closings, according to data released by the National Association of Realtors (NAR) on Thursday, underscores the profound impact of elevated mortgage rates and persistent inflation on prospective homebuyers. The economic headwinds have created a challenging environment, deterring many from making one of the most significant financial decisions of their lives.
The breadth of the slowdown is evident across major regions. Sales in the West plummeted to their slowest pace since NAR began tracking data in 1999. Similarly, the South and Midwest witnessed sales hitting their lowest levels in more than a decade, signaling a nationwide cooling of the housing sector. This widespread contraction paints a grim picture for a market that has, in recent years, been characterized by robust demand and rapidly escalating prices. The current economic climate, dominated by mortgage rates consistently exceeding 7% and a stubborn inflation rate across various sectors, has left potential buyers grappling with affordability challenges and economic uncertainty.
However, amidst the prevailing gloom, a potential silver lining is emerging: the possibility of improved affordability in the future. The pullback in demand, while detrimental in the short term, is beginning to manifest in a more balanced market. Recent data from online real estate marketplace Redfin revealed that 36% of homes sold in October experienced at least one price reduction. This figure represents the highest share of price-chopped listings in Redfin’s recorded data, indicating that sellers are increasingly willing to negotiate to attract buyers.
Further supporting the notion of a shifting market dynamic, Bloomberg Intelligence analyst Drew Reading noted in a November 9th report that the active inventory of existing homes on the market continued to grow last month, even as the pace of new listings weakened. This trend, where existing homes linger on the market longer and new construction may be slowing, also suggests that price relief could be on the horizon.
Lawrence Yun, NAR’s Chief Economist, acknowledged the current challenges but expressed optimism about future prospects. "Based on the current underwhelming home sales pace at a time of consistent job growth, there could be sizable pent-up demand if mortgage rates decline," Yun stated in a press release accompanying the NAR report. This sentiment suggests that a significant portion of the population remains interested in homeownership, awaiting more favorable economic conditions.
Supply Builds Amidst Declining Demand
The NAR report provided detailed insights into the evolving supply-demand equation. The supply of homes available on the resale market in October increased by 4.6% compared to the previous year, reaching 1.59 million units. This marks the highest inventory level for an October since 2019. At the current sales pace, this inventory represents 5.1 months’ worth of supply, the most significant buffer observed since late 2015. A rising supply, coupled with declining sales, typically puts downward pressure on prices, a phenomenon that appears to be gradually taking hold.
Despite the overall slowdown, the median sales price of previously owned homes saw a modest annual increase of 0.4% to $416,700. While this represents an increase, it is the smallest year-over-year gain recorded since February, further indicating a deceleration in price appreciation. This trend is a stark contrast to the rapid price hikes witnessed in the preceding years, which were fueled by historically low mortgage rates and a surge in buyer demand.
The affordability crisis in housing has been a significant economic and political issue, notably contributing to the Democratic party’s successes in the midterm elections. NAR’s housing affordability index, a crucial metric that gauges a typical family’s ability to qualify for a mortgage on a median-priced home, has deteriorated significantly. The index has fallen to its lowest level since mid-2025, highlighting the increasing financial strain on potential homeowners. This decline in affordability has effectively priced many out of the market, forcing them to postpone or abandon their homeownership aspirations.
The weakness in the housing market extends beyond single-family homes. Sales of existing condominiums also experienced a substantial decline, reaching their lowest point in records dating back to 1999. This broad-based contraction across different housing types suggests a systemic issue rather than a localized problem.
Economic Context and Broader Implications
The dismal housing figures are part of a larger economic narrative characterized by persistent inflation and rising interest rates. The Federal Reserve has been actively raising interest rates in an effort to curb inflation, a strategy that directly impacts mortgage rates. As borrowing costs increase, the affordability of homes diminishes, leading to a slowdown in sales.
In a related economic development, separate data released on Thursday indicated that applications for unemployment benefits rose to 200,000 last week. While this represents an increase, the figure remains close to historically low levels, suggesting that the labor market, while showing some signs of cooling, has not yet experienced a significant deterioration. This resilient labor market could provide a floor for the housing market, preventing a more drastic collapse, but it has not been enough to offset the negative impact of high borrowing costs.
The current situation in the housing market has several significant implications. For potential buyers, it presents a difficult decision: whether to enter a market with high borrowing costs and potentially falling prices, or to wait for more favorable conditions. For sellers, it means adjusting expectations and potentially accepting lower offers. For the broader economy, a prolonged housing downturn can have ripple effects, impacting construction, related industries, and consumer spending.
The historical context of this housing slowdown is important. Following the 2008 financial crisis, the housing market experienced a prolonged period of recovery and growth, often buoyed by exceptionally low interest rates. The recent surge in rates marks a significant departure from this trend, forcing a recalibration of market expectations and affordability metrics. The current market conditions are a stark reminder of the cyclical nature of the housing market and the significant influence of monetary policy on real estate transactions.
Looking ahead, the trajectory of the housing market will largely depend on the path of inflation and the Federal Reserve’s monetary policy decisions. Should inflation begin to abate more consistently, the Fed may pause or even reverse its rate hikes, leading to a potential decline in mortgage rates. Such a development could re-ignite buyer interest and stimulate sales. Conversely, if inflation remains stubbornly high, interest rates may continue to rise, further dampening demand and prolonging the housing market’s slump.
The interplay between supply, demand, interest rates, and inflation will continue to shape the housing landscape. While the current data points to a challenging period, the underlying desire for homeownership, as suggested by NAR’s Chief Economist, remains a potent factor that could drive a future recovery once economic conditions become more conducive. The coming months will be crucial in determining whether the current downturn is a temporary pause or the beginning of a more extended period of adjustment for the U.S. housing market.
The challenges faced by the housing market also have broader implications for economic policy. Policymakers will need to navigate the delicate balance between controlling inflation and supporting economic growth. The housing sector, a significant component of the U.S. economy, will be a key indicator to watch as these policies unfold. The current environment underscores the interconnectedness of various economic factors and the complex challenges faced by consumers, businesses, and policymakers alike in the current economic climate.