Lana Rhoades
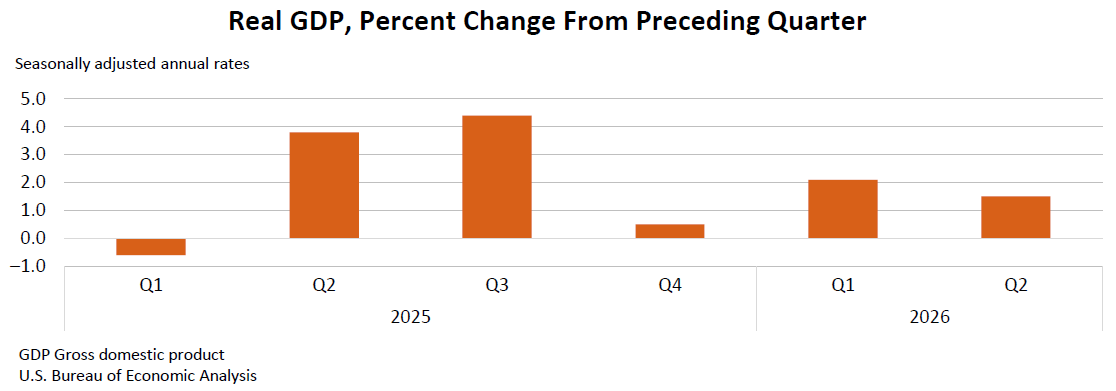
The United States economy, as measured by real gross domestic product (GDP), expanded at an annualized rate of 1.5 percent in the second quarter of 2026, according to the second estimate released by the U.S. Bureau of Economic Analysis (BEA). This represents a deceleration from the 2.1 percent growth recorded in the first quarter of the year. The latest figures, covering the period from April through June, offer a more refined picture of economic activity, incorporating updated data that nudged the initial advance estimate slightly.
Key Drivers of Economic Growth in Q2 2026
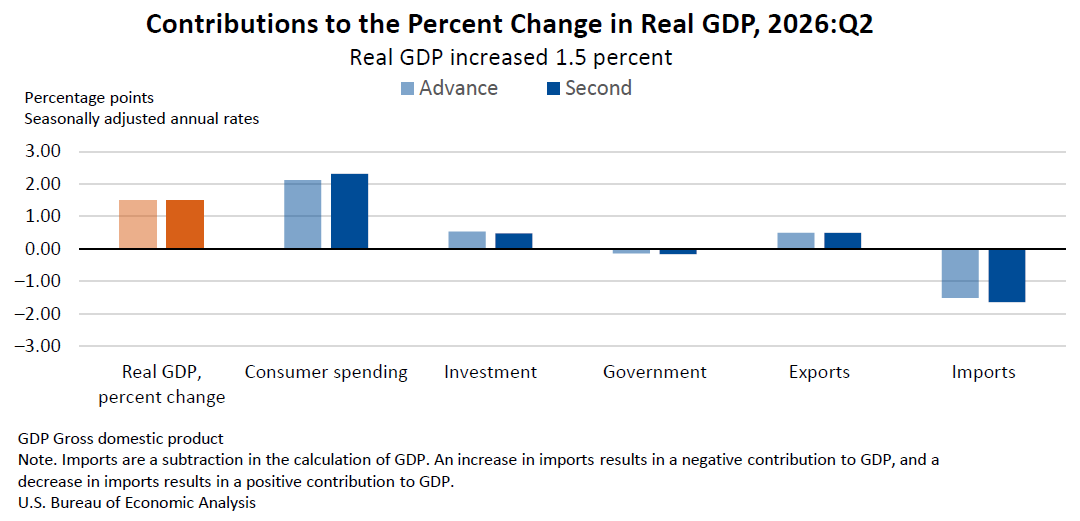
The modest expansion in real GDP during the second quarter was propelled by several key components, albeit with a mixed performance across different sectors. Consumer spending, a perennial engine of the U.S. economy, continued its upward trajectory, providing a significant boost. Exports also contributed positively, indicating sustained demand for American goods and services from international markets. Investment, a crucial indicator of business confidence and future economic potential, also showed an increase, although its growth rate was less pronounced than in the preceding quarter.
However, the overall growth was partially tempered by a contraction in government spending. This decline in public expenditure offset some of the gains made by the private sector. Furthermore, imports, which are subtracted in the calculation of GDP, experienced a notable increase. A rise in imports suggests that domestic demand is being met, in part, by goods and services produced abroad, thereby reducing the net contribution of trade to GDP.
The BEA’s second estimate confirmed the initial projection of 1.5 percent growth for real GDP. While an upward revision to consumer spending was a positive development, it was counterbalanced by an upward revision to imports. This interplay of revised figures underscores the dynamic nature of economic data and the continuous refinement process undertaken by statistical agencies.
Deceleration Explained: A Shift in Economic Momentum
The slowdown in real GDP growth from the first quarter to the second quarter can be attributed to a confluence of factors. A significant downturn in government spending marked a notable shift in economic momentum. This contraction in public investment and expenditure, whether at the federal, state, or local level, exerted a drag on overall economic activity.
Additionally, both investment and exports experienced a deceleration in their growth rates compared to the first quarter. While still positive contributors, their slowing pace indicated a less vigorous expansion in these areas. Conversely, consumer spending exhibited an acceleration, demonstrating resilience and a growing propensity among households to spend. This acceleration in consumption played a vital role in mitigating the broader slowdown. The increasing volume of imports in the second quarter, outpacing the first quarter, further influenced the GDP calculation, highlighting a growing reliance on foreign-produced goods.
Private Sector Strength: Real Final Sales to Private Domestic Purchasers
A closer examination of domestic demand reveals a more robust picture within the private sector. Real final sales to private domestic purchasers, a measure that aggregates consumer spending and gross private fixed investment, surged by 4.2 percent in the second quarter. This figure, revised upward by 0.3 percentage point from the previous estimate, signals strong underlying demand from households and businesses for goods and services produced domestically. This robust growth in private domestic demand suggests a healthy consumer and business environment, even as broader GDP growth moderated.
Inflationary Pressures Remain a Key Concern
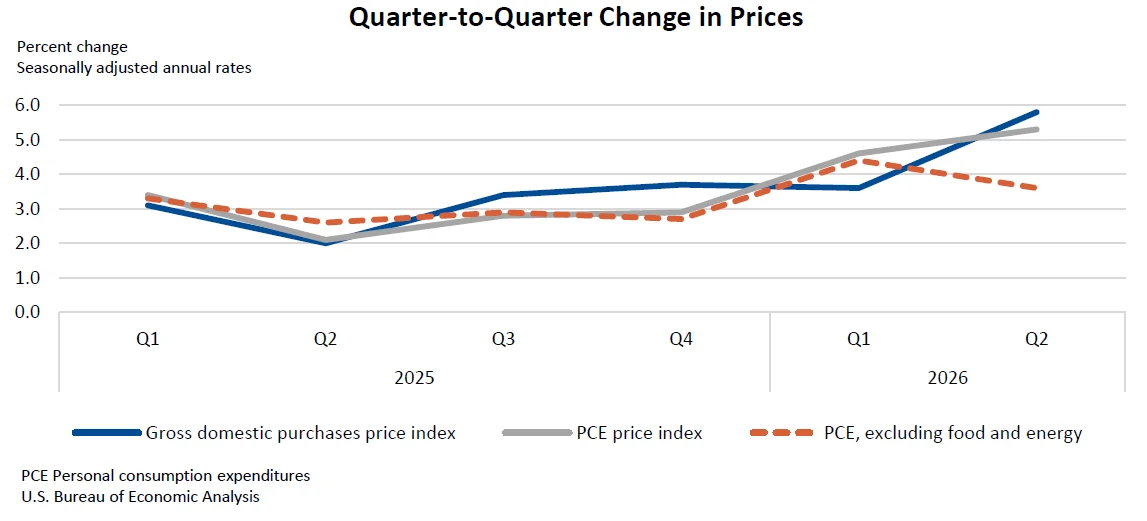
While economic growth figures provide a snapshot of output, the inflationary environment remains a critical concern for policymakers and consumers alike. The price index for gross domestic purchases, a broad measure of inflation for goods and services purchased by domestic entities, rose by 5.8 percent in the second quarter. This represents an upward revision of 0.1 percentage point from the advance estimate.
The personal consumption expenditures (PCE) price index, a key inflation gauge closely watched by the Federal Reserve, increased by 5.3 percent. This was also revised upward by 0.2 percentage point. Even when excluding the more volatile food and energy components, the core PCE price index saw an increase of 3.6 percent, revised upward by 0.2 percentage point. These figures indicate that inflationary pressures, while potentially showing some signs of moderation in certain categories, remain elevated and a significant factor in the current economic landscape. The sustained rise in the cost of goods and services impacts household purchasing power and business operating costs, influencing investment and consumption decisions.
Gross Domestic Income (GDI) and the Average Measure
In addition to GDP, the BEA also tracks Gross Domestic Income (GDI), which measures the income side of economic activity. In the second quarter, real GDI increased by 2.2 percent, a notable acceleration from the 1.2 percent growth seen in the first quarter. This divergence between GDP and GDI can occur due to statistical discrepancies and differences in the timing and valuation of transactions.
To provide a more comprehensive view, the BEA often presents the average of real GDP and real GDI. This average, which is considered a more stable indicator of economic activity, increased by 1.8 percent in the second quarter, up from 1.7 percent in the first quarter. The increase in this averaged measure suggests a more consistent, albeit still moderating, pace of economic expansion when accounting for both the production and income sides of the economy.
Corporate Profits Show Strong Gains
Corporate profits from current production, adjusted for inventory valuation and capital consumption, demonstrated robust growth in the second quarter. Profits increased by $400.9 billion, a significant uptick from the $74.4 billion increase recorded in the first quarter. This substantial rise in corporate profitability indicates that many businesses were able to navigate the economic environment effectively, potentially passing on costs to consumers or benefiting from strong demand for their products and services. These gains in profits can have implications for business investment, hiring decisions, and shareholder returns.
A Look at the Data: Key Revisions and Comparisons
The second estimate of real GDP growth at 1.5 percent annual rate was consistent with the advance estimate. However, underlying components saw revisions. An upward revision to consumer spending contributed positively, reflecting stronger-than-anticipated household expenditures. Conversely, an upward revision to imports indicated a greater influx of foreign goods and services than initially assessed.
Compared to the first quarter’s 2.1 percent growth, the deceleration in the second quarter was primarily driven by a significant downturn in government spending. Furthermore, both investment and exports saw their growth rates slow down. Consumer spending, however, accelerated, providing a crucial counterbalance to these moderating forces. The increased pace of import growth in the second quarter compared to the first also played a role in the overall GDP calculation.
Upcoming Annual Updates and Data Releases
The U.S. Bureau of Economic Analysis has announced significant changes to its annual update schedule for national and regional economic accounts. For the first time, the 2026 annual updates for national, industry, and regional data will be released concurrently on September 30, 2026. This integrated approach aims to enhance the efficiency and coherence of BEA’s statistical production. The national economic accounts update will encompass GDP, GDI, GDP by industry, and monthly personal income and outlays, among other statistics. Simultaneously, the regional economic accounts update will include GDP by state and county, along with personal income data for these geographic levels. This coordinated release is part of BEA’s ongoing efforts to improve the timeliness and comprehensiveness of its economic data.
The next release of GDP data is scheduled for September 30, 2026, at 8:30 a.m. Eastern Daylight Time. This release will include the third estimate for the second quarter of 2026 GDP, along with data on industries, corporate profits, state GDP, and state personal income for the same quarter. Additionally, state personal consumption expenditures for 2025 will be published.
Technical Notes and Data Interpretation
The technical notes accompanying the BEA release provide further detail on the sources of revisions to real GDP. The second estimate of real GDP growth at an annual rate of 1.5 percent (which translates to 0.4 percent on a quarterly rate) was a slight downward revision of less than 0.1 percentage point. The upward revision to consumer spending was a key factor, but it was offset by an upward revision to imports.
For analysts and the public seeking to delve deeper into the data, the BEA provides access to a comprehensive suite of interactive data tables. These tables allow users to explore historical time series and detailed breakdowns of GDP and related economic indicators. Key tables include:
- Table 1.1.1. Percent Change From Preceding Period in Real Gross Domestic Product: This table provides the headline GDP growth rates.
- Table 1.5.2. Contributions to Percent Change in Real Gross Domestic Product, Expanded Detail: This table breaks down the specific components that contributed to GDP growth or contraction.
- Table 1.4.1. Percent Change From Preceding Period in Real Gross Domestic Product, Real Gross Domestic Purchases, and Real Final Sales to Domestic Purchasers: This table offers a comparison of different measures of domestic economic activity.
- Table 1.6.7. Percent Change From Preceding Period in Prices for Gross Domestic Purchases: This table details price changes across a broad range of goods and services.
- Table 1.7.1. Percent Change From Preceding Period in Real GDP, Real Gross National Product, and Real Net National Product: This table provides broader measures of national economic output.
- Table 6.16D. Corporate Profits by Industry: This table offers a detailed view of corporate profitability across various economic sectors.
It is important to note that with each subsequent release, the data presented in these tables is superseded. The original data featured in a specific release can be accessed through the BEA’s Data Archive, ensuring historical accuracy and transparency.
Broader Economic Context and Implications
The second quarter GDP figures paint a picture of an economy that is expanding, but at a more measured pace than previously observed. The resilience of consumer spending is a positive sign, suggesting that household finances remain relatively stable, supporting demand. However, the deceleration in investment and exports, coupled with the decline in government spending, warrants attention. These trends could signal a shift in the economic landscape, potentially influenced by factors such as global economic uncertainties, domestic policy adjustments, or evolving business investment strategies.
The persistent inflationary pressures, as indicated by the rising price indices, continue to pose a challenge. Policymakers, including the Federal Reserve, will likely remain focused on balancing the need to foster economic growth with the imperative to control inflation. The interplay between robust corporate profits and the broader economic environment will also be closely monitored, as it can influence future capital expenditures and hiring decisions.
The BEA’s commitment to enhancing its data production and dissemination, as evidenced by the upcoming synchronized annual updates, underscores the importance of timely and accurate economic statistics for informed decision-making by businesses, policymakers, and the public. As the economy navigates through the remainder of 2026, the BEA’s ongoing releases will be crucial for understanding the evolving economic trajectory and its potential implications.