Lana Rhoades
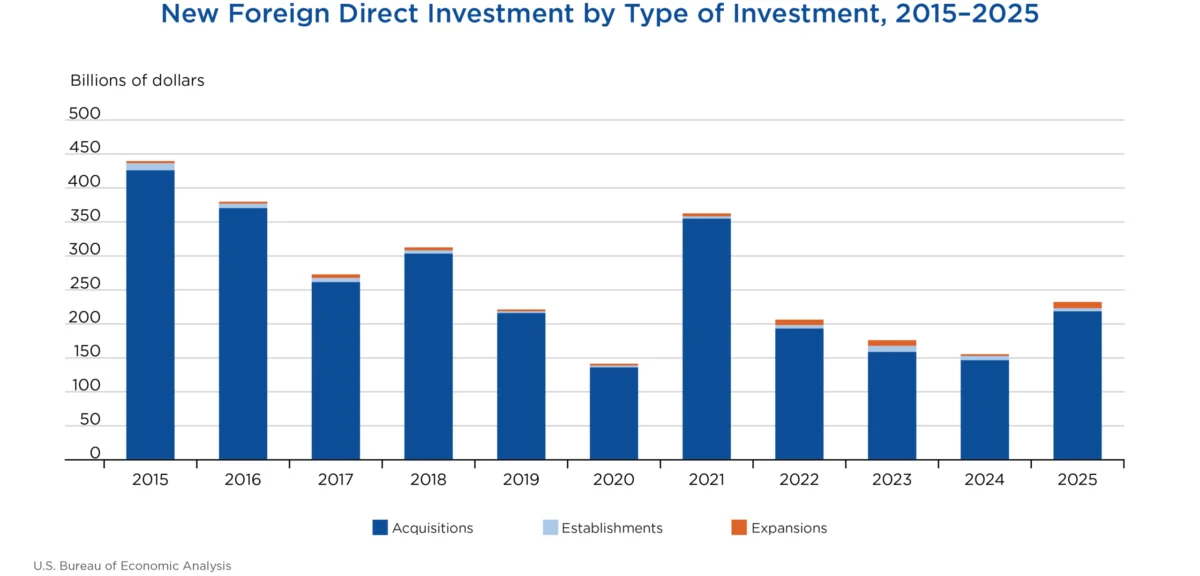
Expenditures by foreign direct investors to acquire, establish, or expand U.S. businesses reached a robust $232.2 billion in 2025, marking a significant 49.5 percent increase from the previous year’s $155.3 billion. Preliminary statistics released today by the U.S. Bureau of Economic Analysis (BEA) indicate a dynamic period for international investment in the American economy, with the acquisition of existing U.S. businesses remaining the predominant avenue for foreign capital deployment. This surge in investment not only highlights the continued attractiveness of the U.S. market but also signals a renewed confidence among global investors in the nation’s economic prospects.
The substantial growth in foreign direct investment (FDI) underscores a broader trend of increasing cross-border capital flows, a phenomenon influenced by evolving global economic conditions, strategic market access, and the pursuit of technological advancements. In 2025, the landscape of FDI in the United States was characterized by a clear preference for strategic acquisitions, which accounted for the lion’s share of the investment. Specifically, acquisitions of existing U.S. businesses totaled $218.4 billion. In contrast, the establishment of new U.S. businesses, often referred to as greenfield investments, attracted $4.6 billion, while expansions of existing foreign-owned businesses accounted for $9.2 billion. These figures, when aggregated, paint a picture of foreign entities actively integrating into the U.S. economic fabric through both outright ownership and strategic growth initiatives.
Beyond the immediate first-year expenditures, the BEA also reported planned total expenditures, which encompass both initial outlays and commitments for future investment. These projections reached $284.5 billion, suggesting that the momentum generated in 2025 is expected to continue, with significant further investments anticipated in the coming years. This forward-looking data provides a crucial insight into the long-term strategies of foreign investors and their sustained commitment to the U.S. market.
The impact of this influx of capital is also evident in employment figures. In 2025, newly acquired, established, or expanded foreign-owned businesses in the United States provided employment for 213,100 individuals. This figure represents a direct contribution to job creation and economic vitality across various sectors and geographic regions within the United States. The breakdown of employment further illustrates the scale of these investments, with current employment at acquired enterprises reaching 211,700, and total planned employment, including new establishments and expansions, projected to reach 232,400 once fully operational.
Shifting Investment Landscape: Key Sectors and Origins
The distribution of foreign direct investment across industries reveals strategic priorities among international investors. Publishing industries emerged as the largest recipient of new direct investment in 2025, attracting $50.7 billion. This sector’s strong performance indicates a global appetite for U.S. media, content, and information services. Following closely, chemicals manufacturing garnered $45.4 billion, highlighting the continued importance of this foundational industry in the U.S. economy. Plastics and rubber products manufacturing also saw substantial investment, with $19.0 billion directed towards this sector. Collectively, the manufacturing sector accounted for a significant portion of total expenditures, representing $121.8 billion, or 52.5 percent of all new FDI. This dominance of manufacturing underscores its enduring role as a key driver of economic activity and innovation in the United States.
On the global stage, Japan led the pack of investing countries, with its investors committing $50.5 billion to U.S. businesses. Germany followed with $26.7 billion, and Canada contributed $23.5 billion. Regionally, Europe was the most significant source of new investment, contributing $116.6 billion, or 50.2 percent of all new FDI in 2025. The Asia and Pacific region was the second-largest investing bloc, with $71.9 billion in expenditures. These figures reflect established economic ties and strategic trade relationships between the United States and these key global partners.
The geographical distribution of FDI within the United States underscores the varied appeal of different states to foreign investors. California emerged as the top destination, attracting $59.7 billion in first-year investment expenditures. Its robust technology sector, large consumer market, and skilled workforce likely contributed to its leading position. Texas followed with $21.5 billion, a testament to its diverse economy, particularly in energy and technology. Pennsylvania secured the third spot with $20.9 billion, reflecting investment across a range of industries.
Greenfield Investments: Laying New Foundations
While acquisitions dominated overall FDI, greenfield investments—expenditures dedicated to establishing new U.S. businesses or expanding existing foreign-owned ones—also played a notable role. In 2025, greenfield expenditures totaled $13.8 billion. By industry, transportation and warehousing received the largest share of greenfield investment at $3.6 billion, signaling growth in logistics and supply chain infrastructure. Computers and electronics products manufacturing attracted $2.0 billion, while chemicals manufacturing received $1.8 billion.
Regionally, investors from the Asia and Pacific bloc led greenfield expenditures with $8.3 billion. Australia was a prominent contributor within this region, investing $3.0 billion, followed by South Korea with $2.2 billion and Japan with $1.7 billion. At the state level, Louisiana saw significant greenfield investment, totaling $3.0 billion, likely driven by its strategic port infrastructure and industrial base. Arizona attracted $2.7 billion, and Texas received $1.9 billion in greenfield investments. Planned total expenditures for greenfield investments initiated in 2025 were projected at $66.1 billion, indicating substantial future development and job creation in these areas.
Employment Dynamics and Sectoral Contributions
The impact of FDI on employment is multifaceted, encompassing current jobs in acquired companies and planned jobs in new ventures and expansions. In 2025, current employment within acquired enterprises stood at 211,700. When considering the planned employment for newly established businesses and expansions, the total projected workforce reaches 232,400. This sustained job creation is a critical economic benefit of FDI.
Analyzing employment by industry, plastics and rubber parts manufacturing provided the largest number of current employees at 21,800. This was followed by transportation equipment manufacturing with 17,300 employees and primary and fabricated metals manufacturing with 16,400 employees. These figures highlight the labor-intensive nature of these manufacturing sub-sectors and their reliance on foreign investment for growth and employment.
Examining employment by country of origin, Mexico accounted for the largest number of current employees, with 54,600 individuals working in foreign-owned enterprises. Canada followed with 29,500 employees, and the United Kingdom with 26,800. This data points to strong employment linkages with neighboring countries and established trading partners. At the state level, California led in current employment generated by new FDI, with 37,200 employees. Illinois followed with 17,600 employees, and Texas with 16,500. These states, being major economic hubs, are naturally attractive to foreign investors seeking access to large labor pools and robust consumer markets.
Revisions to 2024 Data Highlight Growth Trajectory
The BEA’s release also included revisions to the 2024 foreign direct investment statistics, offering a more accurate picture of the preceding year’s investment activity and providing crucial context for the 2025 surge. Previously published first-year expenditures for 2024 stood at $151.0 billion. However, revised data now places this figure at $155.3 billion, an upward adjustment of $4.3 billion. This revision was primarily driven by increased expenditures on U.S. business acquisitions, which were revised from $143.0 billion to $146.4 billion. Expenditures for establishing new businesses and expanding existing ones were also revised upwards, from $6.3 billion to $6.4 billion and from $1.8 billion to $2.5 billion, respectively.
Similarly, planned total expenditures for 2024 were revised from $157.0 billion to $164.0 billion. These revisions indicate that the U.S. economy continued to attract strong foreign investment even before the significant jump observed in 2025. The upward revisions in both first-year and planned expenditures for 2024 underscore a consistent, positive trend in foreign investment, suggesting that the 2025 figures represent an acceleration rather than a sudden, isolated event. This recalibration of historical data provides a more reliable baseline for understanding the sustained growth trajectory of FDI in the United States.
Broader Economic Implications and Future Outlook
The substantial increase in foreign direct investment in 2025 carries significant implications for the U.S. economy. Firstly, it signifies robust investor confidence in the stability and future growth prospects of the American market, even amidst global economic uncertainties. The preference for acquisitions suggests that foreign investors are often seeking to leverage existing U.S. infrastructure, market share, and established customer bases, which can lead to operational efficiencies and quicker market penetration. This can also translate into significant capital infusions for U.S. companies, potentially enabling them to pursue new research and development, expand their product lines, or enhance their competitiveness.
The growth in employment directly linked to FDI is a critical benefit, contributing to lower unemployment rates and increased disposable income, which in turn can stimulate domestic consumption and further economic growth. The diversification of investment across various industries, from manufacturing to publishing, suggests that the appeal of the U.S. market is broad-based and not concentrated in a single sector. This can foster innovation and competition across the economy.
However, the dominance of acquisitions also raises questions about the long-term strategic integration of these foreign-owned entities and their commitment to local job retention and community investment. While BEA data tracks expenditures and employment, the broader impact on corporate decision-making and potential divestitures requires ongoing monitoring.
Looking ahead, the BEA’s projection for the next release in June 2027, focusing on 2026 FDI data, will be crucial in determining whether the remarkable growth seen in 2025 is sustained or represents a cyclical peak. Factors such as geopolitical stability, U.S. trade policies, and global economic growth will undoubtedly influence future investment flows. The BEA’s commitment to publishing detailed data tables, including breakdowns by industry, country, and state, as well as by type of investment (acquisitions, establishments, expansions), provides essential resources for policymakers, businesses, and researchers to understand and navigate the evolving landscape of foreign direct investment in the United States. The continued refinement of data collection and disclosure methods, as noted by the BEA, ensures that these statistics remain a valuable and reliable indicator of international economic engagement.