Layla Zulfa
In an era marked by escalating living costs and growing apprehension about retirement security, the AARP has pinpointed six fundamental financial metrics that individuals can utilize to gain a clear and actionable understanding of their financial well-being. These six numbers, ranging from the immediate reality of monthly cash flow to the long-term implications of retirement savings and debt, offer a comprehensive framework for identifying potential financial vulnerabilities early, when corrective measures are most effective. This initiative comes at a critical juncture, as a significant portion of the American workforce grapples with anxieties surrounding their future financial stability, particularly in the context of retirement.
The Growing Tide of Retirement Anxiety
The AARP’s emphasis on these financial indicators is underscored by a sobering report from the Employee Benefit Research Institute (EBRI). Their 2026 Retirement Confidence Survey revealed that approximately two in five U.S. workers harbor concerns about their ability to afford a comfortable retirement. This widespread anxiety is not an isolated phenomenon but rather a confluence of several challenging economic factors. Persistent inflation continues to erode purchasing power, making it harder for individuals to save and maintain their desired lifestyle. Simultaneously, discussions and uncertainties surrounding the future solvency and benefit levels of Social Security add another layer of apprehension. Compounding these concerns is the alarming rise in debt among older Americans, a trend that can significantly jeopardize their financial security in their later years.
Six Numbers to Navigate Financial Health
AARP’s report, accessible on their website, meticulously details each of the six critical numbers and explains their significance:
1. Monthly Cash Flow: The Immediate Financial Pulse
The most immediate indicator of financial health is monthly cash flow. This metric is calculated by subtracting all household expenses from an individual’s take-home pay. A negative cash flow, where expenses consistently exceed income, is a red flag signaling that spending is outpacing earnings. This situation necessitates a critical review of recurring costs, identifying areas for potential reduction, or exploring avenues to increase income. For many, this might involve re-evaluating subscriptions, optimizing utility usage, or considering side hustles. The EBRI survey also highlighted that a substantial percentage of workers are not confident in their ability to cover unexpected expenses, making positive monthly cash flow even more crucial for building a financial cushion.
2. Social Security Estimates: Projecting Future Income
Understanding potential Social Security benefits is a cornerstone of retirement planning. The Social Security Administration (SSA) provides an online portal where individuals can create an account and access personalized estimates of their future monthly payments. These estimates are based on an individual’s earnings history. AARP’s guidance emphasizes the strategic advantage of delaying Social Security claims. While benefits can commence as early as age 62, delaying the claim until full retirement age or even up to age 70 can significantly increase the monthly payout, providing a more robust income stream in retirement. This delayed claiming strategy is particularly impactful for individuals who may not have accumulated substantial personal retirement savings.
3. Retirement Savings: The Foundation for the Future
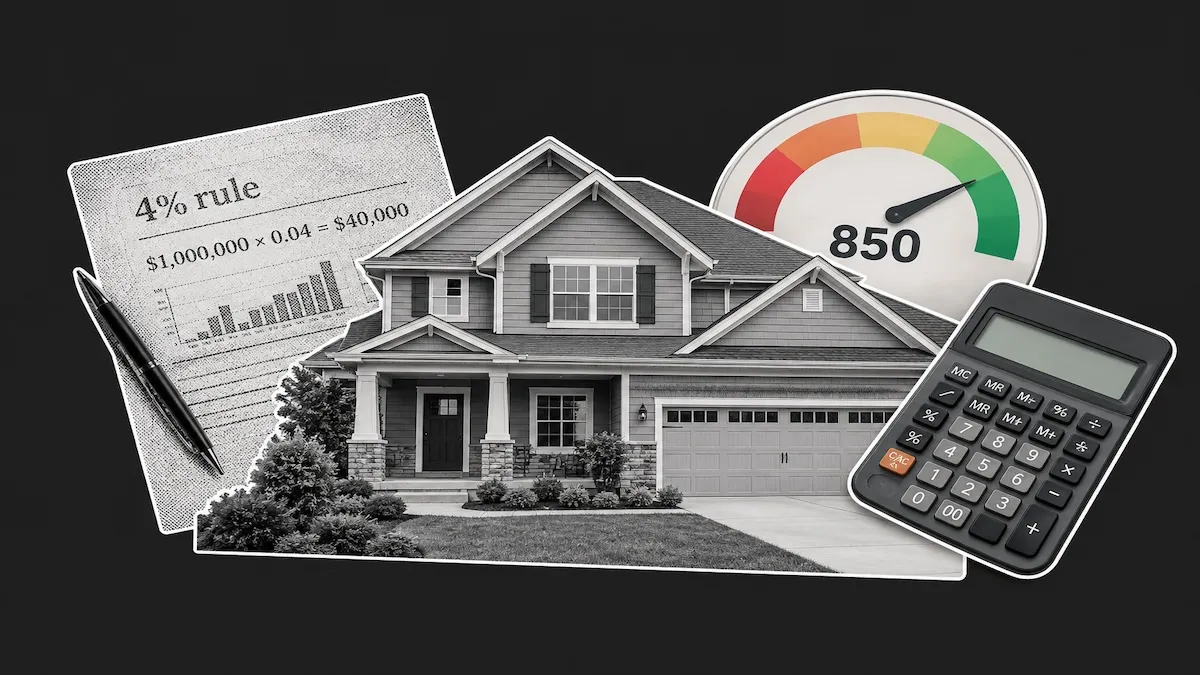
Assessing the adequacy of retirement savings is paramount. This involves aggregating balances from all retirement accounts, including 401(k)s, IRAs, pensions, and any other dedicated investment vehicles. This total sum is then compared against projected retirement expenses and expected income from sources like Social Security. AARP’s report utilizes a modified version of the widely recognized 4% rule as a benchmark. The 4% rule suggests that retirees can safely withdraw 4% of their total retirement savings in the first year of retirement, adjusting for inflation annually, with a high probability of their savings lasting for at least 30 years. For example, a savings balance of $1 million would theoretically support an annual income of $40,000. This metric helps individuals gauge whether their current savings trajectory aligns with their retirement lifestyle aspirations. Data from the Federal Reserve’s Survey of Consumer Finances consistently shows disparities in retirement savings across different demographics, underscoring the importance of this assessment for a broad spectrum of the population.
4. Credit Scores: The Gateway to Financial Opportunities
Credit scores, typically ranging from 300 to 850, serve as a crucial indicator of an individual’s creditworthiness. Major credit bureaus and scoring models, such as FICO and VantageScore, provide these scores to lenders. A strong credit score is essential for securing favorable terms on mortgages, auto loans, credit cards, and even for renting an apartment or obtaining certain types of insurance. AARP advises that improving one’s credit score can be achieved by consistently paying bills on time, reducing credit card balances to keep utilization low (ideally below 30%), and avoiding opening too many new credit accounts simultaneously. A low credit score can translate into higher interest rates and limited access to financial products, significantly impacting an individual’s ability to achieve financial goals.
5. High-Interest Debt: The Drag on Financial Progress
The burden of high-interest debt, particularly from credit cards, can rapidly erode financial progress. The compounding effect of high interest rates means that a significant portion of payments goes towards interest rather than principal, making it challenging to pay down the debt. AARP highlights two popular debt payoff strategies:
- The Avalanche Method: This strategy prioritizes paying off debts with the highest interest rates first, while making minimum payments on all other debts. Mathematically, this method saves the most money on interest over time.
- The Snowball Method: This approach focuses on paying off the smallest debts first, regardless of interest rate, while making minimum payments on larger debts. The psychological wins from quickly eliminating smaller debts can provide motivation to continue.
The prevalence of credit card debt among Americans remains a persistent concern. Data from the Federal Reserve Bank of New York has shown a steady increase in revolving credit balances in recent years, underscoring the urgency of addressing high-interest debt.
6. Debt-to-Income Ratio (DTI): A Measure of Borrowing Capacity
The debt-to-income ratio (DTI) is a critical metric, especially for individuals looking to secure loans for major purchases like homes. It compares an individual’s total monthly debt payments to their gross monthly income. Lenders typically prefer a DTI of 36% or lower, as it indicates that a borrower has a manageable amount of debt relative to their income. A higher DTI can signal financial strain and may limit an individual’s ability to qualify for new loans or may result in less favorable interest rates. Understanding and managing one’s DTI is essential for maintaining financial flexibility and achieving borrowing goals.
Proactive Financial Management: The Key to Long-Term Security
The AARP’s emphasis on these six numbers is not merely about assessing current financial standing; it is a call to action for proactive financial management. By regularly monitoring these metrics, individuals can gain invaluable insights into their financial trajectory. Early identification of potential issues, whether it’s a negative cash flow, insufficient retirement savings, or a high debt burden, provides the crucial advantage of time. With sufficient lead time, individuals can implement strategic adjustments to their spending habits, savings plans, and debt repayment strategies. This proactive approach can prevent minor financial hiccups from escalating into major crises, ultimately paving the way for greater financial security and a more comfortable future, particularly in retirement.
The report implicitly acknowledges that many individuals may feel overwhelmed by these numbers. However, the organization’s underlying message is one of empowerment. By breaking down financial health into these six digestible components, AARP aims to demystify personal finance and equip individuals with the knowledge and tools they need to take control of their financial destiny. The availability of resources through AARP and the SSA, along with guidance on debt management strategies, provides a roadmap for those seeking to improve their financial standing. As economic uncertainties persist, the ability to accurately assess and actively manage one’s financial health through these fundamental metrics becomes an increasingly indispensable skill for navigating the complexities of modern life.