Layla Zulfa
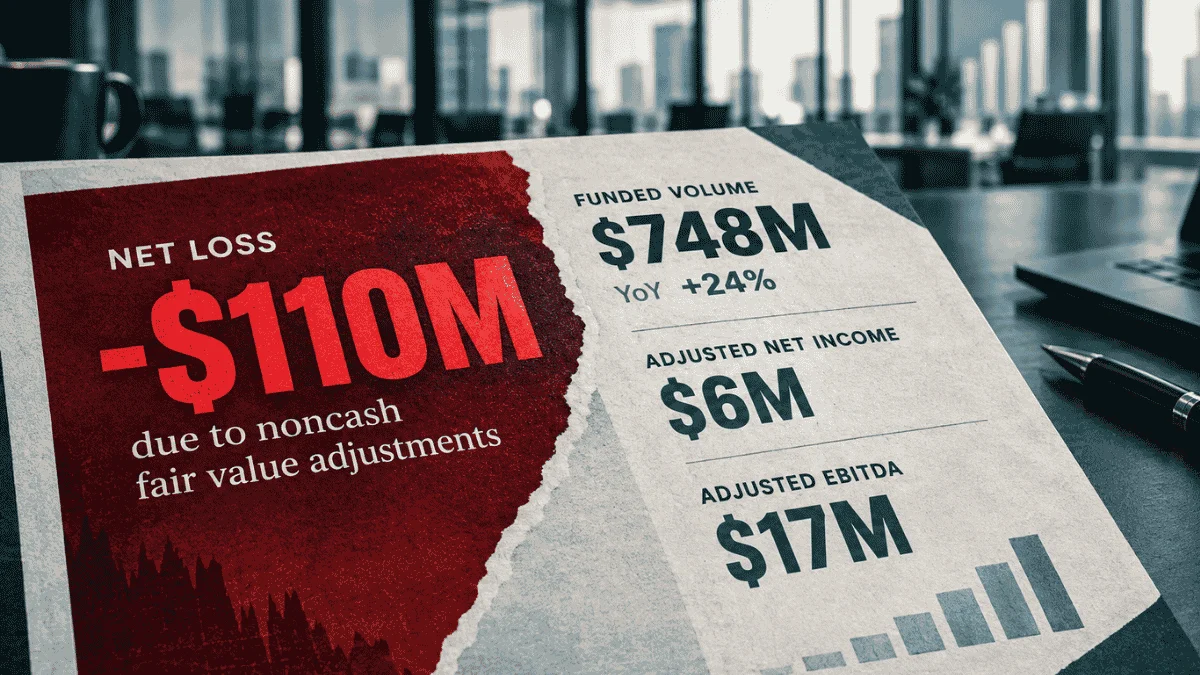
Finance of America (FOA) disclosed a significant net loss of $110 million for the third quarter of 2026, a period marked by considerable non-cash fair value adjustments that overshadowed the company’s growth in its home equity lending business. The Plano, Texas-based lender reported funded volume of $748 million for the quarter ending September 30, representing a robust 24% increase from $603 million in the same period of the preceding year. This positive trajectory extended to year-to-date figures, with funded volume reaching $2.07 billion, up 17% from the first nine months of 2025, underscoring sustained demand for its core products.
However, the reported net loss translated to a basic loss of $5.24 per share, a stark contrast to the 98 cents per share loss recorded in the third quarter of 2025. The primary driver behind this substantial quarterly net loss was $125 million in non-cash fair value adjustments, a financial accounting mechanism that reflects changes in the estimated market value of assets and liabilities. These adjustments, while not representing an immediate cash outflow or inflow, can significantly impact a company’s reported profitability in the short term.
On an adjusted basis, which aims to provide a clearer view of operational performance by excluding certain one-time or non-recurring items, Finance of America reported a net income of $6 million, or 28 cents per share. This figure, however, represents a considerable decrease from the $33 million in net income, or $1.33 per share, achieved in the third quarter of 2025. Furthermore, Adjusted EBITDA, a measure of a company’s operating performance before interest, taxes, depreciation, and amortization, stood at $17 million, down from $55 million in the prior-year period. This decline in adjusted profitability signals that underlying operational pressures were also at play, compounded by the fair value adjustments.
CEO Graham Fleming acknowledged the challenging environment in his statement, highlighting the platform’s resilience despite the headwinds. "The third quarter of 2026 demonstrated the continued strength of our platform, with funded origination volume growing 24% year over year," Fleming stated. "While higher interest rates drove near-term pressure on earnings, we believe this impact is temporary. We have already taken steps to improve margins." This sentiment was further elaborated during the company’s earnings call, where Fleming detailed the strategic responses being implemented to mitigate the impact of the evolving interest rate landscape.
The shift in monetary policy by the Federal Reserve from a period of rate cuts to a stance of rate hikes was identified as a key factor compressing margins. This pivot, driven by persistent inflationary pressures and a robust labor market, created a more challenging borrowing environment for consumers and subsequently impacted the profitability of mortgage lenders. Fleming assured investors that the company had proactively adjusted product pricing and expressed confidence in a return to historical margin levels by the first half of 2027.
"We have already made the necessary changes to product pricing, and we expect margins to return to historical levels in the first half of 2027," Fleming told investors. He further contextualized the market dynamics, noting that Finance of America had experienced consistent volume growth, averaging approximately 20% annually since 2023. "The third quarter was a challenging rate environment, with the 10-year Treasury yields increasing over 75 basis points during the quarter, a reaction to the Fed’s pivot to raising rates and elevated inflation," he added, underscoring the significant market shift that characterized the period.
Retirement Solutions Segment Shows Resilience Amidst Margin Compression
Finance of America’s retirement solutions segment, which focuses on home equity-based financing products, including reverse mortgages, emerged as a bright spot in terms of origination volume. This segment reported $748 million in funded volume during the third quarter of 2026, a notable 24% increase compared to the same quarter in 2025. This growth is particularly significant as it indicates sustained demand from an aging demographic seeking to leverage their home equity.
However, the segment’s profitability experienced a notable contraction. The retirement solutions revenue margin decreased to 9% in the third quarter of 2026, down from 11.3% in the third quarter of 2025 and below the historical average of 10.7% since the beginning of 2024. "Our retirement solutions revenue margin was impacted in the third quarter, decreasing to 9%, compared with 11.3% in the third quarter of 2025, and a historical average since the start of 2024 of 10.7%," Fleming explained on the earnings call. He reiterated the company’s belief that these impacts were temporary and did not alter the fundamental strength of the business.
Overall revenue for the retirement solutions segment totaled $67 million, a slight decrease of 1% from the prior-year period and a dip from the $74 million generated in the second quarter of 2026. Pretax income within this segment fell to $3 million, a significant decline from $10 million recorded a year earlier. Similarly, adjusted net income for the segment decreased to $9 million, down from $20 million in the third quarter of 2025. The company attributed this profitability squeeze primarily to pressure on origination margins, directly linked to the rise in benchmark interest rates. The implementation of product and pricing adjustments was highlighted as a key strategy to counteract these effects, with expectations for margins to rebound.
For the first nine months of 2026, the retirement solutions segment demonstrated robust top-line growth. Funded volume reached $2.07 billion, an increase of 17% year over year. Revenue for the segment also saw a healthy increase, rising 14% to $208 million. This sustained volume growth over a longer period suggests a growing market acceptance and strategic positioning for FOA’s retirement solutions.
Kristen Sieffert, President of Finance of America, provided further granular detail on volume trends across different product offerings within the retirement solutions segment. "Since 2023, our submission volumes have increased by 21% annually, while our funded volume has grown by 20% annually. This is across our product suite, as HECM volume is up 14% year over year, HomeSafe first liens are up 15%, and HomeSafe seconds are up 63%," Sieffert stated during the call, illustrating the broad-based growth across its core offerings. The significant increase in HomeSafe second liens, in particular, may indicate a growing preference for flexible financing options that allow homeowners to access equity while retaining their primary mortgage.
Portfolio Management Segment Faces Significant Fair Value Headwinds
The portfolio management segment of Finance of America, which derives revenue from net interest income and fair value changes on its portfolio assets, reported a significant pretax loss of $138 million in the third quarter of 2026. This represents a substantial deterioration from the $11 million pretax loss experienced in the same quarter of 2025. The primary driver for this intensified loss was negative non-cash fair value adjustments on the company’s retained interests in securitizations. These retained interests, often representing a portion of the underlying loan pool sold into a securitization, are sensitive to changes in interest rates and prepayment speeds, leading to potential valuation volatility.
On an adjusted basis, the portfolio management segment reported adjusted net income of $11 million, a notable decrease from $30 million in the prior year. This indicates that while the headline pretax loss was heavily influenced by non-cash accounting items, underlying operational profitability also saw a decline.
Despite the profitability challenges, assets under management within this segment continued to grow, increasing by 23% year over year to $37.4 billion. This expansion was fueled by both new originations and the strategic acquisition of Onity Mortgage Corp.’s HECM servicing portfolio on July 1, 2026. This acquisition likely contributed to an increase in the volume of assets managed, even as their valuation faced headwinds.
For the first nine months of 2026, the portfolio management segment recorded a cumulative pretax loss of $128 million. This contrasts sharply with the $202 million pretax income reported in the same period of 2025, highlighting the significant shift in performance due to market conditions. Adjusted net income for the nine-month period totaled $57 million, down from $66 million in the prior year.
Financial Position and Outlook
Finance of America concluded the third quarter of 2026 with a healthy cash position of $118 million, an increase from $85 million at the end of June. This growth in cash and cash equivalents was attributed to cash generated from originations and capital markets activities, indicating strong operational cash flow generation despite the reported net loss.
The company’s total equity stood at $307 million as of September 30, 2026, with $259 million attributable to common stock. The book value per common share was reported at $28.08. These figures provide a snapshot of the company’s financial health and its underlying asset base.
Looking ahead, Finance of America announced its intention to complete a $60 million paydown of senior secured notes in November. This deleveraging action is a positive step towards strengthening the company’s balance sheet and reducing future interest expenses.
For the fourth quarter of 2026, Chief Financial Officer Matt Engel projected funded volume to range between $3.1 billion and $3.4 billion. This outlook is underpinned by several favorable factors, including consumer demographics, the company’s diverse product offerings, and ongoing improvements in conversion rates. "We expect funded volume to reach $3.1 billion to $3.4 billion, a range supported by consumer demographics, our product breadth, and ongoing conversion improvements," Engel stated, conveying confidence in the company’s near-term growth prospects. The sustained demand from the growing senior population, coupled with FOA’s established product suite, suggests a continued market opportunity.
The company’s performance in the third quarter of 2026 serves as a case study in how non-cash accounting adjustments and a rapidly shifting interest rate environment can impact even growing businesses. While the headline net loss is significant, the underlying operational growth in its core retirement solutions business and the company’s proactive steps to manage margins and strengthen its balance sheet provide a basis for optimism regarding its long-term trajectory. The focus now shifts to the execution of these strategies and the company’s ability to navigate the prevailing economic conditions to achieve its targeted return to historical profitability levels.