

 Candice Horbacz
A vigorous debate is unfolding among prominent tax scholars and policymakers regarding the optimal structure and rates of corporate taxation, particularly in an evolving global economic landscape. At the heart of this discussion is a provocative argument advanced by legal scholar Reuven Avi-Yonah in a forthcoming Tax Law Review article titled “Taxation and Deglobalization.” Avi-Yonah posits that with certain fundamental reforms to the corporate tax base, concerns about the economic distortions typically associated with high corporate income tax rates could largely dissipate, potentially clearing the path for an astonishing 80 percent top marginal rate. This perspective, while extreme in its proposed rate, aligns with a broader intellectual current among analysts like Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby, who advocate for the principle of "fix the base, raise the rate." However, a careful examination reveals that while base-broadening reforms are indeed beneficial, the notion that they would completely neutralize the economic trade-offs of an exceptionally high corporate tax rate is met with significant skepticism from other economic experts, including those who acknowledge the benefits of robust tax reform.
The Case for Base Reform and Higher Rates
Avi-Yonah’s central thesis rests on the idea that if the corporate tax base is meticulously designed to eliminate inefficiencies and loopholes, the negative economic consequences of a high corporate income tax rate would no longer apply to "normal" business activities. His article specifically entertains an 80 percent top rate for global profits exceeding $10 billion, a figure dramatically higher than the rates typically discussed by other proponents of base reform. The rationale behind this aggressive rate is to capture "excessive rents"—supernormal returns often associated with monopolistic or cartel-like behavior—without discouraging productive investment. He argues that in a "deglobalizing economy," such a high tax rate, applied on a worldwide basis, becomes "more feasible" because corporations face greater difficulty in relocating their profits or headquarters without forfeiting access to the lucrative U.S. market.
A cornerstone of Avi-Yonah’s proposed reforms, and indeed a widely lauded pro-growth tax policy, is full expensing of investment. Full expensing allows businesses to immediately deduct the entire cost of certain investments in new or improved technology, equipment, or buildings. This reform is designed to eliminate a bias in the tax code that currently favors consumption over investment, thereby incentivizing companies to invest more, which theoretically leads to increased worker productivity, higher wages, and job creation in the long run. Under a perfectly designed system with full expensing, the tax rate theoretically drops out of the calculation for the "user cost of capital"—the minimum pre-tax return required for an investment to be undertaken—suggesting that the tax rate would no longer distort investment decisions.
Beyond full expensing, Avi-Yonah’s proposals aim to address the pervasive issue of profit shifting. Profit shifting occurs when multinational corporations strategically move the declared location of their profits from high-tax jurisdictions to low-tax havens to reduce their overall tax burden. This practice necessitates higher tax rates to collect the same amount of revenue and introduces non-neutralities that distort investment decisions, as some businesses are better positioned to benefit from such maneuvers than others. It also compels firms to expend resources on unproductive administrative and compliance activities.
To counter profit shifting, many experts, including Avi-Yonah, advocate for reforms that move the U.S. tax system towards a destination-based cash flow tax (DBCFT). A DBCFT fundamentally alters how multinational profits are taxed by reorienting the tax base towards where goods and services are consumed rather than produced. Key components of a DBCFT include denying tax deductions for imports (including service imports) and applying a zero tax rate on export income—a mechanism collectively known as "border adjustment." This border adjustment effectively closes off major avenues for profit shifting by making the location of production less relevant for tax purposes. Coupled with full expensing and denying interest expense deductions (together constituting "cash flow taxation"), a DBCFT significantly reduces the distortive effects of taxation on investment decisions. Avi-Yonah’s specific proposals, which involve a 10 percent tariff instead of denying import deductibility and a digital services tax, represent variations that generally align with the broader objectives of a DBCFT.
The Counter-Argument: Limits to Tax Rate Indifference
While the economic benefits of full expensing and robust anti-profit shifting measures like those inherent in a DBCFT are widely acknowledged, the leap to concluding that these reforms can justify an 80 percent corporate tax rate is seen by many as a dangerous oversimplification. The core criticism is that while such reforms can significantly improve the tax base and reduce the economic cost of existing or modestly higher rates, they do not eliminate the fundamental trade-offs involved in adopting an exceptionally high corporate income tax rate.
The standard economic framework for analyzing investment decisions, known as the Hall-Jorgenson framework, uses the "user cost of capital" formula. In its simplified form, this formula suggests that if full expensing (where the present value of cost-recovery deductions per dollar invested, ‘z’, equals 1) is implemented, the tax rate (‘τ’) appears to cancel out of the equation, leaving only the required after-tax return (‘r’) and economic depreciation (‘δ’) as determinants of the pre-tax return (‘c’). However, this standard framework does not fully capture the complexities and nuances of the real-world tax system and investment choices, especially when considering drastic rate changes.
One significant departure from this idealized model lies in the realm of innovation and entrepreneurship, particularly regarding the implicit wages of founders. Many startups are founded by entrepreneurs who work for less than their market wage—their "sweat equity"—while building their businesses. This unpaid effort represents a real economic cost, an opportunity cost, which is not deductible for business tax purposes. For example, an entrepreneur foregoing a market salary to build a company cannot deduct that foregone income from the company’s taxable profits. As Nobel laureate Gary Becker famously noted, human capital is a form of investment, yet its ‘expensing’ for tax purposes is practically impossible. This inherent inability to fully allow and price a business deduction for such opportunity costs means that the tax rate will not fully cancel out, even under full expensing.
To illustrate this, an extension of the user cost formula shows that if an investment requires both explicit capital spending (fully expensed) and a complementary input of the founder’s unexpensed effort (with opportunity cost ‘ψ’ per dollar of capital), then raising the business rate from, say, 21 percent to 80 percent would dramatically increase the required pre-tax return. Drawing on estimates from scholars like Bhandari and McGrattan, which suggest sweat equity can roughly match fixed asset investment, and assuming a 50 percent labor tax rate on that foregone income, raising the corporate rate from 21 percent to 80 percent could necessitate an approximately 114 percent increase in the required pre-tax return. Crucially, the cost of raising the rate is modest when the rate is low but escalates sharply when the rate is already high. For instance, a 10-percentage-point increase from 21 percent to 31 percent might increase the required return by about 6 percent, whereas the same 10-percentage-point increase from 70 percent to 80 percent could boost the required return by about 31 percent. This demonstrates a non-linear relationship where higher rates impose disproportionately larger burdens.
Another critical real-world departure concerns the asymmetry of loss offsets. For full expensing to truly render the tax rate irrelevant, businesses must be able to fully and immediately deduct all investment costs, even if they incur losses. In reality, deductions can be delayed if a business is in a loss position, or even lost entirely if the business never turns a profit. This is particularly relevant for startups and innovative ventures, which often operate at a loss for extended periods. Data from venture-backed startups between 1985 and 2009, for example, show that 55 percent were ultimately terminated at a loss. In such scenarios, the theoretical benefits of full expensing are diminished, and the tax rate still influences investment decisions by increasing the risk and effective cost of capital for businesses that may not immediately generate taxable income.
Furthermore, Avi-Yonah’s specific proposal for a progressive corporate tax rate structure—lower marginal rates for profits below $10 billion and an 80 percent rate for profits above—introduces additional complexities. This progressive structure can create intertemporal asymmetry over the life cycle of a firm. If early-stage investment costs are expensed and relieved at a lower marginal rate (e.g., 21 percent), but later profits are taxed at a much higher rate (e.g., 80 percent), this effectively raises the user cost of capital. The exact magnitude of this distortion depends on the timing of profits and losses, discounting effects, and the firm’s ability to strategically defer tax deductions, such as by electing out of bonus depreciation, which itself reintroduces the tax rate into the user cost calculation.
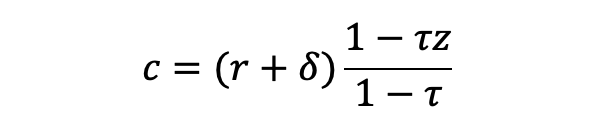
Broader Economic Implications and Risks
Beyond these theoretical and practical limitations of the "rate doesn’t matter" argument, an 80 percent corporate tax rate carries profound broader economic implications.
- Investment Disincentives: Even with a reformed base, such an extraordinarily high rate would likely act as a severe disincentive for both domestic and foreign direct investment (FDI). Capital is inherently mobile, and despite "deglobalization" trends, the U.S. would become an extreme outlier in the global tax landscape. The average corporate income tax rate among OECD countries stood at approximately 23.5% in 2023, with the U.S. rate currently at 21% following the Tax Cuts and Jobs Act of 2017 (down from 35% previously). An 80% rate would make the U.S. significantly less attractive for capital allocation, potentially leading to slower capital accumulation, reduced productivity growth, and ultimately, lower wage increases for workers.
- Competitiveness Concerns: While Avi-Yonah argues that a deglobalizing economy makes it harder for companies to move, an 80% rate would undoubtedly spur companies to find new ways to minimize their U.S. taxable presence or simply avoid investing in the U.S. altogether. This could manifest in reduced expansion, relocation of research and development, or a reluctance for new businesses to establish significant operations within the U.S. This would erode the U.S.’s global economic competitiveness.
- Innovation and Entrepreneurship: The specific issues related to implicit wages and asymmetric loss offsets highlighted above mean that innovative startups and growth-oriented companies would be disproportionately affected. These firms are critical engines of future economic growth, and a tax regime that heavily penalizes their early-stage, often unprofitable, investment efforts could stifle the very innovation it seeks to nurture.
- Revenue Volatility and Economic Stability: A system heavily reliant on taxing "supernormal returns" at an 80 percent rate could lead to significant revenue volatility. Supernormal profits are often concentrated in specific sectors or fluctuate heavily with economic cycles and market conditions. This could make government budgeting and fiscal planning less predictable.
- Increased Complexity and Administration: Implementing a highly progressive corporate tax rate structure with specific profit thresholds (e.g., $10 billion) would introduce new layers of complexity for businesses and tax administrators. It could create incentives for companies to structure their operations to stay below certain thresholds, or to engage in aggressive accounting practices to minimize reported profits subject to the highest rates, potentially leading to new forms of tax avoidance.
Conclusion
The intellectual current advocating for "fix the base, raise the rate" offers valuable insights into improving the efficiency and equity of the U.S. tax system. Reforms like full expensing and measures to curb profit shifting, such as those embodied in a destination-based cash flow tax, are genuinely pro-growth and can significantly reduce economic distortions. These improvements would undoubtedly lower the economic cost of the current corporate tax rate and could accommodate modest rate increases without severe negative consequences.
However, the assertion that such base reforms would eliminate all worries about the economic effects of an arbitrarily high corporate income tax rate, particularly one as extreme as 80 percent, is a miscalculation. Real-world complexities, such as the non-deductibility of entrepreneurial effort, the asymmetry of loss offsets, and the distortive effects of progressive rate structures on firm lifecycles, ensure that the tax rate will always retain a significant influence on investment decisions.
Policymakers must carefully weigh the commendable goal of capturing excessive rents and ensuring corporate fairness against the substantial risks of stifling investment, innovation, and overall economic growth. While improving the tax base is a crucial and beneficial endeavor, it does not provide a "magic bullet" that allows for the complete disregard of the fundamental economic principles governing corporate tax rates. A balanced approach that combines judicious base reforms with competitive and economically sound rates remains essential for fostering a robust and dynamic economy.









