Candice Horbacz
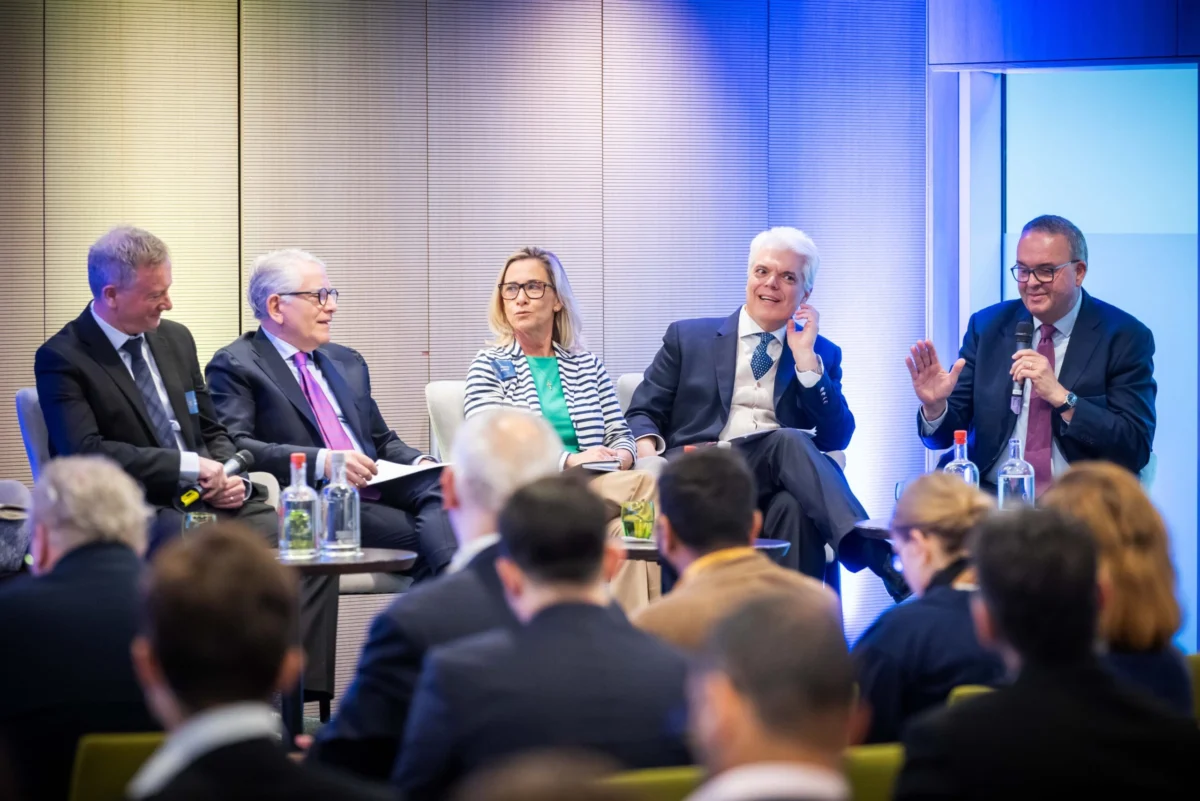
The intricate landscape of global taxation is undergoing a profound transformation, driven by technological advancements, shifting political priorities, and an intensified focus on international cooperation and competition. Recent discussions among policymakers, industry leaders, and tax experts have underscored the urgency of addressing these multifaceted challenges, particularly concerning the integration of artificial intelligence, the dynamic interplay of national electoral outcomes on fiscal policy, the ongoing evolution of European Union tax directives, and the critical balance between investment attraction and fair competition in an era marked by trade tensions. These pivotal themes formed the core agenda of a recent high-level forum, offering crucial insights into the mechanisms shaping the fiscal policies of tomorrow.
The AI Revolution and the Future of Tax Revenue
A central focus of the forum’s keynote address, titled "AI, disruption, and the future of tax: labor revenue, competition, and innovation," delved into the profound implications of artificial intelligence (AI) on traditional tax bases and economic structures. As AI technologies become increasingly sophisticated, their capacity to automate tasks previously performed by human labor poses a significant challenge to government revenue streams heavily reliant on income and payroll taxes. Studies by institutions like the McKinsey Global Institute project that automation could displace tens of millions of jobs globally by 2030, while simultaneously creating new ones. However, the net effect on overall labor force participation and, consequently, on the taxable wage base remains a subject of intense debate and research.
The discussion highlighted that AI-driven disruption is not merely about job displacement; it reconfigures the very nature of value creation. Companies leveraging AI often generate significant profits with fewer human employees, challenging existing corporate tax frameworks designed for an industrial economy. This raises fundamental questions about where economic value is created, how it should be taxed, and whether current systems adequately capture the wealth generated by digital platforms and AI algorithms. Experts debated whether new tax instruments, such as a "robot tax" on automated production or revised digital services taxes, might be necessary to ensure equitable wealth distribution and stable public finances. The underlying challenge is to design tax policies that foster innovation and competitiveness in the AI sector without stifling its growth, while simultaneously ensuring that the benefits of this technological revolution are broadly shared. Policymakers are grappling with the dual imperative of attracting AI investment through favorable tax regimes, such as enhanced R&D tax credits, while also preventing a "race to the bottom" in corporate taxation that could undermine public services. The imperative is to strike a delicate balance that encourages technological advancement within national borders, thereby securing future economic prosperity and fiscal stability.
French Tax Policy: Post-Election Trajectories and EU Alignment
The forum’s first session, conducted in French, honed in on "How Elections Will Shape French Tax Policy," examining the prospective impact of a new president’s tax agenda on the national budget and France’s commitments within the European Union. France, a founding member of the EU and a significant economic power, often finds its domestic fiscal choices resonating across the bloc. With national elections periodically bringing shifts in political leadership, the potential for significant changes in tax philosophy becomes a critical point of analysis.
Historically, French presidential candidates often present divergent economic platforms. For instance, right-leaning candidates might advocate for corporate tax cuts, reductions in social security contributions, and deregulation to stimulate business investment and employment, echoing sentiments for greater economic competitiveness. Conversely, left-leaning candidates typically prioritize social solidarity, proposing wealth taxes, increased taxes on higher incomes, and robust public spending funded by progressive taxation. The implications of these varying approaches on the French budget are substantial. A focus on tax cuts could exacerbate the national debt, which stood at approximately 111.9% of GDP in 2023, while increased social spending would demand sustainable revenue generation.
Beyond domestic concerns, France’s tax agenda holds significant sway over EU priorities. As a vocal proponent of deeper European integration, France’s stance on issues like the harmonization of corporate tax bases, the implementation of digital services taxes, and the future of EU own resources (mechanisms for the EU to fund its budget directly) can either accelerate or impede broader European fiscal initiatives. The session critically explored how a new French administration might leverage tax policy to enhance France’s competitiveness within the Eurozone. This could involve targeted tax incentives for specific industries, simplification of the tax code to reduce administrative burdens for businesses, or investments in infrastructure and education to attract foreign direct investment (FDI). Analysts emphasized that any strategic tax reforms would need to be carefully calibrated to comply with EU state aid rules and avoid accusations of unfair tax competition, reflecting the complex interplay between national sovereignty and supranational economic governance. The outcome of such elections, therefore, is not merely a domestic affair but a significant determinant of the trajectory of European economic policy.
Navigating the Labyrinth of EU Tax Policy Developments
The second session provided a comprehensive "update on EU Tax Policy," shedding light on several critical initiatives designed to enhance fiscal stability, transparency, and fairness across the 27-member bloc. The European Union is continually refining its tax framework to adapt to global economic changes and combat cross-border tax evasion and avoidance.
A key element of discussion was the Multiannual Financial Framework (MFF) and own resources. The MFF represents the EU’s long-term budget, typically spanning seven years, which sets spending ceilings for various policy areas. The debate around "own resources" concerns how the EU funds this budget. Traditionally, it has relied on contributions from member states based on their Gross National Income and a share of customs duties. However, there’s a growing push for new, more direct sources of revenue, such as a levy on plastics, a share of revenues from the Emissions Trading System, and a digital levy. These proposals aim to reduce reliance on national contributions, enhance the EU’s financial autonomy, and align its budget with strategic priorities like the green and digital transitions. The current MFF (2021-2027) is undergoing a mid-term review, prompting intense negotiations on its potential revision and the introduction of new own resources, with a timeline for agreement expected by late 2024 or early 2025.
The Omnibus package was also highlighted. While not a single, monolithic piece of legislation, this term often refers to a series of amendments or updates to existing EU tax directives, designed to ensure their coherence, close loopholes, or adapt them to new international standards. These packages frequently include revisions to the Anti-Tax Avoidance Directives (ATADs) or the Directive on Administrative Cooperation (DAC), reflecting the EU’s continuous effort to strengthen its arsenal against aggressive tax planning.
A significant update focused on the DAC recast, particularly the anticipated DAC8. The Directive on Administrative Cooperation (DAC) is the cornerstone of tax transparency in the EU, providing a framework for the mandatory automatic exchange of information between member states’ tax authorities. DAC8, which entered into force in 2024, expands the scope of reporting requirements to include crypto-asset service providers and e-money institutions, obliging them to report information on EU clients’ crypto-asset transactions and holdings. This measure is a direct response to the increasing use of crypto-assets, which previously operated in a regulatory grey area, for potential tax evasion. Further potential iterations, such as DAC9, are already being discussed to cover other asset classes or financial products, demonstrating the EU’s proactive stance on adapting tax transparency to the evolving digital economy.
Progress on Pillar One of the OECD/G20 Inclusive Framework on Base Erosion and Profit Shifting (BEPS) was another critical point. Pillar One aims to reallocate taxing rights over a portion of the profits of the largest and most profitable multinational enterprises (MNEs) to market jurisdictions where their users and customers are located, regardless of physical presence. This initiative is designed to address the challenges of taxing a globalized and digitalized economy fairly. While significant political agreement was reached in 2021, the practical implementation through a multilateral convention has faced delays due to complex technical details and differing national interests. The EU remains committed to a multilateral solution, but has also explored options for a regional digital services tax should the global agreement falter, though such unilateral measures risk trade disputes.
Finally, the Mobility Map was discussed, referring to initiatives addressing the taxation of cross-border workers, digital nomads, and highly mobile individuals within the Single Market. As remote work becomes more prevalent and the workforce increasingly mobile, existing tax rules, often based on physical presence, struggle to keep pace. The Mobility Map aims to develop clearer, more coherent tax rules to avoid double taxation, reduce administrative burdens for individuals and businesses, and prevent unintended tax advantages or disadvantages for those working across EU borders. This includes examining issues related to social security contributions, residency rules, and the allocation of taxing rights between member states. The goal is to facilitate free movement of labor while ensuring fair and effective taxation, supporting the integrity of member states’ tax bases.
Investment, Competition, and Trade Wars: A New Global Economic Order
The forum’s third session, "Investment and Competition in an Era of Trade Wars," explored the intricate relationship between foreign direct investment (FDI), the newly enacted global minimum tax, and rising protectionist measures. This discussion highlighted how these forces are reshaping global supply chains and the very concept of international tax competition.
A primary focus was the role of FDI under Pillar Two of the OECD/G20 Inclusive Framework. Pillar Two introduces a global minimum corporate tax rate of 15% for large multinational enterprises (MNEs) with revenues exceeding €750 million. This landmark agreement, which began taking effect in various jurisdictions in 2024, fundamentally alters the landscape of international tax planning. For decades, countries competed to attract FDI by offering low corporate tax rates or generous tax incentives. Pillar Two significantly curtails this "race to the bottom" by ensuring that if an MNE pays less than 15% effective tax in one jurisdiction, its home country or other jurisdictions can impose a "top-up tax" to reach the minimum.
The implications for FDI are profound. While low headline tax rates will no longer be the primary differentiator, countries will still compete on other factors, such as the stability of their legal and regulatory frameworks, the availability of skilled labor, infrastructure quality, and the effectiveness of targeted, transparent tax incentives that are compliant with Pillar Two (e.g., qualified refundable tax credits for R&D). Jurisdictions that have historically relied heavily on extremely low tax rates to attract investment, such as certain small economies or tax havens, are now compelled to re-evaluate their economic models and seek new avenues for growth and revenue generation. The overall impact is expected to shift FDI decisions towards locations offering genuine economic value rather than purely tax-driven advantages.
Concurrently, the global economic environment is increasingly characterized by rising tariffs and protectionist trade policies. The past decade has seen a resurgence of trade tensions, exemplified by the US-China trade war, Brexit-related trade barriers, and increasing scrutiny of global supply chain vulnerabilities, particularly in critical sectors like semiconductors and healthcare. Tariffs, quotas, and other non-tariff barriers directly increase the cost of doing business across borders, compelling MNEs to re-evaluate their global manufacturing and distribution strategies. This often leads to nearshoring or reshoring production, diversifying supply chains away from single dominant suppliers, and a greater emphasis on regional economic blocs. The interplay between Pillar Two and rising tariffs is complex: while Pillar Two reduces tax arbitrage opportunities, tariffs can create new economic incentives for companies to relocate production closer to consumer markets, potentially overriding purely tax-driven investment decisions.
The session also delved into the concept of "healthy tax competition." In the wake of Pillar Two, the discourse has shifted from outright tax rate competition to a more nuanced rivalry focused on attracting quality investment. Healthy tax competition, as defined by experts, involves jurisdictions competing on genuine economic fundamentals and providing transparent, non-distortive tax incentives that encourage real economic activity, innovation, and job creation. This contrasts sharply with "harmful tax competition," which typically involves aggressive tax avoidance schemes, opaque regimes, or sweetheart deals designed to divert profits without substantive economic activity. The challenge for policymakers is to design tax systems that are attractive to investors while maintaining fairness, ensuring sufficient public revenue, and adhering to evolving international standards. This involves fostering an environment where competition centers on factors like regulatory efficiency, digital infrastructure, human capital development, and targeted R&D support, rather than merely offering the lowest possible effective tax rate.
Conclusion: A New Era of Fiscal Governance
The discussions at this high-level forum collectively painted a picture of a global tax landscape in flux. From the disruptive potential of AI to the intricate dance of national elections and EU directives, and the reshaping of investment flows by global minimum taxes and trade protectionism, the challenges facing policymakers are unprecedented. The imperative is clear: traditional tax frameworks, often conceived in a bygone industrial era, are no longer adequate for a digitalized, globalized, and increasingly fragmented world.
The ongoing evolution of international tax rules, exemplified by Pillar One and Pillar Two, signifies a global effort to achieve greater fairness and stability. However, their implementation remains complex, requiring continuous multilateral cooperation and political will. National governments, in turn, must adapt their fiscal strategies to remain competitive while safeguarding their revenue bases and addressing social equity concerns. The future of taxation will demand agility, foresight, and an unwavering commitment to international collaboration to ensure that the benefits of economic progress are widely shared and that public finances remain robust enough to address the challenges of the 21st century. These dialogues underscore that tax policy is not merely a technical exercise but a crucial lever for shaping economies, fostering innovation, and promoting social cohesion in an ever-changing world.